
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Industrial Fasteners Market Size 2024 | USD 28,843.26 million |
| U.S. Industrial Fasteners Market, CAGR | 6.23% |
| U.S. Industrial Fasteners Market Size 2032 | USD 46,758.28 million |
Market Overview:
The U.S. Industrial Fasteners Market is projected to grow from USD 28,843.26 million in 2024 to an estimated USD 46,758.28 million by 2032, with a compound annual growth rate (CAGR) of 6.23% from 2024 to 2032.
Several key factors are propelling the growth of the U.S. industrial fasteners market. The resurgence of domestic manufacturing, particularly in the automotive and aerospace industries, has significantly increased the demand for high-quality fasteners. As manufacturers strive to improve operational efficiency, the need for reliable and durable fastening solutions has intensified. Additionally, the ongoing infrastructure development, encompassing roadways, bridges, and commercial buildings, necessitates a substantial volume of fasteners, thereby driving market growth. This trend is further supported by rising urbanization, leading to increased demand for residential and commercial construction. Technological advancements, such as the adoption of smart manufacturing and automation, are also contributing to the demand for precision-engineered fasteners. Automation not only ensures higher production speed but also enhances the consistency and quality of fasteners. Moreover, the rise in green construction practices is fostering the development of sustainable and recyclable fastening solutions, aligning with environmental considerations and regulatory requirements.
Geographically, the U.S. industrial fasteners market exhibits regional variations influenced by the concentration of manufacturing activities and infrastructure projects. The Midwest region, often referred to as the "Rust Belt," remains the dominant market, accounting for a significant share due to its dense concentration of automotive, aerospace, machinery, and construction industries. This region's established infrastructure and historical significance in manufacturing continue to make it a key player in the fasteners market. The Southeast region is emerging as the fastest-growing market, driven by the establishment of major automotive manufacturing facilities in states like Alabama, Georgia, South Carolina, and Tennessee. These states are attracting new investments due to their competitive labor costs and favorable business environments. This regional growth is further supported by favorable economic conditions and strategic investments in manufacturing capabilities, as well as the proximity to key ports for import/export.
Market Insights:
- The U.S. Industrial Fasteners Market is projected to grow from USD 28,843.26 million in 2024 to USD 46,758.28 million by 2032, at a CAGR of 6.23%.
- Key growth drivers include the resurgence of domestic manufacturing in automotive and aerospace sectors, leading to heightened demand for durable and high-quality fasteners.
- Infrastructure development, including roadways, bridges, and commercial buildings, is creating substantial demand for fasteners, particularly as urbanization continues.
- Technological advancements such as automation and smart manufacturing are improving fastener production efficiency, meeting the growing demand for precision-engineered solutions.
- Sustainability and green construction practices are promoting eco-friendly and recyclable fasteners, which aligns with environmental regulations and consumer preferences for green building materials.
- Fluctuating raw material prices, particularly steel and aluminum, pose a challenge for manufacturers, as unpredictable production costs impact profitability.
- The U.S. industrial fasteners market faces intense competition, with both established players and new entrants vying for market share, pushing innovation and pricing strategies.
Market Drivers:
Resurgence of Domestic Manufacturing
One of the primary drivers behind the growth of the U.S. industrial fasteners market is the resurgence of domestic manufacturing. Particularly in the automotive and aerospace sectors, U.S. manufacturers are increasingly prioritizing onshore production to address supply chain challenges and meet growing demand. For instance, leading companies like Boeing and Lockheed Martin are major consumers of high-quality fasteners, with Boeing’s 737 MAX series requiring thousands of specialized fasteners to ensure structural integrity and safety. The need for high-quality, durable fasteners has escalated as these industries continue to innovate and scale production. Fasteners play a critical role in ensuring the integrity and safety of automotive components, airframes, and other machinery, making them indispensable in the manufacturing process. This resurgence is not only a result of increased domestic production but also reflects the ongoing efforts of the U.S. government to bolster local manufacturing capabilities through policies and incentives, further driving demand for industrial fasteners.
Infrastructure Development and Urbanization
The ongoing infrastructure development across the United States is another significant driver of the industrial fasteners market. As the government continues to invest in upgrading transportation networks, bridges, and urban construction projects, the demand for fasteners has risen considerably. The push for sustainable infrastructure development, including green buildings and energy-efficient construction, has also contributed to this trend. As urbanization continues, particularly in growing metropolitan areas, the need for both residential and commercial construction projects increases. This creates a substantial demand for industrial fasteners, used extensively in both new builds and renovation projects, including roads, bridges, and high-rise buildings.
Technological Advancements in Manufacturing
Technological advancements in manufacturing processes have greatly impacted the industrial fasteners market in the U.S. The adoption of automation and smart manufacturing techniques has significantly enhanced the precision and efficiency of fastener production. For example, AI-driven automation in aerospace fastener manufacturing has improved quality control and reduced design cycle times, supporting the production of fasteners that meet the rigorous demands of the industry. These innovations enable manufacturers to meet increasingly complex demands for fasteners that can withstand high levels of stress, extreme temperatures, and corrosive environments. The development of new materials, such as corrosion-resistant alloys and advanced composite materials, has also influenced fastener production. These innovations cater to a broader range of applications, from aerospace and defense to heavy machinery, ensuring that U.S. manufacturers remain competitive in an evolving global marketplace.
Sustainability and Green Construction Practices
Sustainability has become an essential focus in the U.S. construction and manufacturing industries, further driving the demand for eco-friendly fasteners. With increasing pressure to adhere to environmental regulations, manufacturers are developing fasteners that are both recyclable and made from sustainable materials. Green construction practices, including the use of energy-efficient designs and eco-friendly building materials, have fostered the adoption of sustainable fastening solutions. Additionally, regulations promoting environmentally conscious building practices, such as LEED (Leadership in Energy and Environmental Design) certification, have encouraged the use of fasteners that contribute to the overall environmental performance of construction projects. As the demand for green solutions increases, the market for sustainable industrial fasteners is expected to grow as well.
Market Trends:
Growth in Automation and Robotics
A prominent trend in the U.S. industrial fasteners market is the increasing use of automation and robotics in manufacturing processes. As industries such as automotive, aerospace, and electronics seek greater efficiency and precision, manufacturers are adopting robotic systems to streamline fastener assembly and installation. These systems not only reduce labor costs but also improve production speed and accuracy, allowing for the production of high-quality fasteners at a lower cost. With the automation of manufacturing lines, there is also a growing demand for fasteners designed to withstand higher levels of stress and environmental extremes, pushing for the development of more advanced fastening solutions.
Advancements in Fastener Materials
The U.S. industrial fasteners market is witnessing a shift toward more specialized and durable materials, driven by the need for fasteners that can perform under extreme conditions. There is a rising demand for fasteners made from high-strength alloys, corrosion-resistant materials, and lightweight composites, particularly in industries like aerospace and defense. For instance, titanium and stainless steel fasteners are becoming more prevalent due to their superior resistance to corrosion and ability to withstand harsh environmental conditions. These advancements are enabling manufacturers to create fasteners that can meet the demands of increasingly complex and high-performance applications.
Integration of 3D Printing in Fastener Production
Another notable trend in the U.S. industrial fasteners market is the integration of 3D printing technologies into fastener production. As industries seek to reduce lead times and costs associated with traditional manufacturing methods, 3D printing is offering significant advantages. Manufacturers can now create customized fasteners with intricate designs and material properties that were previously challenging or costly to achieve with traditional methods. For instance, companies such as Boeing are exploring 3D printing for lightweight, customized fasteners that reduce overall aircraft weight and improve fuel efficiency. This trend is particularly prevalent in the aerospace and automotive sectors, where the need for lightweight, customized parts is paramount. The growing adoption of 3D printing is expected to reduce waste, lower inventory costs, and enhance the flexibility of fastener production.
Increased Focus on Sustainability
Sustainability is becoming an essential trend in the U.S. industrial fasteners market as industries and consumers increasingly demand environmentally friendly solutions. Manufacturers are responding by producing fasteners made from recyclable materials or those that contribute to overall sustainability in construction and manufacturing. For example, Kuraray Fastening Co., Ltd. has launched a recycled type of FREE MAGIC™ mixed hook-and-loop fastener, which is RCS-certified and manufactured using a process that generates about 30% less CO₂ emissions compared to conventional methods. This trend is particularly strong in the construction sector, where green building practices are becoming the norm. Fasteners that are not only durable but also eco-friendly are in high demand as companies strive to meet sustainability goals and adhere to stringent environmental regulations. As green building certifications, such as LEED, become more widespread, the need for sustainable fasteners will continue to grow.
Market Challenges Analysis:
Fluctuating Raw Material Prices
One of the key restraints in the U.S. industrial fasteners market is the volatility of raw material prices. The cost of essential materials, such as steel, aluminum, and titanium, can fluctuate significantly due to global supply chain disruptions, trade tariffs, and changes in demand from other industries. For example, in 2023, the price of titanium sponge metal in the United States reached $12 per kilogram, marking a 12% increase from 2018. These price fluctuations pose a challenge for manufacturers, as they can lead to unpredictable production costs and impact profit margins. Additionally, the increasing cost of energy and transportation further exacerbates the issue, making it difficult for fastener manufacturers to maintain stable pricing for their products.
Stringent Regulatory Compliance
Another challenge faced by the U.S. industrial fasteners market is the increasing complexity of regulatory compliance. The fastener industry is subject to a range of quality standards, safety regulations, and environmental guidelines. These regulations vary across industries, such as aerospace, automotive, and construction, and must be adhered to by manufacturers. Compliance with these stringent regulations often requires significant investments in research, testing, and certification processes, which can be both time-consuming and costly. Failure to meet these requirements can lead to legal penalties, product recalls, or damage to a company’s reputation.
Intense Market Competition
The U.S. industrial fasteners market is highly competitive, with numerous established players and new entrants vying for market share. This intense competition puts pressure on companies to continuously innovate while keeping costs under control. Smaller manufacturers, in particular, may struggle to invest in new technologies or maintain high product quality at competitive prices. As a result, profit margins can become squeezed, and companies may find it challenging to differentiate their offerings in a crowded market. Additionally, the growing presence of low-cost foreign manufacturers further intensifies competition, making it difficult for domestic manufacturers to compete on price alone.
Supply Chain Vulnerabilities
The U.S. industrial fasteners market is also constrained by supply chain vulnerabilities. Disruptions caused by natural disasters, geopolitical tensions, or global health crises can severely impact the availability and cost of raw materials and finished products. Such supply chain uncertainties not only increase lead times but also affect inventory management, ultimately impacting the delivery schedules for customers. As manufacturers depend on both domestic and international suppliers, maintaining a resilient and diversified supply chain remains a challenge in an unpredictable global landscape
Market Opportunities:
The U.S. industrial fasteners market presents significant opportunities in the expansion of infrastructure projects. With the federal government’s increased focus on upgrading transportation systems, including highways, bridges, and railroads, the demand for industrial fasteners is poised for growth. These projects require a wide range of fasteners that ensure structural integrity and durability. As urbanization accelerates and the need for new residential and commercial buildings rises, there is a growing requirement for high-quality fastening solutions in construction. This offers manufacturers a promising opportunity to supply fasteners for large-scale infrastructure projects, particularly with the trend toward green construction and sustainable building practices that demand innovative fastening solutions.
Another key opportunity lies in the adoption of advanced manufacturing technologies, such as automation, robotics, and 3D printing, which are revolutionizing the production of industrial fasteners. These technologies enable manufacturers to improve production efficiency, reduce costs, and offer customized solutions tailored to specific applications. The rise of Industry 4.0 and smart manufacturing also opens the door for precision-engineered fasteners that meet the evolving needs of industries like aerospace, automotive, and electronics. As these sectors continue to innovate and demand higher performance fasteners, there is a substantial opportunity for manufacturers to diversify their product offerings and tap into new markets by adopting these advanced technologies, thereby staying competitive in an increasingly technology-driven marketplace.
Market Segmentation Analysis:
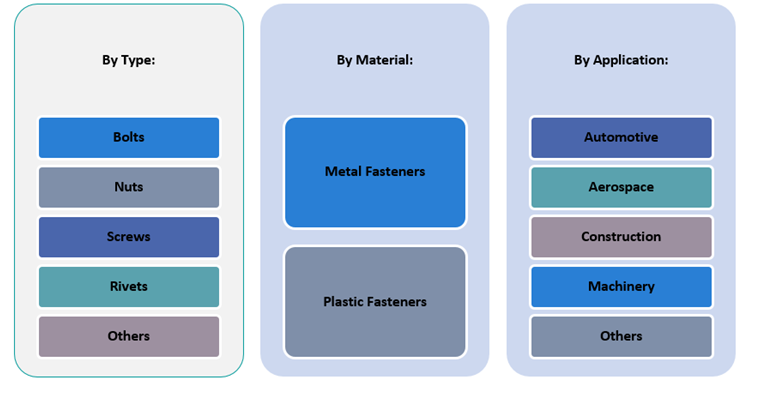
The U.S. Industrial Fasteners Market is segmented into three primary categories: type, application, and material, each of which plays a crucial role in the market's growth.
By Type Segment:
The market is predominantly driven by bolts, nuts, and screws, which are essential in fastening components across various industries. Bolts are widely used for joining heavy components in sectors like automotive and construction. Nuts complement bolts by securing them tightly, ensuring a firm connection. Screws, offering a versatile solution, are favored for applications requiring precise torque. Rivets, though less common, are critical in industries like aerospace for their permanent fastening capabilities. The others segment includes a variety of fasteners like washers and pins, which have specialized uses.
By Application Segment:
In terms of applications, the automotive sector is the largest consumer of industrial fasteners, driven by the need for high-quality, durable fasteners in vehicle manufacturing. The aerospace industry follows, where fasteners are crucial for ensuring safety and precision in aircraft construction. Construction is another significant sector, requiring fasteners for structural integrity in buildings, roads, and bridges. Machinery manufacturing demands fasteners for assembling heavy equipment and industrial machinery. The others segment includes industries like electronics and energy, where specialized fasteners are used.
By Material Segment:
The material segment is led by metal fasteners, including steel, titanium, and aluminum, known for their strength and durability. Plastic fasteners are gaining traction, particularly in industries where lightweight and corrosion resistance are critical, such as electronics and automotive applications.
Segmentation:
By Type Segment:
- Bolts
- Nuts
- Screws
- Rivets
- Others
By Application Segment:
- Automotive
- Aerospace
- Construction
- Machinery
- Others
By Material Segment:
- Metal Fasteners
- Plastic Fasteners
Regional Analysis:
The U.S. industrial fasteners market exhibits notable regional variations driven by the concentration of manufacturing activities, infrastructure development, and industrial demand. Each region plays a unique role in shaping the market dynamics, with distinct growth drivers, demands, and challenges.
Midwest Region
The Midwest region remains the dominant player in the U.S. industrial fasteners market, accounting for a significant market share of approximately 35%. This region is historically known as the industrial heartland of the country, with a high concentration of automotive, aerospace, and heavy machinery manufacturing. States such as Michigan, Ohio, and Illinois continue to lead in fastener consumption due to their established manufacturing base and robust infrastructure. The ongoing recovery of domestic manufacturing, coupled with growing demand from the automotive sector, has bolstered the demand for fasteners in this region. Furthermore, the aerospace industry in the Midwest, with major players such as Boeing and Raytheon, continues to require high-performance, precision-engineered fasteners to support the production of aircraft and components.
Southeast Region
The Southeast region is emerging as the fastest-growing market for industrial fasteners in the U.S., with a projected market share of 25%. Key states such as Alabama, Georgia, and Tennessee have become hotspots for automotive manufacturing, with major production facilities from companies like Mercedes-Benz, Honda, and Nissan. These automotive hubs have driven significant demand for fasteners, especially those used in vehicle assembly. Additionally, the Southeast is benefiting from favorable business climates, lower labor costs, and ongoing investments in infrastructure, further contributing to its market growth. This trend is expected to continue, with new manufacturing plants and industrial projects fueling the demand for fasteners.
West Coast Region
The West Coast region holds a market share of approximately 20% in the U.S. industrial fasteners market. California, as the largest state in the region, is a significant contributor to this share, driven by the state's diverse industrial landscape, which includes electronics, technology, and renewable energy. The West Coast's aerospace and defense sectors also require a wide array of specialized fasteners. In addition, the growing demand for fasteners in the renewable energy industry, particularly for wind and solar power installations, is further driving market growth in this region. However, challenges such as high labor costs and regulatory hurdles are factors that companies must navigate in the West Coast market.
Northeast Region
The Northeast region accounts for about 15% of the U.S. industrial fasteners market. This region’s key industry includes manufacturing, construction, and defense. States like New York, Pennsylvania, and Massachusetts are home to a diverse range of industries, with significant demand for fasteners used in infrastructure projects, industrial machinery, and defense manufacturing. While the Northeast sees steady demand for industrial fasteners, the region's slower growth rate compared to the Southeast and Midwest can be attributed to its more mature manufacturing base and higher operational costs.
Southwest Region
The Southwest region, contributing roughly 5% to the total market share, is growing steadily, particularly in Texas. The state's expanding oil and gas sector, as well as the increasing number of construction and energy projects, is driving the demand for industrial fasteners. However, the Southwest market remains smaller compared to other regions due to a lower concentration of manufacturing facilities and industries requiring large volumes of fasteners.
Key Player Analysis:
- Arconic Inc.
- Illinois Tool Works Inc.
- STANLEY Engineered Fastening
- Hilti Corporation
- Acument Global Technologies
- Fastenal Company
- Nucor Corporation
- PennEngineering
- TriMas Corporation
- Parker Fasteners
Competitive Analysis:
The U.S. industrial fasteners market is highly competitive, with a blend of well-established players and emerging companies striving for market share. Major global fastener manufacturers, such as Stanley Black & Decker, Illinois Tool Works, and Fastenal, dominate the market through their extensive product portfolios, broad distribution networks, and robust supply chains. These companies leverage their economies of scale to offer cost-effective solutions across various industries, including automotive, aerospace, and construction. In addition to large multinational corporations, regional players are also gaining traction by focusing on specific industries or offering customized fasteners tailored to particular applications. The competition is driven by factors such as product quality, technological advancements in manufacturing, and the ability to meet stringent regulatory standards. Companies are increasingly investing in innovation, particularly in smart manufacturing and automation, to stay competitive. Moreover, the growing demand for sustainable fasteners has prompted manufacturers to adopt eco-friendly solutions, further intensifying market competition.
Recent Developments:
- On February 25, 2025, Miller Electric Mfg. LLC, a wholly-owned subsidiary of Illinois Tool Works (ITW), announced a strategic partnership with Novarc Technologies. This collaboration focuses on developing AI-powered welding solutions under the Miller® Copilot™ line, aiming to enhance productivity, address labor shortages, and improve precision in industries such as shipbuilding and heavy equipment manufacturing.
- In January 2023, Hilti North America announced the addition of more than 30 new cordless tools to its Nuron battery-powered platform, expanding its portfolio to over 100 tools. This expansion, showcased at the World of Concrete event, includes advanced tools such as a diamond core rig, rotating lasers, and cut-off saws, reinforcing Hilti’s leadership in cordless jobsite solutions
Market Concentration & Characteristics:
The U.S. industrial fasteners market is characterized by a moderate to high concentration, with a few large players commanding a significant share, while smaller regional manufacturers cater to niche segments. Major companies such as Stanley Black & Decker, Fastenal, and Illinois Tool Works dominate the market through their extensive product offerings and established customer bases. These players benefit from economies of scale, advanced manufacturing capabilities, and a global reach, allowing them to offer competitive pricing and high-quality fasteners across various industries. Despite the dominance of these large corporations, the market also features numerous smaller players that focus on specialized fasteners or cater to specific industries, such as aerospace or energy. This segmentation allows for diversity in product offerings and fosters competition based on factors such as customization, innovation, and the ability to meet the unique needs of end-users. Innovation in materials, sustainability, and advanced manufacturing technologies also plays a key role in shaping market dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Material. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. industrial fasteners market will continue to benefit from the strong growth in infrastructure development, including transportation and construction projects.
- Increasing adoption of automation and robotics in manufacturing will drive demand for precision-engineered fasteners.
- The automotive industry’s shift toward electric vehicles will create new opportunities for fasteners designed for lightweight and high-performance applications.
- Aerospace advancements, including space exploration, will boost the need for high-quality, durable fasteners capable of withstanding extreme conditions.
- The growing trend of sustainability and green construction will drive demand for eco-friendly and recyclable fasteners.
- Technological advancements, such as 3D printing, will enable customization and reduce lead times in fastener production.
- The integration of Industry 4.0 will enhance production efficiency and product innovation within the fasteners sector.
- Rising investments in renewable energy will spur demand for specialized fasteners used in wind and solar energy installations.
- Regional market growth in the Southeast and West will continue as new manufacturing facilities and infrastructure projects emerge.
- Competitive pressures will intensify, pushing companies to innovate and develop fasteners that meet increasingly complex and demanding industry needs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Resurgence of Domestic Manufacturing
The revitalization of U.S. manufacturing, especially in the automotive and aerospace sectors, is increasing demand for high-quality, durable fasteners as companies onshore production and expand capacity to address supply chain challenges.
Infrastructure Development and Urbanization
Major investments in transportation, bridges, and commercial construction, along with ongoing urbanization, are driving substantial demand for industrial fasteners used in both new projects and renovations.
Technological Advancements in Manufacturing
The adoption of automation, robotics, and smart manufacturing is boosting production efficiency and enabling the creation of precision-engineered fasteners that meet the stringent requirements of advanced industries.
Sustainability and Green Construction Practices
Growing emphasis on eco-friendly building and manufacturing practices is fostering demand for recyclable and sustainable fasteners, aligning with regulatory requirements and consumer preferences for green solutions.
Expansion of Advanced Materials and Customization
The development and use of advanced materials such as corrosion-resistant alloys and composites, along with the integration of 3D printing, are enabling the production of specialized fasteners for high-performance and customized applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Industrial Fasteners Market?
What factors are driving the growth of the U.S. Industrial Fasteners Market?
How are technological advancements affecting the fasteners market?
What are some challenges faced by the U.S. Industrial Fasteners Market?
Who are the key players in the US Industrial Fasteners Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Bolts
- 1.2.2 Nuts
- 1.2.3 Screws
- 1.2.4 Rivets
- 1.2.5 Others
- 1.3 By Material
- 1.3.1 Metal Fasteners
- 1.3.2 Plastic Fasteners
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Aerospace
- 1.4.3 Construction
- 1.4.4 Machinery
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 28,843.26 million → 2032: USD 46,758.28 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Industrial Fasteners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Industrial Fasteners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Industrial Fasteners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Industrial Fasteners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Industrial Fasteners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Industrial Fasteners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Industrial Fasteners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Industrial Fasteners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 28,843.26 million → 2032: USD 46,758.28 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Industrial Fasteners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bolts
- 12.3.7.2 Nuts
- 12.3.7.3 Screws
- 12.3.7.4 Rivets
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metal Fasteners
- 12.4.7.2 Plastic Fasteners
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Aerospace
- 12.5.7.3 Construction
- 12.5.7.4 Machinery
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Industrial Fasteners End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Industrial Fasteners Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Industrial Fasteners Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Industrial Fasteners Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arconic Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Illinois Tool Works Inc.
- 18.4 STANLEY Engineered Fastening
- 18.5 Hilti Corporation
- 18.6 Acument Global Technologies
- 18.7 Fastenal Company
- 18.8 Nucor Corporation
- 18.9 PennEngineering
- 18.10 TriMas Corporation
- 18.11 Parker Fasteners
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

