
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vacuum Reflow Soldering Ovens Market Size 2024 | USD 250 Million |
| Vacuum Reflow Soldering Ovens Market, CAGR | 5.1% |
| Vacuum Reflow Soldering Ovens Market Size 2032 | USD 372.1 Million |
Market Overview:
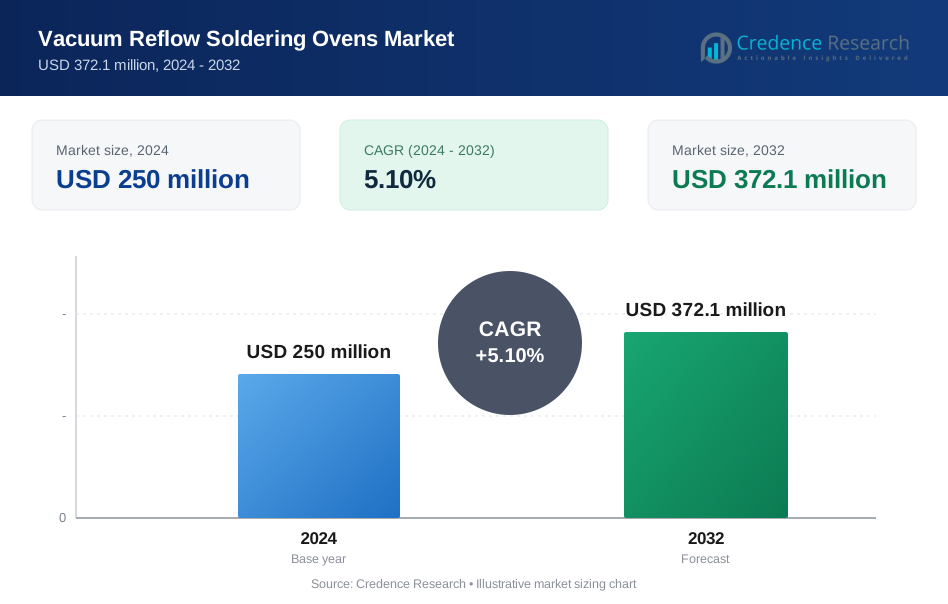
The Vacuum Reflow Soldering Ovens Market is projected to grow from USD 250 million in 2024 to an estimated USD 372.1 million by 2032, with a compound annual growth rate (CAGR) of 5.1% from 2024 to 2032.
Key factors propelling the market include the escalating demand for high-performance electronic devices across sectors such as automotive, telecommunications, and consumer electronics. The rise of electric vehicles (EVs) and advanced driver-assistance systems (ADAS) has amplified the need for reliable and compact electronic components, thereby driving the demand for efficient soldering technologies. Additionally, the trend towards miniaturization and the growing complexity of electronic assemblies necessitate precise and void-free soldering processes, which vacuum reflow ovens are adept at providing. Technological advancements, such as the integration of automation and smart technologies, further enhance the appeal of vacuum reflow soldering ovens by offering improved process control and efficiency. These innovations also contribute to reducing manufacturing defects and increasing overall production yield, which is critical for meeting stringent quality standards.
The Asia-Pacific region dominates the vacuum reflow soldering ovens market, holding a significant share due to the concentration of electronics manufacturing in countries like China, Japan, South Korea, and India. This region's robust infrastructure and established supply chains contribute to its leading position. North America and Europe also represent substantial markets, driven by the presence of major electronics manufacturers and increasing investments in advanced manufacturing technologies. The demand in these regions is further bolstered by the growing emphasis on quality and precision in electronic component manufacturing. Furthermore, government initiatives promoting advanced manufacturing and smart factory adoption accelerate the uptake of vacuum reflow soldering ovens in these developed markets.
Market Insights:
- The Vacuum Reflow Soldering Ovens Market is expected to grow from USD 250 million in 2024 to USD 372.1 million by 2032, with a CAGR of 5.1%.
- Demand for high-performance electronics in automotive, telecommunications, and consumer sectors drives market growth.
- The rise of electric vehicles and advanced driver-assistance systems increases the need for reliable and compact soldering solutions.
- Miniaturization and complexity of electronic assemblies require precise, void-free soldering that vacuum reflow ovens provide.
- Technological advances in automation and smart systems improve process control, reduce defects, and enhance production yield.
- Asia-Pacific dominates the market due to concentrated electronics manufacturing in China, Japan, South Korea, and India.
- North America and Europe maintain significant shares, supported by investments in advanced manufacturing and quality standards.
Market Drivers:
Technological Advancements Enhancing Precision and Efficiency
The Vacuum Reflow Soldering Ovens Market grows significantly due to ongoing technological advancements in soldering processes. It enables manufacturers to achieve higher precision and uniformity in solder joints, which is crucial for complex and miniaturized electronic assemblies. Integration of smart sensors and automation within these ovens allows real-time monitoring and precise control of temperature and vacuum levels, reducing defects and improving yield rates. Innovations in heating elements and vacuum systems enhance energy efficiency and throughput, making production faster and more cost-effective. These improvements support the rising demand for reliable soldering in advanced electronics such as smartphones, wearables, and automotive components. Manufacturers increasingly adopt vacuum reflow ovens to maintain a competitive advantage by improving product quality and operational efficiency. This technological progress directly boosts adoption across various electronics manufacturing sectors.
- For example, Rehm Thermal Systems’ VisionXP+ Vac integrates a vacuum module directly into the convection soldering process, enabling manufacturers to achieve void rates of less than 2% by applying a vacuum down to 2 mbar immediately after soldering.
Rising Demand for Miniaturized and Complex Electronic Assemblies
The market expands due to growing demand for smaller, lightweight, and more complex electronic devices requiring precise and void-free soldering solutions. Miniaturization increases the complexity of printed circuit boards (PCBs), necessitating soldering techniques that prevent defects like voids and insufficient wetting. It ensures electrical performance and mechanical stability, essential in consumer electronics, telecommunications, and automotive industries. The Vacuum Reflow Soldering Ovens Market benefits from trends such as Internet of Things (IoT) devices and 5G technology, which require compact and reliable assemblies. Vacuum reflow technology effectively removes trapped gases during soldering, producing superior joints that meet stringent quality standards. Increasing complexity in electric vehicles and aerospace sectors further accelerates vacuum reflow oven adoption. Market players develop ovens tailored for advanced applications demanding precision and high reliability.
Expansion of Automotive and Consumer Electronics Sectors
Growth in automotive and consumer electronics industries fuels demand for vacuum reflow soldering ovens. The automotive sector incorporates electronic components extensively in electric vehicles (EVs) and advanced driver-assistance systems (ADAS), requiring highly reliable solder joints to ensure safety and durability under harsh conditions. Rising EV production worldwide pushes manufacturers to adopt vacuum reflow ovens to comply with quality and regulatory standards. Rapid innovation and frequent product upgrades in consumer electronics such as smartphones, laptops, and wearables also drive market growth. The Vacuum Reflow Soldering Ovens Market benefits from these sectors’ need for efficient soldering processes supporting high volume and stringent quality demands. Suppliers provide versatile ovens that accommodate diverse assembly types to meet industry-specific requirements. Increased electronics content in vehicles and consumer devices guarantees sustained demand for vacuum reflow ovens.
Focus on Quality Control and Regulatory Compliance
Stringent quality control and regulatory compliance requirements act as strong market drivers. Automotive, aerospace, and medical device industries enforce standards that require soldering processes minimizing failures and enhancing product durability. Vacuum reflow soldering technology offers precise control over process parameters, reducing voids and ensuring consistent joint integrity. It helps manufacturers meet international quality certifications while decreasing costly recalls and warranty claims. Growing awareness of soldering defects’ impact on device performance motivates companies to invest in advanced ovens with accurate process control. This investment improves customer satisfaction and brand reputation, providing a competitive edge. Increasing global regulations and industry standards further accelerate the adoption of vacuum reflow soldering ovens in critical manufacturing sectors.
- For instance, the VisionXP+ Vac system’s clean vacuum chamber, equipped with pyrolysis units and separate filtering, minimizes downtime and maintenance, further supporting consistent product quality and regulatory adherence.
Market Trends:
Increasing Adoption of Automation and Industry 4.0 Technologies
The Vacuum Reflow Soldering Ovens Market reflects a strong shift toward automation and integration of Industry 4.0 technologies. Manufacturers implement smart sensors, IoT connectivity, and real-time data analytics to enhance process control and traceability. These technologies allow operators to monitor soldering parameters remotely and adjust settings dynamically, improving consistency and reducing waste. Automated loading and unloading systems increase throughput and reduce labor costs, supporting large-scale production demands. Digital twin technology simulates soldering processes for optimization before actual production, minimizing errors. This trend aligns with manufacturers’ goals to improve operational efficiency and product quality, positioning vacuum reflow ovens as essential in smart factories.
- For example, Heller Industries has developed SMT soldering equipment with predictive analytics, increased connectivity, and reduced maintenance costs, specifically designed for Industry 4.0 environments. Their systems offer communication protocols such as SEC/GEM and IPC CFX, enabling seamless integration with smart factory floors and allowing for real-time data exchange and remote monitoring of soldering parameters.
Rising Demand for Energy-Efficient and Environmentally Friendly Vacuum Reflow Ovens
Energy efficiency and environmental considerations increasingly influence product development and purchasing decisions in the Vacuum Reflow Soldering Ovens Market. Manufacturers reduce power consumption through innovations in heating elements, insulation, and vacuum systems. Lower energy use decreases operational costs and supports sustainability goals amid tightening regulatory pressure on emissions and resource consumption. Some companies use eco-friendly materials and design ovens for easier recycling or disposal. The market responds to demand for equipment that meets both performance and environmental standards. Energy-efficient vacuum reflow ovens attract sectors with strong corporate social responsibility policies. This trend enhances competitiveness by aligning with global sustainability initiatives and lowering electronic manufacturing’s carbon footprint.
- For instance, Ersa’s HOTFLOW series, including the EXOS 10/26, is engineered for energy-efficient operation and reduced environmental impact, aligning with customers’ sustainability goals and regulatory requirements.
Expansion of Customized and Application-Specific Vacuum Reflow Solutions
The Vacuum Reflow Soldering Ovens Market sees growing demand for customized and application-specific solutions tailored to unique manufacturing needs. Industries such as automotive, aerospace, medical devices, and consumer electronics require ovens designed for varied soldering profiles, board sizes, and component types. Vendors offer modular and flexible ovens that adapt or upgrade based on production needs. Customization includes software controls and reporting features integrating with manufacturing execution systems (MES). This trend supports agility, enabling manufacturers to respond swiftly to product changes or market shifts. Tailored vacuum reflow ovens improve yield and reduce downtime, strengthening value propositions. The ability to deliver bespoke solutions drives competitive differentiation.
Growing Importance of Void Reduction and Quality Assurance in Soldering Processes
Reducing voids in solder joints and ensuring superior quality remain critical trends shaping the Vacuum Reflow Soldering Ovens Market. Voids compromise electrical conductivity and mechanical strength, leading to premature failures. Vacuum reflow ovens minimize trapped gases during soldering, producing consistent, high-quality joints. Manufacturers emphasize quality assurance through inline inspection systems and statistical process control (SPC). Integrating vacuum soldering with advanced inspection tools identifies defects early, reducing rework and warranty costs. Market demand favors ovens offering reproducible results that comply with strict industry standards. This focus on quality supports product reliability in critical applications like automotive electronics, aerospace, and medical devices. It drives ongoing innovation and investment in vacuum reflow soldering technology.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs Restrict Market Penetration
The Vacuum Reflow Soldering Ovens Market faces challenges due to the substantial upfront capital required for purchasing advanced vacuum reflow equipment. High costs can deter small and medium-sized manufacturers from adopting this technology despite its benefits in quality and precision. Maintenance and calibration of these ovens demand specialized expertise and periodic investments, adding to operational expenses. The complexity of vacuum systems and control electronics necessitates regular servicing to maintain optimal performance and prevent downtime. These financial barriers slow widespread market penetration, especially in cost-sensitive regions or industries. Manufacturers must balance initial expenditures against long-term gains in product reliability and yield. This challenge compels vendors to explore cost-effective designs and flexible financing options to broaden their customer base.
- For instance, users of the SMT Wertheim Reflow Oven have noted that its high initial cost can be a significant barrier, particularly for small and medium-sized manufacturers, despite its exceptional performance.
Technical Complexity and Skill Shortages Limit Efficient Utilization
The Vacuum Reflow Soldering Ovens Market encounters obstacles due to the technical complexity involved in operating and optimizing vacuum reflow processes. Skilled operators and process engineers with specific knowledge of vacuum soldering are critical to achieve consistent quality and maximize equipment capabilities. Lack of trained personnel can lead to suboptimal process control, increasing defect rates and reducing production efficiency. Integration of vacuum reflow ovens into existing production lines requires careful planning and adjustment to avoid disruptions. Rapid technological advancements further increase the learning curve for users. The shortage of skilled labor combined with evolving process requirements creates operational challenges for manufacturers adopting vacuum reflow technology. It drives a need for comprehensive training programs and user-friendly equipment interfaces to improve adoption and effective utilization.
Market Opportunities:
The Vacuum Reflow Soldering Ovens Market benefits from rising demand for advanced electronic devices that require precise and reliable soldering solutions. Increasing adoption of miniaturized assemblies in consumer electronics, automotive systems, and medical devices drives the need for void-free solder joints. It offers manufacturers opportunities to develop ovens tailored for complex, high-density circuit boards and emerging technologies such as 5G and IoT. Expanding applications in electric vehicles and aerospace further extend market potential. Companies can leverage this demand by innovating flexible and adaptable vacuum reflow solutions that meet evolving industry requirements. This trend opens avenues for product differentiation and geographic expansion into high-growth sectors.
Advancements in automation, real-time monitoring, and Industry 4.0 integration present significant growth opportunities within the Vacuum Reflow Soldering Ovens Market. It enables manufacturers to improve process control, reduce defects, and increase production efficiency. Vendors can capitalize on demand for connected ovens with predictive maintenance capabilities and seamless integration into digital factory ecosystems. Rising focus on energy-efficient and environmentally friendly equipment further broadens market appeal. Developing user-friendly interfaces and modular designs allows penetration into new customer segments, including small and medium enterprises. These technological opportunities position the market for sustained growth driven by innovation and digital transformation.
Market Segmentation Analysis:
The Vacuum Reflow Soldering Ovens Market segments reflect diverse technologies, applications, configurations, features, and end-users, each driving distinct growth dynamics.
By technology, convection vacuum reflow ovens dominate due to their efficient heat transfer and ability to handle complex assemblies, while infrared (IR) vacuum ovens offer precise temperature control for sensitive components. Vapor phase vacuum reflow ovens provide uniform soldering profiles, preferred in high-reliability sectors, and laser vacuum reflow ovens cater to advanced applications requiring localized heating and minimal thermal impact.
By application, automotive electronics lead market demand driven by the rise of electric vehicles and advanced driver-assistance systems requiring reliable solder joints. Consumer electronics and telecommunications sectors follow closely, fueled by miniaturization and growing connectivity needs. Aerospace, defense, medical devices, and industrial electronics also contribute, prioritizing quality and durability.
By configuration, inline vacuum reflow ovens dominate high-volume manufacturing environments due to their speed and integration capabilities. Batch mode ovens serve smaller production runs or prototyping, while modular ovens provide flexibility for evolving manufacturing requirements.
By Features such as programmable profiles, automated cleaning systems, energy-efficient designs, and real-time monitoring systems enhance process control and reduce defects.
By End-users include original equipment manufacturers (OEMs), contract manufacturers (CMs), research and development laboratories, and semiconductor manufacturers. These groups demand advanced soldering solutions that ensure precision, repeatability, and compliance with industry standards. The Vacuum Reflow Soldering Ovens Market benefits from this segmentation, driving tailored innovations and expanding adoption across multiple industries.
Segmentation:
By Technology
- Infrared (IR) Vacuum Reflow Ovens
- Convection Vacuum Reflow Ovens
- Vapor Phase Vacuum Reflow Ovens
- Laser Vacuum Reflow Ovens
By Application
- Automotive Electronics
- Consumer Electronics
- Telecommunications
- Aerospace & Defense
- Medical Devices
- Industrial Electronics
By Configuration
- Batch Mode Vacuum Reflow Ovens
- Inline Vacuum Reflow Ovens
- Modular Vacuum Reflow Ovens
By Features
- Programmable Profiles
- Automated Cleaning Systems
- Energy-Efficient Designs
- Real-Time Monitoring Systems
By End-User
- Original Equipment Manufacturers (OEMs)
- Contract Manufacturers (CMs)
- Research and Development (R&D) Laboratories
- Semiconductor Manufacturers
By Region
- North America
- Europe
- APAC
- Middle East Asia & Rest of World
Regional Analysis:
The Asia-Pacific region leads the Vacuum Reflow Soldering Ovens Market, commanding the largest share of approximately 45% in 2024. This dominance stems from the region’s well-established electronics manufacturing hubs in countries such as China, Japan, South Korea, and Taiwan. It benefits from robust supply chains, skilled labor availability, and high investments in semiconductor and consumer electronics production. Rapid growth in sectors like automotive electronics, telecommunications, and consumer devices fuels demand for advanced soldering technologies. Governments in the region actively support technological upgrades and smart manufacturing initiatives, further driving market expansion. The rising adoption of electric vehicles and 5G infrastructure also contributes to sustained growth prospects in this region.
North America holds a significant share of around 30% in the Vacuum Reflow Soldering Ovens Market, driven by the presence of major electronics manufacturers and advanced research facilities. It stands out for early adoption of Industry 4.0 technologies and automation, which improve manufacturing efficiency and quality control. The United States and Canada see growing investments in aerospace, medical devices, and automotive sectors that require precise soldering solutions. The market in this region benefits from stringent quality standards and regulatory compliance, motivating companies to invest in high-performance vacuum reflow ovens. Increased focus on sustainability and energy efficiency also supports demand for next-generation equipment.
Europe accounts for approximately 20% of the Vacuum Reflow Soldering Ovens Market share, characterized by a strong presence of automotive and industrial electronics manufacturers. Countries such as Germany, France, and the UK lead in adopting vacuum reflow technology for high-reliability applications. It benefits from well-established industrial infrastructure and ongoing digital transformation efforts. European manufacturers emphasize quality assurance and process optimization to maintain competitiveness in global markets. Rising demand for electric and autonomous vehicles further stimulates the adoption of advanced soldering technologies. The region’s commitment to environmental regulations promotes investment in energy-efficient vacuum reflow ovens. This combination of factors ensures steady market growth in Europe.
Key Player Analysis:
- 3S Silicon Tech Inc.
- ATV Technologie GmbH
- BTU International
- EIGHTECH TECTRON
- Heller Industries
- HIRATA Corporation
- Kurtz Ersa
- Rehm Thermal Systems
- Senju Metal Industry Co., Ltd
- Shenzhen JT Automation
- SMT Wertheim
Competitive Analysis:
The Vacuum Reflow Soldering Ovens Market features intense competition among established and emerging players striving to innovate and expand their market share. Leading companies focus on developing technologically advanced ovens that offer improved precision, energy efficiency, and seamless integration with Industry 4.0 systems. It drives continuous product enhancements such as enhanced temperature control, automation, and real-time monitoring capabilities. Strategic partnerships and collaborations with electronics manufacturers help vendors tailor solutions to specific industry needs. Companies also invest in expanding their global footprint, particularly in high-growth regions like Asia-Pacific and North America. Competitive pricing and flexible financing options play crucial roles in attracting a diverse customer base. Customer service and after-sales support remain key differentiators that influence purchasing decisions. Overall, the competitive landscape in the Vacuum Reflow Soldering Ovens Market pushes innovation and efficiency, benefiting end-users through improved product quality and manufacturing performance.
Recent Developments:
- In April 2025, 3S Silicon Tech Inc. highlighted its comprehensive system portfolio for power device assembly, which includes advanced vacuum reflow ovens and formic acid vacuum reflow ovens. The company positions itself as a total solution provider, integrating materials, process expertise, and equipment for the semiconductor industry. Their recent focus has been on configurable systems tailored to the precision and reliability demands of modern power semiconductor packaging, with ongoing innovations in silicon photonics and wafer-level packaging.
- In March 2025, Heller Industries announced a strategic global partnership with VST, an Israeli company specializing in thin film and vacuum deposition systems. This partnership will allow Heller to offer VST’s product line, including nanolayer sputtering and vacuum test solutions, through its global sales channels.
- On February 11, 2025, Rehm Thermal Systems announced further developments in convection soldering under vacuum with its VisionXP+ Vac system, which offers high process stability and reduced operating costs. The company showcased these advancements at Productronica China 2025, emphasizing the system’s ability to remove voids and gas inclusions during the soldering process, as well as its energy-efficient closed-loop system for vapour phase soldering.
- In October 2023, Heller also launched its High UPH Vacuum Oven, which features a multi-stage rail conveyor system to significantly boost production capacity, earning acclaim from customers worldwide
Market Concentration & Characteristics:
The Vacuum Reflow Soldering Ovens Market exhibits a moderately concentrated structure dominated by a few key players with strong technological capabilities and extensive distribution networks. It features leading manufacturers who invest heavily in research and development to maintain competitive advantages through innovation in automation, energy efficiency, and precision control. These companies benefit from established customer relationships in sectors like automotive, aerospace, and consumer electronics. The market also includes smaller, specialized firms offering niche solutions tailored to specific applications or regional demands. High capital requirements and technical complexity create entry barriers for new competitors, reinforcing the position of established players. It fosters steady advancements while maintaining a balance between innovation and reliability. The market’s characteristics reflect a focus on quality, customization, and compliance with evolving industry standards, ensuring ongoing demand from industries requiring stringent soldering performance.
Report Coverage:
The research report offers an in-depth analysis based on technologies, applications, configurations, features, and end-users. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of electric vehicles will drive demand for advanced vacuum reflow soldering ovens.
- Miniaturization in consumer electronics will require more precise and void-free soldering solutions.
- Integration of AI and machine learning will enhance process optimization and defect detection.
- Rising investments in 5G infrastructure will expand opportunities for vacuum reflow ovens in telecommunications.
- Growth in aerospace and medical device manufacturing will boost demand for high-reliability soldering equipment.
- Energy-efficient and eco-friendly oven designs will gain prominence due to stricter environmental regulations.
- Expansion of smart factories and Industry 4.0 adoption will accelerate the integration of connected vacuum reflow ovens.
- Customizable and modular ovens will address diverse application needs, improving market flexibility.
- Increasing emphasis on quality assurance and compliance will reinforce the importance of vacuum reflow technology.
- Emerging markets in Asia-Pacific and Latin America will present significant growth potential for manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Precision and Automation
Continuous improvements in automation, smart sensors, and process control enable vacuum reflow soldering ovens to deliver higher precision, reduce defects, and increase production yield, making them essential for advanced electronics manufacturing.
Growth of Automotive and Electric Vehicle Electronics
The rapid expansion of electric vehicles and advanced driver-assistance systems (ADAS) requires highly reliable and compact electronic assemblies, driving demand for vacuum reflow ovens that can produce void-free, durable solder joints.
Miniaturization and Complexity of Electronic Assemblies
As electronic devices become smaller and more complex, manufacturers require soldering solutions that ensure precise, void-free joints, which vacuum reflow ovens are specifically designed to provide.
Stringent Quality and Regulatory Standards
Industries such as automotive, aerospace, and medical devices enforce strict quality and compliance requirements, pushing manufacturers to adopt vacuum reflow ovens for their ability to minimize defects and ensure consistent, high-quality soldering.
Adoption of Industry 4.0 and Smart Factory Initiatives
The integration of Industry 4.0 technologies, including IoT connectivity and real-time monitoring, enhances process optimization and traceability, making vacuum reflow ovens a critical component in modern, connected manufacturing environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vacuum Reflow Soldering Ovens Market?
What factors are driving the growth of the Vacuum Reflow Soldering Ovens Market?
What are the key segments within the Vacuum Reflow Soldering Ovens Market?
What are some challenges faced by the Vacuum Reflow Soldering Ovens Market?
Who are the major players in the Vacuum Reflow Soldering Ovens Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Original Equipment Manufacturers (OEMs)
- 1.2.2 Contract Manufacturers (CMs)
- 1.2.3 Research and Development (R&D) Laboratories
- 1.2.4 Semiconductor Manufacturers
- 1.3 By Technology
- 1.3.1 Infrared (IR) Vacuum Reflow Ovens
- 1.3.2 Convection Vacuum Reflow Ovens
- 1.3.3 Vapor Phase Vacuum Reflow Ovens
- 1.3.4 Laser Vacuum Reflow Ovens
- 1.4 By Application
- 1.4.1 Automotive Electronics
- 1.4.2 Consumer Electronics
- 1.4.3 Telecommunications
- 1.4.4 Aerospace & Defense
- 1.4.5 Medical Devices
- 1.4.6 Industrial Electronics
- 1.5 By Configuration
- 1.5.1 Batch Mode Vacuum Reflow Ovens
- 1.5.2 Inline Vacuum Reflow Ovens
- 1.5.3 Modular Vacuum Reflow Ovens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 250 million → 2032: USD 372.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vacuum Reflow Soldering Ovens Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vacuum Reflow Soldering Ovens Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vacuum Reflow Soldering Ovens Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vacuum Reflow Soldering Ovens Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vacuum Reflow Soldering Ovens Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vacuum Reflow Soldering Ovens Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vacuum Reflow Soldering Ovens Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vacuum Reflow Soldering Ovens Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 250 million → 2032: USD 372.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vacuum Reflow Soldering Ovens Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Original Equipment Manufacturers (OEMs)
- 12.3.7.2 Contract Manufacturers (CMs)
- 12.3.7.3 Research and Development (R&D) Laboratories
- 12.3.7.4 Semiconductor Manufacturers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Infrared (IR) Vacuum Reflow Ovens
- 12.4.7.2 Convection Vacuum Reflow Ovens
- 12.4.7.3 Vapor Phase Vacuum Reflow Ovens
- 12.4.7.4 Laser Vacuum Reflow Ovens
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive Electronics
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Telecommunications
- 12.5.7.4 Aerospace & Defense
- 12.5.7.5 Medical Devices
- 12.5.7.6 Industrial Electronics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Configuration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Batch Mode Vacuum Reflow Ovens
- 12.6.7.2 Inline Vacuum Reflow Ovens
- 12.6.7.3 Modular Vacuum Reflow Ovens
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vacuum Reflow Soldering Ovens End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Vacuum Reflow Soldering Ovens Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Vacuum Reflow Soldering Ovens Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Vacuum Reflow Soldering Ovens Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Rehm Thermal Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kurtz Ersa
- 18.4 Heller Industries
- 18.5 3S Silicon Tech Inc.
- 18.6 ATV Technologie GmbH
- 18.7 BTU International
- 18.8 HIRATA Corporation
- 18.9 Senju Metal Industry Co., Ltd
- 18.10 Shenzhen JT Automation
- 18.11 SMT Wertheim
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

