
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
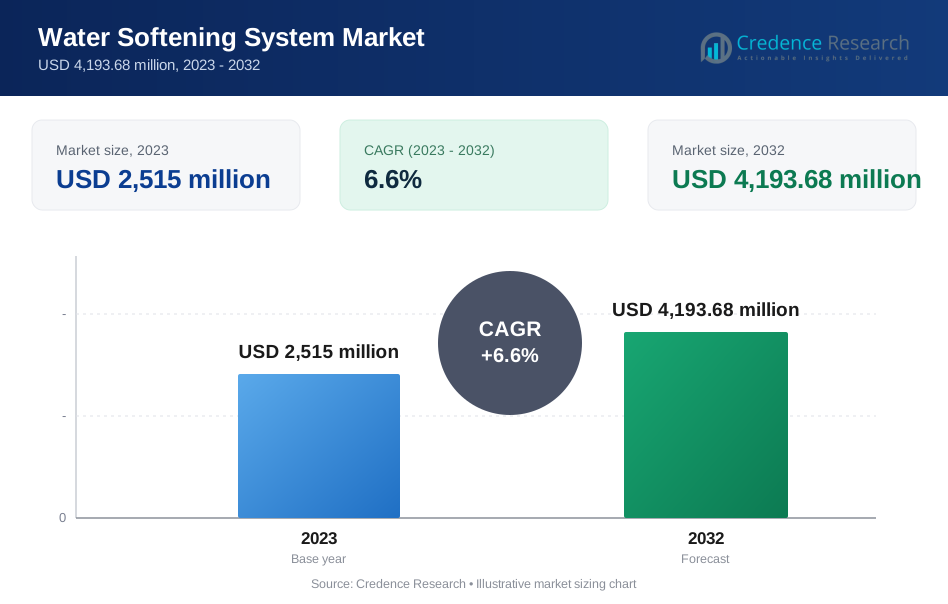
| Water Softening System Market Size 2023 | USD 2,515 Million |
| Water Softening System Market, CAGR | 6.6% |
| Water Softening System Market Size 2032 | USD 4,193.68 Million |
Market Overview
The Global Water Softening System Market is projected to grow from USD 2,515 million in 2023 to an estimated USD 4,193.68 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.6% from 2024 to 2032. This growth trajectory is primarily driven by the increasing demand for treated water in residential, commercial, and industrial sectors due to concerns over water hardness, which affects appliances, plumbing, and industrial processes.
The market's growth is propelled by factors such as heightened awareness about health risks associated with hard water consumption, regulatory policies mandating water treatment, and the rising need for efficient water management solutions across urban and rural areas. Trends such as the development of smart and connected water softening systems with digital controls and the shift toward eco-friendly and salt-free systems are further enhancing market dynamics. Increasing investments in infrastructure modernization and efforts to reduce scaling and corrosion in water-using equipment are also significant drivers.
Geographically, North America and Europe dominate the market due to strong consumer awareness and stringent regulatory mandates related to water treatment. Asia-Pacific is expected to witness the highest growth rate during the forecast period, driven by rapid industrialization, urbanization, and a growing emphasis on water quality in developing economies such as China and India. Key players in the market include A.O. Smith Corporation, Culligan International Company, BWT AG, 3M Company, EcoWater Systems LLC, and Pentair Residential Filtration LLC, who focus on innovative solutions and strategic expansions to capture market share.
Market Drivers
Increasing Awareness About the Adverse Effects of Hard Water
Consumers and industries worldwide are increasingly aware of the negative effects of hard water on health, household appliances, plumbing systems, and industrial processes. Hard water, characterized by high levels of calcium and magnesium ions, leads to limescale buildup, which damages pipes, reduces appliance efficiency, and increases energy consumption. For instance, a survey in Bengaluru, India revealed that 24% of the city's areas receive hard water, which directly prompted increased water-softening system installations in households and commercial sectors. Another concrete example is that nearly 3,400 million people in Asia are estimated to live in water-stressed areas by 2050, highlighting the critical need for water treatment solutions.This awareness drives demand for water softening systems as they provide an effective solution to reduce the hardness of water by removing these ions, ultimately enhancing the longevity and performance of equipment. The heightened awareness is further fueled by campaigns and educational initiatives from public health bodies, water treatment organizations, and government agencies, emphasizing the importance of addressing water hardness.
Stringent Government Regulations and Standards for Water Quality
Regulatory bodies around the globe are enforcing stringent standards and policies regarding water quality, primarily in developed regions like North America and Europe. Regulatory PrecisionFor instance, the U.S. Environmental Protection Agency (EPA) has required public water suppliers since 1974 to ensure their water is sufficiently free of certain chemicals, germs, and other pollutants. The EPA also mandates that states report on water quality every two years through the National Water Quality Inventory Report to Congress, demonstrating the rigorous regulatory oversight.Regulations often mandate the installation of water treatment systems, including water softeners, particularly in industries where water quality can impact production processes, product safety, or public health. In many countries, water softening is essential in commercial establishments such as hotels, hospitals, and food and beverage industries to ensure compliance with safety and performance standards. The focus on reducing scaling, ensuring potable water quality, and minimizing the environmental impact of untreated hard water discharge further propels the demand for water softening systems. Compliance-driven demand from residential sectors, driven by the promotion of water efficiency and quality standards, also plays a key role in market growth.
Growing Urbanization and Industrialization in Emerging Economies
Rapid urbanization and industrialization, especially in regions such as Asia-Pacific, Latin America, and the Middle East & Africa, have led to an increased demand for water softening systems. Urban Water ChallengesFor instance, developing nations like India and China are experiencing significant urban expansion. In India, rising industrial and agricultural activities have deteriorated surface and groundwater quality, creating an urgent need for water purification systems. Another concrete example is that government and non-government organizations in India are actively investing in water purification systems across schools, hospitals, corporate spaces, and community centers to address water contamination challenges.Urban expansion typically results in higher water consumption rates and requires infrastructure improvements to provide soft and treated water to households and commercial establishments. In emerging markets, industries such as power generation, manufacturing, oil & gas, and pharmaceuticals are also on the rise, demanding large-scale soft water solutions to protect machinery, optimize operational efficiency, and ensure product quality.Government programs promoting infrastructure development, housing projects, and modernization of water treatment facilities across developing economies also create strong growth opportunities for water softening systems.The integrated content now provides a more comprehensive view of the water softening market, supported by specific, data-driven examples that illustrate the key points of awareness, regulation, and urban development driving the industry's growth.
Technological Advancements and Product Innovation
Rapid advancements in water softening technologies have revolutionized the market, making systems more efficient, user-friendly, and environmentally sustainable. Innovations such as salt-free and dual-tank water softening systems, smart control features with remote monitoring, and integration with IoT platforms have significantly enhanced consumer appeal. Salt-free water softeners cater to health- and environment-conscious consumers by reducing salt consumption and minimizing environmental waste. Likewise, smart water softeners with real-time water usage data, leak detection, and predictive maintenance capabilities provide added convenience and cost savings for users. Companies continue to invest in research and development (R&D) to introduce novel, energy-efficient, and customized solutions tailored to diverse residential, commercial, and industrial needs, further expanding market adoption and accessibility.
Market Trends
Adoption of Smart and Connected Water Softening Systems
One of the most prominent trends in the global water softening system market is the integration of smart technology and connectivity features. Modern water softeners are now equipped with advanced monitoring and control capabilities, often facilitated through IoT and mobile applications. For instance, a single smart water softening system can reduce water waste by up to 25,000 gallons annually through optimized regeneration cycles. In a typical household, these smart systems can track water usage patterns and automatically adjust settings, with some models enabling users to monitor system performance through smartphone apps that provide real-time diagnostics within a 500-foot Bluetooth range. These smart water softening systems provide real-time data on water consumption, salt levels, and system performance, enhancing user convenience and enabling predictive maintenance. Moreover, advanced IoT-enabled water softeners can detect potential maintenance issues up to 72 hours before a critical system failure, allowing preemptive interventions. Consumers and businesses can monitor water softener operations remotely, receive alerts on potential malfunctions, and optimize the regeneration cycle, thus reducing operating costs and energy consumption. This trend caters particularly to tech-savvy consumers and commercial operators looking to increase operational efficiency and reduce environmental impact. As smart home ecosystems continue to grow, the adoption of intelligent water softeners will likely gain further traction.
Growing Demand for Eco-Friendly and Salt-Free Water Softeners
Another notable trend in the global water softening system market is the rising demand for eco-friendly and salt-free alternatives. Traditional water softening systems often rely on salt-based ion-exchange processes, which can lead to increased sodium discharge into water supplies. For instance, a salt-free water conditioning system can prevent up to 12 pounds of scale buildup per household annually. In commercial settings like hotels and restaurants, template-assisted crystallization (TAC) systems can reduce equipment maintenance costs by eliminating scale formation in pipes and appliances, with some studies showing a potential reduction of maintenance expenses by approximately 8,000 dollars over a five-year period. Environmental concerns and water scarcity issues have prompted manufacturers to develop salt-free solutions that rely on alternative methods, such as template-assisted crystallization (TAC) and electromagnetic conditioning. Additionally, electromagnetic conditioning technologies can treat water volumes up to 40 gallons per minute without introducing any chemical additives, making them particularly attractive for industrial and large-scale applications. These systems effectively reduce scaling without using sodium, making them an attractive choice for environmentally conscious consumers and areas with regulations on salt discharge. This trend is further reinforced by growing public awareness about sustainability and the impact of salt-based systems on soil, water, and human health. As a result, eco-friendly and salt-free solutions are experiencing increased popularity in both residential and commercial markets, driving manufacturers to continuously innovate and expand their product offerings to meet this evolving demand.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the primary challenges facing the global water softening system market is the high initial investment and ongoing maintenance costs associated with these systems. Compared to basic water treatment solutions, water softeners often involve significant upfront costs for installation, which can be a deterrent for cost-sensitive consumers, particularly in developing regions. Additionally, regular maintenance, including salt replacement, system servicing, and regeneration processes, can lead to ongoing expenses that may pose a burden for residential users and small businesses. The total cost of ownership, which encompasses both capital and operational costs, can limit the adoption of these systems, especially among low-income households or budget-conscious organizations. While manufacturers are working on cost-effective models and more efficient maintenance solutions, the price factor remains a barrier for broader market penetration.
Environmental Concerns and Regulatory Restrictions on Salt-Based Systems
Environmental and regulatory challenges pose another major restraint to the growth of the water softening system market, particularly for traditional salt-based systems. The ion-exchange process employed in these systems involves the discharge of salt brine, which can have negative impacts on water sources and soil. In response, several regions have implemented regulations and restrictions on the use and disposal of salt-based softeners to mitigate their environmental impact. For example, certain municipalities have banned or placed limits on salt discharge from water softening systems, forcing users to seek alternative or modified solutions. This challenge not only restricts market growth in regions with stringent environmental policies but also requires manufacturers to invest heavily in research and development to create eco-friendly and compliant alternatives. Addressing these environmental concerns remains a key priority for the industry, but compliance can increase production costs and limit product accessibility.
Market Segmentation Analysis
By Softener Type
Salt-based ion exchange softeners are the most widely used type in the market due to their proven effectiveness in removing calcium and magnesium ions that cause water hardness, enhancing the efficiency of plumbing and appliances by replacing hardness-causing minerals with sodium or potassium ions. While environmental concerns and regulations limiting salt discharge pose challenges, these systems continue to be favored in both residential and commercial applications. On the other hand, demand for salt-free water softeners is growing, driven by increased environmental awareness and regulatory restrictions on salt-based solutions. These systems employ alternative methods, such as template-assisted crystallization, to reduce scaling without adding sodium, appealing to eco-conscious consumers and areas with sodium discharge restrictions. Although they may not completely remove hardness minerals, their ability to minimize scaling without salt or wastewater discharge positions them as a sustainable option in the residential and commercial markets.
By Type
Twin-cylinder water softeners are ideal for commercial establishments and large households due to their continuous operation, providing uninterrupted soft water even during regeneration cycles, making them suitable for high-demand applications. Mono-cylinder systems, with their single-tank setup, are compact and cost-effective, making them a practical choice for residential and small commercial settings with moderate water usage and limited space. Multi-cylinder systems offer flexibility, scalability, and high-capacity performance, making them well-suited for industrial and large-scale commercial operations, often supporting customized configurations for specific water treatment needs.
Segments
Based on Softener Type
- Salt-Based Ion Exchange Softener
- Salt-Free Water Softener
Based on Type
- Twin Cylinder
- Mono Cylinder
- Multi-Cylinder
Based on Application
- Residential
- Commercial
- Industrial
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%)
North America holds a significant share of the global water softening system market, accounting for approximately 35% of total revenue. The region's dominance is attributed to widespread consumer awareness about water hardness and its adverse effects on health, household appliances, and infrastructure. Stringent regulations and standards concerning water quality further drive the adoption of water softening systems across residential, commercial, and industrial sectors. The United States is the key contributor, with a strong demand for both traditional salt-based and advanced salt-free systems. Investments in smart water technology and IoT-enabled softening systems continue to foster market growth, reflecting the region's emphasis on innovation and sustainability.
Europe (30%)
Europe represents around 30% of the market, driven by the presence of mature economies such as Germany, the UK, and France, where water hardness is a common issue. Regulatory initiatives mandating water quality improvement and conservation are major growth drivers. Additionally, the demand for eco-friendly, salt-free solutions has surged due to heightened environmental consciousness and stringent regulations on salt discharge. Industrial applications also play a vital role, with sectors like manufacturing and healthcare relying on water softening systems to maintain operational efficiency and comply with stringent safety standards.
Key players
- EcoWater Systems LLC (Minnesota, U.S.)
- Culligan International Company (Illinois, U.S.)
- Kinetico Incorporated (Ohio, U.S.)
- Hydroflux (Sydney, Australia)
- Envicare Technologies Pvt. Ltd. (Maharashtra, India)
- Wychwood Water Systems Ltd. (Witney, U.K.)
- Harvey Water Softeners Ltd. (England, U.K.)
- Pelican Water Systems (Florida, U.S.)
- BWT AG (Mondsee, Austria)
- Marlo Incorporated (Wisconsin, U.S.)
- Monarch Water Ltd. (Norfolk, U.K.)
- Atlas Filtri (Limena (PD), Italy)
- Watts Water Technologies Inc. (Massachusetts, U.S.)
- Feedwater Limited (England, U.K.)
Competitive Analysis
The global water softening system market features intense competition, with key players focusing on innovation, regional expansion, and customer-centric solutions to strengthen their market presence. Companies such as EcoWater Systems LLC, Culligan International, and BWT AG leverage advanced technologies and strong distribution networks to maintain market leadership. Emerging players like Hydroflux and Envicare Technologies tap into regional opportunities with tailored solutions for residential, commercial, and industrial needs. Competition is further heightened by increasing demand for eco-friendly, smart, and connected water softeners. Strategic partnerships, acquisitions, and product diversification remain core strategies for players aiming to capture and sustain market share in an evolving regulatory and environmental landscape.
Recent Developments
- In November 2023, EcoWater Systems LLC launched the eflow Tankless Reverse Osmosis System offering continuous fresh water flow with a space-saving design and user-friendly filter replacement.
- In January 2024, Culligan International Company completed acquisition of majority of Primo Water Corporation's businesses in EMEA (excluding UK, Portugal, and Israel) expanding footprint in 12 countries including Poland, Latvia, Lithuania, and Estonia.
- In April 2023, Kinetico Incorporated launched the ComfortSoft Whole House Water Softener enhancing residential water softening technology.
- In September 2023, Harvey Water Softeners Ltd announced reaching over 100,000 orders on their Harvey Shop showcasing commitment to customer satisfaction.
- In October 2023, Pelican Water Systems acquired by Pentair plc for $120 million in cash enhancing Pentair's residential water treatment business.
- December 1, 2023, BWT AG acquired Austral Distributors NZL, a leading distributor of pool and spa products in New Zealand, effective.
- In August 2024, Monarch Water Ltd launched Ultra HE and Premio HE battery-operated twin tank duplex series metered softeners designed to tackle hard water issues effectively.
- In September 2024, Atlas Filtri acquired Hydro-Flow Filtration Systems, a Californian carbon-based water filtration company, to expand product portfolio.
- In October 2023, Watts Water Technologies Inc completed acquisition of Bradley Corporation for $303 million.
- In October 2024, Feedwater limited participating in an international project to develop nano-biosensors for waterborne pathogen detection, scheduled to conclude with an international conference.
Market Concentration and Characteristics
The global water softening system market is moderately fragmented, with a mix of large multinational companies and smaller regional players. Market concentration is influenced by key factors such as technological advancements, regulatory compliance, and shifting consumer preferences toward eco-friendly solutions. While major players like EcoWater Systems LLC, Culligan International, and BWT AG hold a significant share due to their global reach and product innovation capabilities, smaller and emerging players cater to niche markets and regional demands, providing tailored solutions. The market is characterized by intense competition, a focus on sustainability, and an increasing demand for smart, connected systems that improve user convenience and efficiency. Regulatory pressures, consumer awareness about water quality, and environmental concerns drive continuous evolution in product offerings, further shaping market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Softener Type, Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness growing adoption of smart water softening systems with IoT-enabled monitoring and controls, enhancing user convenience and operational efficiency.
- Demand for salt-free and environmentally sustainable water softeners is expected to grow as consumers and industries prioritize green technologies and reduced environmental impact.
- Rapid urbanization and industrialization in regions like Asia-Pacific and Latin America will drive significant demand for residential, commercial, and industrial water softening solutions.
- Continuous innovation in water treatment technologies will lead to more efficient, low-maintenance, and high-performing water softening systems, catering to evolving market needs.
- Increasing government regulations on water quality and salt discharge will push manufacturers to develop compliant and advanced systems tailored for specific regional needs.
- Future water softening systems will emphasize energy efficiency, reducing both power consumption and operational costs for residential and industrial users.
- Rising demand for application-specific and customized water softening solutions will spur innovation, particularly in large-scale industrial and commercial sectors.
- Mergers, acquisitions, and partnerships will continue to shape the competitive landscape, allowing key players to expand their market presence and technological capabilities.
- Efforts to raise public awareness about the adverse effects of hard water and the benefits of water softening will further drive market penetration, especially in underdeveloped regions.
- The market is likely to see increased integration of water softening with advanced water filtration systems, providing comprehensive water treatment solutions for diverse consumer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Water Softening System Market in 2023 and 2032, and what is the CAGR?
What factors are driving the growth of the water softening system market?
Why are smart and connected water softening systems gaining popularity?
Which regions dominate the global water softening system market?
What role do regulatory policies play in the market's growth?
Why is the Asia-Pacific region expected to witness high growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Water Softening System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Water Softening System Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,515 million → 2032: USD 4,193.68 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Water Softening System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Water Softening System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Water Softening System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Water Softening System Market Drivers
- 3.3 Water Softening System Market Restraints & Challenges
- 3.4 Water Softening System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Water Softening System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Water Softening System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Water Softening System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Water Softening System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Water Softening System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Water Softening System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Water Softening System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Water Softening System Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Water Softening System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Water Softening System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Water Softening System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Water Softening System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Water Softening System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Water Softening System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Water Softening System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Water Softening System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Water Softening System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Water Softening System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Water Softening System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
