
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
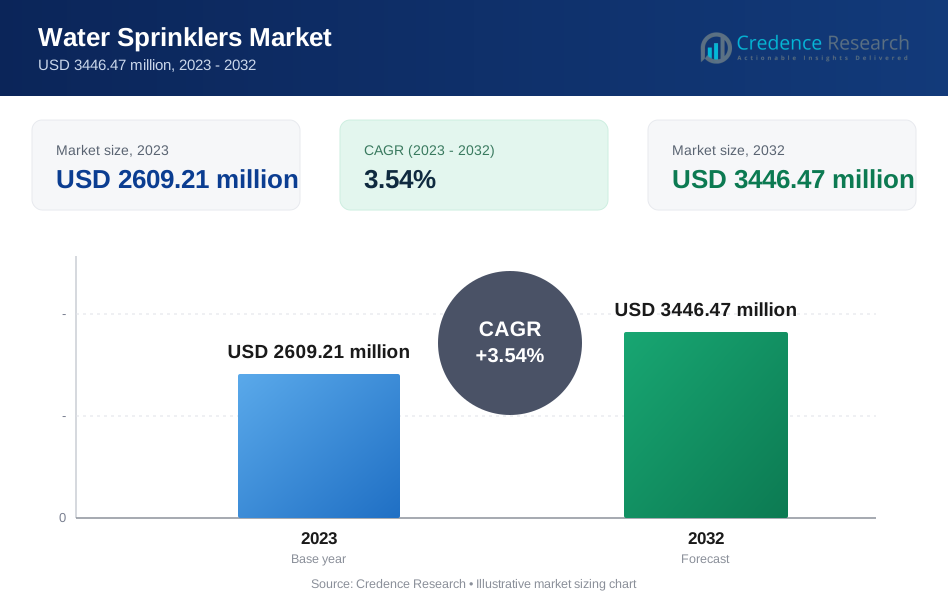
| Water Sprinklers Market Size 2023 | USD 2609.21 Million |
| Water Sprinklers Market, CAGR | 3.54% |
| Water Sprinklers Market Size 2032 | USD 3446.47 Million |
Market Overview
The global Water Sprinklers market is projected to grow from USD 2609.21 million in 2023 to an estimated USD 3446.47 million by 2032, with a compound annual growth rate (CAGR) of 3.54% from 2024 to 2032. This growth trajectory is fueled by various factors, including increasing concerns about water conservation, particularly in arid regions, coupled with the rising adoption of automated irrigation systems in agriculture. Additionally, the burgeoning trend of smart farming practices, which rely heavily on precision irrigation technologies like water sprinklers, is significantly contributing to market expansion. Furthermore, the escalating demand for efficient and sustainable irrigation solutions amidst evolving climatic conditions and water scarcity issues across the globe is expected to drive the growth of the water sprinklers market during the forecast period.
Market drivers and trends in the water sprinklers industry are characterized by technological advancements aimed at enhancing irrigation efficiency and reducing water wastage. Manufacturers are increasingly focusing on developing innovative sprinkler systems equipped with features such as sensor-based monitoring, variable rate irrigation, and remote control capabilities to optimize water usage and minimize operational costs for end-users. Moreover, the integration of artificial intelligence (AI) and Internet of Things (IoT) technologies in modern sprinkler systems is enabling real-time data analytics and predictive maintenance, thereby improving overall system performance and reliability. Additionally, the growing adoption of drip irrigation and micro-sprinkler systems, driven by their ability to deliver water directly to the root zone of plants with minimal losses, is expected to further propel market growth in the coming years.
From a geographical perspective, North America and Europe are anticipated to dominate the water sprinklers market owing to the widespread adoption of advanced irrigation technologies and favorable government initiatives promoting sustainable agriculture practices. Key players operating in the global water sprinklers market include major manufacturers such as Lindsay Corporation, Jain Irrigation Systems Ltd., The Toro Company, Valmont Industries, Inc., and Nelson Irrigation Corporation, among others. These companies are actively involved in research and development activities to introduce innovative product offerings and expand their market presence worldwide. Moreover, strategic collaborations, mergers, and acquisitions are prevalent strategies among market players to strengthen their foothold in the competitive landscape and gain a competitive edge in the global water sprinklers market.
Market Drivers
Growing Concerns about Water Conservation:
One of the primary drivers propelling the water sprinklers market is the escalating global concerns about water conservation. With the increasing strain on water resources due to factors such as population growth, urbanization, and climate change, there is a heightened emphasis on efficient water management practices, particularly in agriculture. Water sprinkler systems offer an effective solution for optimizing water usage by delivering precise amounts of water directly to crops, thereby minimizing wastage and maximizing irrigation efficiency. For example, pop-up spray sprinklers are more efficient, using only 1 to 2 gallons per hour. As governments and environmental organizations continue to advocate for sustainable water management practices, the demand for water sprinklers is expected to surge, driving market growth.
Rising Adoption of Automated Irrigation Systems:
The proliferation of automated irrigation systems is another significant driver fueling the growth of the water sprinklers market. For instance, the use of sprinkler irrigation with precision applications using automation with a sensor-based mechanism for field data collection, data transformation, data analysis, and operation of IoT-based automatic solenoid valves can save 20–30% more irrigation water and increase crop yield by 20–27%. Farmers are increasingly recognizing the benefits of transitioning from traditional irrigation methods to automated systems, which offer greater precision, consistency, and control over the irrigation process. Water sprinklers, equipped with advanced technologies such as sensors, controllers, and actuators, enable farmers to automate irrigation scheduling, monitor soil moisture levels, and adjust watering patterns based on real-time data. This automation not only enhances crop yields and quality but also minimizes labor requirements and operational costs, thereby driving the adoption of water sprinklers across agricultural landscapes globally.
Emergence of Smart Farming Practices:
The emergence of smart farming practices is driving the demand for technologically advanced irrigation solutions, including water sprinklers. Smart farming leverages cutting-edge technologies such as artificial intelligence (AI), Internet of Things (IoT), and data analytics to optimize agricultural operations and maximize resource efficiency. In the context of irrigation, smart sprinkler systems equipped with AI algorithms and IoT sensors enable precise monitoring and management of water distribution, taking into account factors such as weather conditions, soil characteristics, and crop water requirements. By facilitating data-driven decision-making and adaptive irrigation strategies, smart sprinklers contribute to improved crop health, yield optimization, and resource conservation, thereby driving their adoption among progressive farmers and agricultural enterprises worldwide.
Focus on Sustainable Agriculture:
The increasing focus on sustainable agriculture practices is driving the adoption of water sprinklers as part of holistic water management strategies. For instance, sustainable agriculture practices include the use of integrated pest management, soil conservation, and crop rotation techniques to reduce the use of chemical inputs. In response to growing environmental concerns and regulatory pressures, stakeholders across the agriculture value chain are prioritizing sustainability initiatives aimed at reducing water usage, minimizing chemical inputs, and mitigating environmental impacts. Water sprinkler systems play a crucial role in promoting sustainable irrigation practices by enabling efficient water distribution, reducing runoff and soil erosion, and supporting soil conservation efforts. As sustainability becomes a key priority for farmers, agribusinesses, and policymakers alike, the demand for water sprinklers as an environmentally friendly irrigation solution is expected to witness sustained growth, driving market expansion in the coming years.
Market Trends
Adoption of Precision Irrigation Technologies:
A notable trend in the water sprinklers market is the increasing adoption of precision irrigation technologies. Precision sprinkler systems utilize advanced tools such as GPS, soil moisture sensors, and variable rate technology to deliver water precisely where and when it is needed. For instance, the use of sprinkler irrigation with precision applications using automation with a sensor-based mechanism for field data collection, data transformation, data analysis, and operation of IoT-based automatic solenoid valves can save 20–30% more irrigation water and increase crop yield by 20–27%. This trend is driven by the growing emphasis on optimizing water usage, minimizing runoff, and improving crop yields through precise irrigation management.
Integration of IoT and AI:
Another significant trend is the integration of Internet of Things (IoT) and artificial intelligence (AI) technologies into water sprinkler systems. IoT-enabled sensors and controllers allow for real-time monitoring of environmental conditions and irrigation parameters, while AI algorithms analyze data to optimize watering schedules and distribution patterns. For example, an AI-based sprinkler irrigation system collects real-time weather data from rain sensors that measure the amount of rainfall and soil conditions to plan the next irrigation. This trend enhances the efficiency and effectiveness of water sprinklers, leading to better resource utilization and improved crop performance.
Expansion of Smart Sprinkler Systems:
Smart sprinkler systems, which offer remote monitoring and control capabilities via smartphone apps or cloud-based platforms, are experiencing rapid growth in the market. These systems allow users to adjust irrigation settings, monitor water usage, and receive alerts remotely, providing convenience and flexibility for farmers and landowners. The expansion of smart sprinkler systems reflects the increasing demand for connected and automated irrigation solutions in agriculture.
Focus on Water Conservation:
Amidst growing concerns about water scarcity and sustainability, there is a heightened focus on water conservation within the water sprinklers market. Manufacturers are developing innovative sprinkler technologies designed to minimize water wastage and maximize irrigation efficiency. Features such as pressure regulation, nozzle selection, and water-saving modes are being integrated into sprinkler designs to help users conserve water without compromising crop productivity. For instance, groundbreaking innovations have enabled the development of highly efficient sprinkler systems that can precisely manage water distribution, potentially conserving up to 30% more water compared to traditional methods.
Rise of Drip Irrigation and Micro-sprinkler Systems:
Drip irrigation and micro-sprinkler systems are gaining popularity as alternative irrigation methods to traditional overhead sprinklers. These systems deliver water directly to the root zone of plants, minimizing evaporation and runoff and maximizing water uptake efficiency. The rise of drip irrigation and micro-sprinkler systems reflects a broader trend towards more targeted and efficient irrigation practices in agriculture.
Emergence of Sustainable Irrigation Practices:
Sustainable irrigation practices, such as regenerative agriculture and agroecology, are driving innovation in the water sprinklers market. Manufacturers are developing eco-friendly sprinkler systems that support soil health, biodiversity, and ecosystem resilience. These systems are designed to minimize environmental impact while promoting long-term agricultural sustainability, aligning with the growing demand for socially and environmentally responsible farming practices.
Market Shift towards Low-Pressure Systems:
There is a noticeable shift towards low-pressure sprinkler systems in the market, driven by their ability to reduce energy consumption and operating costs. Low-pressure systems operate efficiently at lower water pressures, minimizing energy requirements for pumping and distribution. As energy efficiency and cost savings become increasingly important considerations for farmers, the demand for low-pressure sprinkler systems is expected to continue rising.
Customization and Modular Design:
Manufacturers are offering customizable and modular sprinkler systems to cater to diverse agricultural needs and preferences. These systems allow users to select components and configurations tailored to their specific crops, soil types, and field layouts. By offering flexibility and scalability, customizable and modular sprinkler systems enable users to optimize irrigation practices for maximum productivity and resource efficiency.
Market Restraints and Challenges
High Initial Investment Costs:
One of the primary restraints facing the water sprinklers market is the high initial investment required for purchasing and installing sprinkler systems. The upfront costs associated with acquiring sprinkler equipment, including pumps, pipes, valves, and control systems, can be substantial, particularly for small and medium-sized farmers with limited financial resources. Additionally, the installation expenses, such as labor costs and infrastructure modifications, further add to the overall investment burden. High initial investment costs pose a significant barrier to adoption for many potential users, especially in regions with constrained budgets or limited access to financing options.
Complexity of System Design and Installation:
The complexity of designing and installing water sprinkler systems presents a significant challenge for end-users, particularly those with limited technical expertise or access to professional assistance. Designing an effective sprinkler system requires careful consideration of factors such as crop type, field topography, soil characteristics, and water source availability. Moreover, the installation process involves coordinating multiple components and ensuring proper alignment and calibration to achieve optimal performance. The technical complexity of system design and installation can deter potential users from adopting sprinkler technology or lead to suboptimal outcomes if not executed correctly.
Maintenance and Operational Challenges:
Maintaining and operating water sprinkler systems can pose ongoing challenges for users, particularly in harsh environmental conditions or remote locations. Sprinkler equipment is susceptible to wear and tear over time, requiring regular maintenance to ensure proper functioning and longevity. Moreover, operational challenges such as clogging, leaks, and system malfunctions can disrupt irrigation schedules and compromise crop health. Addressing maintenance and operational issues often requires technical expertise and timely interventions, which may not be readily available to all users, especially in resource-constrained settings.
Dependency on Reliable Water Supply:
The effective operation of water sprinkler systems is contingent upon access to a reliable water supply, which can be a challenge in regions prone to water scarcity or variability. Dependence on surface water sources, such as rivers, lakes, or reservoirs, may expose users to fluctuations in water availability due to factors such as droughts, regulatory restrictions, or competing demands. Additionally, reliance on groundwater pumping for irrigation purposes can exacerbate groundwater depletion and aquifer degradation, leading to long-term sustainability concerns. The dependency on a reliable water supply poses a risk to the viability and continuity of water sprinkler operations, especially in regions vulnerable to water stress or climatic uncertainties.
Compatibility and Adaptation to Local Conditions:
Another challenge facing the water sprinklers market is ensuring the compatibility and adaptation of sprinkler systems to local agricultural and environmental conditions. Sprinkler technologies and designs may not always be suitable or optimized for the specific requirements and constraints of diverse farming contexts, such as smallholder agriculture, subsistence farming, or agroecological systems. Achieving compatibility and adaptation requires customization, localization, and user engagement processes to tailor sprinkler solutions to the unique needs and realities of different farming communities and landscapes. Failure to address compatibility and adaptation challenges may hinder the widespread adoption and effectiveness of water sprinkler technologies in addressing irrigation needs and promoting agricultural sustainability.
Market Segmentation Analysis
By Type
Impact sprinklers feature a rotating arm mechanism that delivers water in a circular pattern, covering a large area. Impact sprinklers are commonly used in agricultural fields and landscaping applications due to their versatility and durability. Rotating sprinklers utilize a gear-driven mechanism to disperse water in a uniform pattern over a designated area. These sprinklers are ideal for medium to large-sized lawns, gardens, and sports fields, offering customizable coverage options and efficient water distribution. Oscillating sprinklers produce a fan-shaped spray pattern by oscillating back and forth, covering a rectangular area. These sprinklers are popular for residential lawn and garden irrigation, providing gentle and even watering for delicate plants and grass. Stationary sprinklers emit water in a fixed pattern without any movement. They are suitable for small to medium-sized areas requiring targeted irrigation, such as flower beds, shrubbery, and narrow strips of lawn.
By Mechanism
Mechanical sprinklers operate based on physical mechanisms such as gears, cams, and springs to regulate water flow and distribution patterns. These sprinklers offer reliability and simplicity in operation, making them suitable for various irrigation applications. Hydraulic sprinklers utilize water pressure and hydraulic principles to control the flow and direction of water. These sprinklers are efficient and versatile, capable of delivering precise watering to different types of landscapes and crops.
By Application
Water sprinklers find extensive application in agricultural settings for crop irrigation, soil moisture management, and frost protection. They are utilized in various farming practices, including field crops, orchards, vineyards, and greenhouse cultivation, to optimize water usage and enhance crop yields. In residential settings, water sprinklers are used for lawn and garden irrigation, landscaping, and outdoor recreational areas. Homeowners rely on sprinkler systems to maintain lush green lawns, vibrant gardens, and healthy landscapes with minimal effort and water consumption. Water sprinklers are also employed in commercial and industrial sectors for landscape maintenance, dust suppression, fire protection, and cooling purposes. They play a vital role in maintaining aesthetic appeal, safety, and operational efficiency across commercial properties, industrial facilities, parks, and recreational spaces.
By Technology
Traditional sprinkler systems rely on basic mechanical components and manual controls for water distribution. They are characterized by simplicity, affordability, and ease of installation, making them suitable for a wide range of applications, especially in smaller-scale irrigation projects. Smart sprinkler systems integrate advanced technologies such as IoT sensors, AI algorithms, and cloud-based platforms to automate irrigation scheduling, optimize water usage, and monitor system performance remotely. These systems offer precision, efficiency, and convenience, catering to the needs of modern agriculture and landscaping practices.
By Distribution Channel
Sprinkler manufacturers and distributors sell their products directly to end-users through company-owned stores, online platforms, or sales representatives. Direct sales channels offer greater control over product quality, pricing, and customer relationships, facilitating personalized service and support. Indirect sales channels involve third-party retailers, dealers, distributors, and wholesalers who distribute sprinkler products to end-users through various retail outlets, home improvement stores, specialty shops, and agricultural supply stores. Indirect channels provide broader market reach, logistical support, and enhanced brand visibility for manufacturers.
Segments
Based on Type
- Impact Sprinklers
- Rotating Sprinklers
- Oscillating Sprinklers
- Stationary Sprinklers
Based on Mechanism
- Mechanical Sprinklers
- Hydraulic Sprinklers
Based on Application
- Agricultural:
- Residential
- Commercial and Industrial
Based on Technology
- Traditional Sprinkler Systems
- Smart Sprinkler Systems
Based on Distribution Channel
- Direct Sales
- Indirect Sales
Based on Region
- North America
- Europe
- Asia Pacific
- Latin America
Regional Analysis
North America (35%):
North America holds a prominent position in the global water sprinklers market, accounting for approximately 35% of the market share. The region's leadership is attributed to factors such as advanced irrigation infrastructure, extensive adoption of precision agriculture practices, and stringent regulations promoting water conservation. The United States and Canada are the primary contributors to market growth in North America, with a robust agricultural sector driving the demand for efficient irrigation technologies. Key players in this region, including Lindsay Corporation, The Toro Company, and Valmont Industries, focus on product innovation, technological advancements, and strategic partnerships to maintain market leadership and meet evolving customer demands.
Europe (25%):
Europe commands a significant share of the water sprinklers market, accounting for around 25% of the total market share. The region's market dominance is fueled by increasing environmental awareness, government initiatives promoting sustainable agriculture practices, and a growing trend towards precision irrigation technologies. Countries such as Germany, France, and Spain are key markets for water sprinklers in Europe, characterized by a strong agricultural base and high adoption rates of advanced irrigation solutions. Manufacturers in this region prioritize eco-friendly irrigation systems, smart irrigation technologies, and customized sprinkler solutions tailored to diverse agricultural landscapes and climatic conditions to maintain market competitiveness and meet customer requirements.
Asia Pacific (30%):
The Asia Pacific region is a rapidly growing market for water sprinklers, accounting for approximately 30% of the global market share. The region's market expansion is driven by factors such as expanding agricultural activities, rising food demand, and increasing investments in irrigation infrastructure. Countries like China, India, and Australia are key contributors to market growth in Asia Pacific, driven by the adoption of modern farming practices, technological innovations, and government support for agricultural development. Market players in this region focus on offering cost-effective irrigation solutions, localized product offerings, and technical support services to cater to the needs of diverse farming communities and agroecological systems, thereby sustaining market growth and competitiveness.
Key players
- Lindsay Corporation
- Jain Irrigation Systems Ltd.
- The Toro Company
- Valmont Industries, Inc.
- Nelson Irrigation Corporation
- Rain Bird Corporation
- Hunter Industries
- T-L Irrigation Co.
- Reinke Manufacturing Company, Inc.
- Netafim Ltd.
Competitive Analysis
In the highly competitive water sprinklers market, key players such as Lindsay Corporation, Jain Irrigation Systems Ltd., and The Toro Company dominate with their extensive product portfolios, technological expertise, and global market presence. These companies continuously innovate to offer advanced sprinkler systems that address evolving customer needs and industry trends. Valmont Industries, Inc., Rain Bird Corporation, and Hunter Industries are also formidable competitors, known for their commitment to quality, reliability, and customer service. Additionally, regional players like Nelson Irrigation Corporation and T-L Irrigation Co. maintain strong market positions through localized offerings and strategic partnerships. As competition intensifies, key players focus on differentiation strategies, such as product innovation, pricing strategies, and distribution channel expansion, to maintain their competitive edge and capture market share in the water sprinklers segment.
Recent Developments
In April 2023, Rivulis Pte. Ltd., a Singaporean company owned by Temasek, completed the acquisition of Jain Irrigation Company's International Irrigation Business ("IIB"). This merger positioned the combined entity as the second-largest global leader in irrigation and climate solutions. Rivulis spearheads the widespread adoption of modern irrigation technologies and digital farming practices among growers and business partners, driving innovation and sustainability in the agricultural sector.
In January 2022, the first year of a Texas A&M AgriLife Research study comparing mobile drip irrigation (MDI) to low-elevation sprinkler application (LESA) systems demonstrated promising results. Led by Charlie Rush, a Texas A&M AgriLife Plant Pathologist, the study aims to optimize irrigation methods for high-quality vegetable production. Results showed that MDI led to increased biomass, reduced water usage, and improved fruit yield, highlighting its potential for enhancing agricultural efficiency and sustainability.
In March 2022, KOMTES GROUP participated in Fire Sprinkler Europe in Madrid, showcasing their AG fire sprinkler technology. This event provided a platform for industry leaders to exchange knowledge and innovations in fire sprinkler systems, fostering collaboration and advancement in fire safety solutions.
Also in March 2022, Reliable Automatic Sprinkler Co., Inc. introduced Standard and custom printed cover plates designed for flat plate residential, commercial, and specialty concealed sprinkler systems. These cover plates enhance aesthetic appeal and customization options for sprinkler installations, meeting the diverse needs of customers across various sectors.
In January 2022, API Group Corporation announced the acquisition of the Chubb Fire & Security business, strengthening its portfolio of fire safety and security solutions. This strategic move expands API Group's market presence and capabilities, enabling it to offer comprehensive fire protection services to customers worldwide.
Market Concentration and Characteristics
The water sprinklers market exhibits a moderate level of market concentration, with a few major players dominating a significant share of the market while numerous smaller players operate in niche segments. Key characteristics of the market include technological innovation, driven by the demand for precision irrigation solutions and sustainable agriculture practices. Major players such as Lindsay Corporation, Jain Irrigation Systems Ltd., and The Toro Company invest heavily in research and development to introduce advanced sprinkler technologies and digital farming solutions. Additionally, the market is characterized by a focus on customization and localization to cater to diverse agricultural landscapes and customer preferences, along with a growing trend towards smart irrigation systems leveraging IoT and AI technologies to optimize water usage and crop productivity.
Report Coverage
The research report offers an in-depth analysis based on Type, Mechanism, Application, Technology, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued innovation in sprinkler technology, including IoT integration and AI-driven automation, will drive efficiency and precision in water distribution, meeting the evolving needs of modern agriculture.
- Growing emphasis on sustainable irrigation practices will fuel the demand for water-efficient sprinkler systems, as stakeholders prioritize resource conservation and environmental stewardship.
- The water sprinklers market is poised for significant growth, propelled by increasing adoption in emerging economies, expanding agricultural activities, and rising awareness of water scarcity issues globally.
- Smart sprinkler systems equipped with remote monitoring and predictive analytics capabilities will gain traction, enabling farmers to optimize irrigation schedules and maximize crop yields while conserving water resources.
- The integration of water sprinklers with precision farming techniques, such as GPS-guided irrigation and variable rate technology, will enhance crop management practices and improve farm productivity and profitability.
- Drip irrigation and micro-sprinkler systems will witness increased adoption, particularly in water-stressed regions, as farmers seek efficient irrigation solutions that minimize water wastage and optimize nutrient delivery to plants.
- Government initiatives promoting sustainable water management practices and incentivizing the adoption of efficient irrigation technologies will create a conducive regulatory environment for market growth.
- The water sprinklers market is likely to witness consolidation through mergers, acquisitions, and strategic alliances among key players, aimed at enhancing market competitiveness and expanding global reach.
- Heightened awareness of water scarcity and climate change impacts will drive demand for water-efficient sprinkler systems, encouraging manufacturers to develop eco-friendly and water-saving irrigation solutions.
- Increasing demand for specialized sprinkler systems tailored to specific crops, soil types, and climatic conditions will lead to market segmentation, offering opportunities for niche players to cater to specialized agricultural needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the water sprinklers market in 2023, 2032, and its Compound Annual Growth Rate (CAGR)?
What is driving the growth of the water sprinklers market?
What are some key technological trends in the water sprinklers industry?
Which regions are expected to dominate the water sprinklers market?
Who are the major players in the water sprinklers market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Water Sprinklers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Water Sprinklers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2609.21 million → 2032: USD 3446.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Water Sprinklers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Water Sprinklers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Water Sprinklers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Water Sprinklers Market Drivers
- 3.3 Water Sprinklers Market Restraints & Challenges
- 3.4 Water Sprinklers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Water Sprinklers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Water Sprinklers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Water Sprinklers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Water Sprinklers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Water Sprinklers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Water Sprinklers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Water Sprinklers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Water Sprinklers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Water Sprinklers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Water Sprinklers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Water Sprinklers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Water Sprinklers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Water Sprinklers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Water Sprinklers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Water Sprinklers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Water Sprinklers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Water Sprinklers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Water Sprinklers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Water Sprinklers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
