
Market Overview:
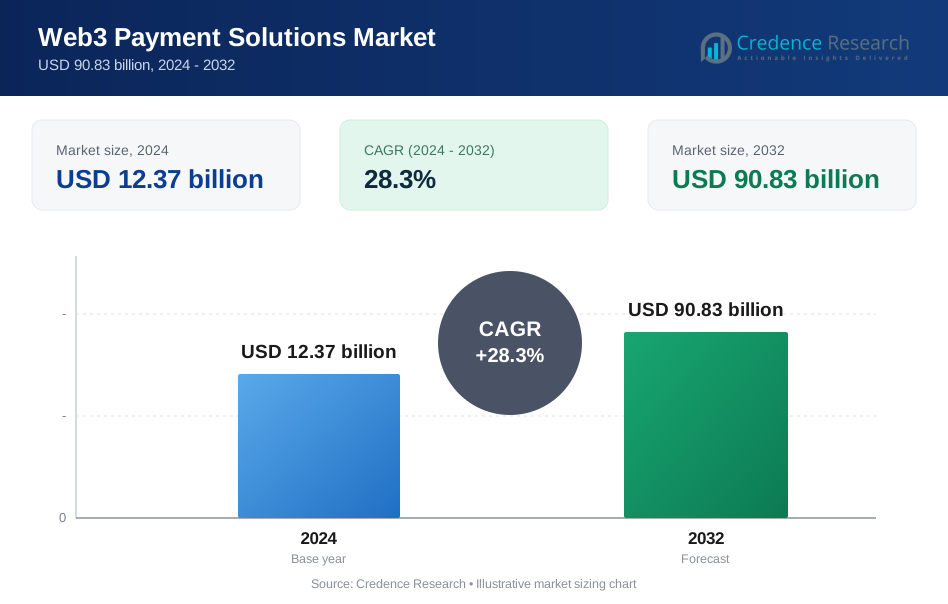
The Web3 payment solutions market was valued at USD 12.37 billion in 2024 and is projected to reach USD 90.83 billion by 2032, growing at a CAGR of 28.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Web3 Payment Solutions Market Size 2024 | USD 12.37 billion |
| Web3 Payment Solutions Market, CAGR | 28.3% |
| Web3 Payment Solutions Market Size 2032 | USD 90.83 billion |
The Web3 payment solutions market is led by major players including MoonPay, Stripe, Ripple, BitPay, PayPal, Coinbase Commerce, Visa, Alchemy Pay, Circle, and Binance Pay. These companies are driving adoption through secure payment infrastructure, multi-chain support, and seamless integration with e-commerce and DeFi platforms. North America dominated with 38% share in 2024, supported by high crypto adoption and institutional investment in blockchain solutions. Europe held 27% share, driven by strong regulatory frameworks and merchant acceptance of crypto payments, while Asia-Pacific captured 25% share, fueled by CBDC pilots, cross-border remittance demand, and rapid growth of Web3 gaming and NFT ecosystems.

Market Insights
- The Web3 payment solutions market was valued at USD 12.37 billion in 2024 and is projected to reach USD 90.83 billion by 2032, growing at a CAGR of 28.3% during the forecast period.
- Growth is driven by rising adoption of cryptocurrency payments, DeFi platforms, and smart contract-enabled solutions that enable low-cost, secure, and borderless transactions.
- Key trends include the expansion of stablecoin usage, integration of Web3 payments with e-commerce and gaming platforms, and development of Layer-2 solutions to improve transaction speed and scalability.
- The market is competitive with players like MoonPay, Stripe, Ripple, BitPay, PayPal, Coinbase Commerce, Visa, Alchemy Pay, Circle, and Binance Pay focusing on partnerships, regulatory compliance, and multi-chain support.
- North America led with 38% share, followed by Europe at 27% and Asia-Pacific at 25%; by type, cryptocurrency payments dominated with over 45% share, making it the largest contributor to global transaction volumes.
Market Segmentation Analysis:
By Type
Cryptocurrency payments dominated the Web3 payment solutions market in 2024, holding over 45% share due to their increasing adoption for retail transactions, gaming, and e-commerce. Bitcoin, Ethereum, and stablecoins are the most widely used tokens, driven by their global acceptance and ease of integration with payment gateways. Rising merchant adoption and consumer preference for decentralized, low-cost transactions are accelerating growth. NFT-based payments and DeFi payment solutions are gaining traction, especially in digital collectibles, Web3 gaming, and decentralized marketplaces, where secure, traceable transactions are critical for value transfer.
- For instance, BitPay processed over 600,000 cryptocurrency transactions in 2024, led by Litecoin, Bitcoin, and Ethereum payments, and highlighted a growing willingness among holders to use digital assets for spending on luxury goods, electronics, and other items.
By Deployment Model
On-chain solutions accounted for more than 50% share in 2024, supported by their transparency, immutability, and trustless nature. Businesses and users prefer on-chain transactions for high-value payments and scenarios requiring automated verification through blockchain smart contracts. The growth of Layer-2 scaling solutions such as rollups has reduced transaction costs, making on-chain payments faster and more affordable. Off-chain and hybrid models are also growing as they provide scalability and reduced latency, supporting real-time micropayments and enabling a seamless user experience in decentralized applications and cross-border remittance systems.
- For instance, the Polygon network's Proof-of-Stake (PoS) chain registered an average of 4.1 million daily transactions in Q2 2024, with its suite of scaling solutions including sidechains and zero-knowledge (ZK) rollups.
By Application
Peer-to-peer transactions held the largest share, exceeding 40% in 2024, driven by rising use of crypto wallets and dApps for direct, borderless value exchange. Consumers increasingly use Web3 solutions for instant money transfers, bypassing traditional intermediaries and reducing transaction fees. Cross-border remittances are another fast-growing application, supported by stablecoin adoption and integration of crypto payments into remittance platforms. Micropayments are expanding, enabling content creators, gamers, and service providers to monetize small, recurring transactions efficiently. This broadening application base continues to drive overall adoption across emerging and developed markets.
Market Overview
Rising Adoption of Cryptocurrencies for Payments
Growing use of cryptocurrencies like Bitcoin, Ethereum, and stablecoins as a medium of exchange is a major growth driver. Merchants are increasingly integrating crypto payment gateways to accept decentralized transactions, reducing reliance on traditional banking systems. Low transaction fees, faster settlement times, and global accessibility are driving adoption across e-commerce, gaming, and peer-to-peer platforms. This shift is supported by increasing wallet penetration and user familiarity with blockchain technology, making cryptocurrency payments one of the most significant contributors to Web3 payment market growth.
- For instance, over 560 million cryptocurrency users were recorded worldwide in 2024, facilitating over 1.1 billion stablecoin transactions in Q2 2024 alone, which contributed to a yearly transaction volume of $27.6 trillion, although the vast majority of this volume was driven by high-frequency trading bots rather than broad utility across decentralized platforms.
Growth of Decentralized Finance (DeFi) Ecosystem
The rapid expansion of DeFi platforms is fueling demand for Web3 payment solutions. Users are leveraging decentralized exchanges, lending platforms, and staking protocols to execute seamless, trustless payments. Smart contract-enabled transactions offer transparency and security, eliminating intermediaries and reducing costs. DeFi-based stablecoins are being widely used for remittances and cross-border settlements, providing price stability and instant transfers. This growing ecosystem is encouraging businesses and developers to adopt Web3 payment infrastructure, accelerating market growth and creating new revenue models for decentralized applications.
- For instance, Ethereum Layer-2 rollups processed billions of transactions in 2024, facilitating efficient DeFi operations with varying finality times and significantly reduced gas fees, in some cases by over 95%, enhancing accessibility and cost-effectiveness.
Integration of Web3 Payments in E-commerce and Gaming
E-commerce platforms and Web3 gaming ecosystems are emerging as significant drivers for payment solution adoption. Businesses are incorporating blockchain-based payments to offer tokenized rewards, loyalty programs, and NFT-based purchases. Gamers prefer crypto transactions for in-game assets, skins, and play-to-earn models, boosting demand for instant and secure payments. Integration of Web3 wallets with mainstream platforms is making it easier for users to transact, contributing to broader acceptance of decentralized payment systems and creating strong momentum for market expansion in consumer-facing sectors.
Key Trends & Opportunities
Growth of Stablecoin and CBDC Adoption
Stablecoins are becoming the preferred choice for Web3 payments due to their price stability and low volatility compared to cryptocurrencies. Businesses and consumers are using stablecoins for cross-border payments and payroll transactions to avoid currency fluctuations. Central Bank Digital Currencies (CBDCs) under development worldwide are expected to integrate with Web3 platforms, offering regulated and secure payment channels. This trend opens opportunities for payment providers to bridge traditional finance with decentralized ecosystems and attract institutional participants into the market.
- For instance, while the total transaction volume of stablecoins, which is heavily inflated by automated crypto trading and exchange activity, did surpass the combined transaction volume of Visa and Mastercard in 2024, the volume attributed to actual, real-world payments was significantly smaller. Estimates suggest that organic, real-world payments account for as little as 1–10% of the total recorded stablecoin volume.
Development of Layer-2 and Scalable Payment Infrastructure
Layer-2 scaling solutions like rollups and sidechains are enabling faster, cheaper, and more energy-efficient Web3 payments. These technologies address network congestion and high gas fees, making blockchain-based transactions more viable for micropayments and retail use cases. Payment solution providers are adopting hybrid models combining on-chain security with off-chain speed to enhance user experience. This creates significant opportunities for mass adoption, particularly in emerging markets where low-cost, real-time transactions are critical for financial inclusion.
- For instance, by mid-2025, the number of active DeFi wallets globally reached over 14.2 million, with weekly transaction volumes exceeding $48 billion, supporting a broad range of lending, trading, and staking services across platforms like Ethereum and BNB Chain.
Key Challenges
Regulatory Uncertainty and Compliance Risks
Lack of clear regulations around crypto transactions and decentralized finance remains a significant challenge for market participants. Businesses face uncertainty over taxation, AML/KYC requirements, and potential restrictions on crypto usage in certain countries. This regulatory ambiguity slows enterprise adoption and discourages institutional investors. Payment providers must invest in compliance solutions and work with regulators to develop frameworks that balance innovation with consumer protection, ensuring long-term growth and stability for the Web3 payment ecosystem.
Security Risks and Fraud Concerns
Web3 payment systems are vulnerable to hacks, phishing attacks, and smart contract exploits, which can result in significant financial losses. High-profile breaches erode user trust and slow adoption among businesses and consumers. The decentralized nature of blockchain makes reversing fraudulent transactions difficult, adding to risk. To address this challenge, solution providers are enhancing wallet security, auditing smart contracts, and integrating insurance protocols. Building robust security frameworks is essential for fostering confidence and driving mass adoption of Web3 payment solutions.
Regional Analysis
North America
North America held 38% share of the Web3 payment solutions market in 2024, driven by strong adoption of cryptocurrencies, NFT payments, and DeFi platforms. The U.S. leads the region due to a mature blockchain ecosystem, high wallet penetration, and supportive institutional investments. Major payment processors and fintechs are integrating Web3 infrastructure, enabling seamless crypto-to-fiat conversions. Canada is witnessing steady growth fueled by regulatory clarity and growing interest in CBDC pilots. The region’s focus on innovation, coupled with rising enterprise blockchain adoption, continues to reinforce North America’s dominant position in this fast-growing market.
Europe
Europe accounted for 27% share in 2024, supported by strict regulatory frameworks such as MiCA that promote safe and transparent crypto transactions. The region is home to a growing number of DeFi startups, blockchain payment processors, and NFT marketplaces. Germany, Switzerland, and the UK lead adoption, driven by merchant acceptance of crypto payments and government-backed digital currency initiatives. European banks and financial institutions are exploring blockchain-based settlement systems, boosting enterprise adoption. Rising consumer demand for secure, low-fee cross-border transactions is expected to drive continued growth across Europe’s Web3 payment ecosystem.
Asia-Pacific
Asia-Pacific captured 25% share of the market in 2024, emerging as one of the fastest-growing regions for Web3 payment solutions. China, India, and Singapore are leading contributors, supported by thriving blockchain developer communities and increasing retail crypto participation. Government-backed pilot projects for CBDCs and digital wallets are accelerating mainstream adoption. Cross-border remittance demand in Southeast Asia and strong growth of Web3 gaming and NFTs are fueling transaction volumes. The region’s cost-sensitive market is pushing innovation in scalable, low-fee payment infrastructure, making Asia-Pacific a key growth driver for the overall industry.
Latin America
Latin America held 6% share of the Web3 payment solutions market in 2024, driven by demand for low-cost remittance services and alternatives to inflation-affected fiat currencies. Countries such as Brazil, Argentina, and Mexico are leading adoption, with growing use of stablecoins for everyday payments. Merchant acceptance of crypto payments is rising, particularly in e-commerce and retail. Government initiatives supporting blockchain education and financial inclusion are improving accessibility. Despite regulatory fragmentation, Latin America continues to gain traction as a high-potential region for decentralized finance and peer-to-peer Web3 payment solutions.
Middle East & Africa
The Middle East & Africa region accounted for 4% share in 2024, supported by increasing adoption of Web3 payment systems for cross-border trade and remittances. The UAE and Saudi Arabia are leading markets, with significant investment in blockchain infrastructure and digital currency pilots. Africa’s adoption is driven by the need for financial inclusion, with crypto wallets enabling access to payments for the unbanked population. Regulatory clarity remains a challenge in some countries, but government-led blockchain projects and rising merchant participation are expected to drive gradual market expansion across this region in the coming years.
Market Segmentations:
By Type
- Cryptocurrency Payments
- NFT-based Payments
- Decentralized Finance (DeFi) Payment
- Smart Contract-enabled Payments
By Deployment Model
- On-chain Solutions
- Off-chain Solutions
- Hybrid Models
By Application
- Peer-to-peer Transactions
- Cross-border Remittances
- Micropayments
- Others
By End User
- Individual Consumers
- SME
- Large Enterprises
- Decentralized Autonomous Organizations (DAOs)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the Web3 payment solutions market is defined by major players such as MoonPay, Stripe, Ripple, BitPay, PayPal, Coinbase Commerce, Visa, Alchemy Pay, Circle, and Binance Pay. These companies are focusing on building scalable, secure, and user-friendly platforms to enable crypto transactions for both consumers and businesses. Strategic partnerships with merchants, e-commerce platforms, and DeFi projects are strengthening their market presence. Players are expanding support for multiple cryptocurrencies, stablecoins, and fiat on-ramps to increase accessibility. Investment in compliance solutions and regulatory alignment is becoming a priority to attract institutional adoption. Many providers are also integrating Layer-2 and cross-chain payment capabilities to reduce transaction costs and improve speed. Continuous innovation, global expansion, and integration with Web3 wallets are expected to shape competition as companies work to capture a growing share of the decentralized payments market.
Key Player Analysis
Recent Developments
- In September 2025, Alchemy Pay partnered with Fiat24 (a Swiss-regulated fintech) to enhance its Web3 Digital Banking service
- In August 2025, Wirex (partnered with Visa) went live with EURC (Circle’s euro-backed stablecoin) real-time settlements in Europe.
- In August 2025, Alchemy Pay formed a partnership with MTT Sports (Web3 gaming) to enable fiat-crypto payments in the gaming platform.
- In August 2025, Alchemy Pay also integrated with Sahara AI (its native token), supporting direct fiat purchases of SAHARA.
Report Coverage
The research report offers an in-depth analysis based on Type, Deployment Model, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of Web3 payment solutions will accelerate as businesses embrace crypto and DeFi integrations.
- Cryptocurrency payments will remain the largest segment with growing use in retail and e-commerce.
- Stablecoin usage will rise, supporting cross-border payments and payroll solutions.
- Layer-2 and cross-chain technologies will enhance transaction speed and reduce network fees.
- Asia-Pacific will see rapid growth driven by CBDC pilots and Web3 gaming expansion.
- North America will maintain leadership with strong institutional investment and merchant acceptance.
- NFT-based payments will gain traction in gaming, digital art, and metaverse commerce.
- Regulatory clarity will improve, encouraging enterprise adoption and mainstream integration.
- Security enhancements and fraud prevention measures will boost user trust and participation.
- Strategic partnerships between payment providers and fintech firms will expand ecosystem reach globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Web3 Payment Solutions market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Web3 Payment Solutions market projected to grow between 2025 and 2032?
Which Web3 Payment Solutions market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Web3 Payment Solutions market?
Who are the leading companies in the Web3 Payment Solutions market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Web3 Payment Solutions Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Web3 Payment Solutions Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12.37 billion → 2032: USD 90.83 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Web3 Payment Solutions Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Web3 Payment Solutions Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Web3 Payment Solutions Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Web3 Payment Solutions Market Drivers
- 3.3 Web3 Payment Solutions Market Restraints & Challenges
- 3.4 Web3 Payment Solutions Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Web3 Payment Solutions Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Web3 Payment Solutions Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Web3 Payment Solutions category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Web3 Payment Solutions Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Web3 Payment Solutions Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Web3 Payment Solutions market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Web3 Payment Solutions Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Web3 Payment Solutions Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Web3 Payment Solutions Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Web3 Payment Solutions (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Web3 Payment Solutions Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Web3 Payment Solutions Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Web3 Payment Solutions Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Web3 Payment Solutions Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Web3 Payment Solutions Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Web3 Payment Solutions Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Web3 Payment Solutions Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Web3 Payment Solutions Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Web3 Payment Solutions Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
