
Market Overview:
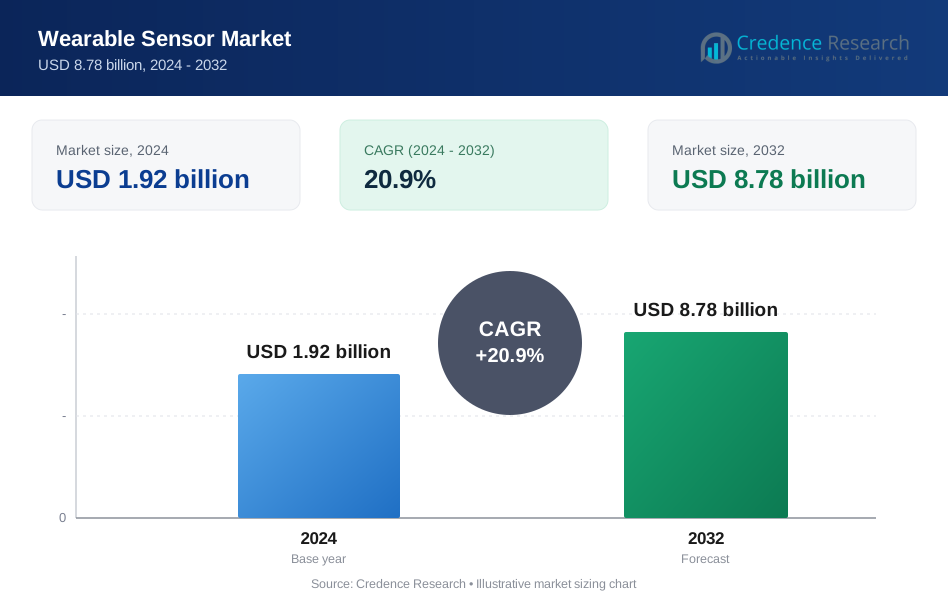
Wearable Sensor Market size was valued USD 1.92 billion in 2024 and is anticipated to reach USD 8.78 billion by 2032, at a CAGR of 20.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wearable Sensor Market Size 2024 | USD 1.92 billion |
| Wearable Sensor Market, CAGR | 20.9% |
| Wearable Sensor Market Size 2032 | USD 8.78 billion |
The wearable sensor market is driven by strong competition among leading players such as Sensirion AG, Robert Bosch GmbH, Panasonic Corporation, TE Connectivity, Knowles Electronics, LLC., STMicroelectronics, Asahi Kasei Microdevices Corporation, Infineon Technologies AG, InvenSense, and NXP Semiconductors. These companies focus on innovation in motion, environmental, and biosensing technologies, supported by advancements in IoT and AI integration. Strategic collaborations with healthcare providers, consumer electronics firms, and industrial sectors strengthen their global presence. North America leads the market with a 34% share, supported by high consumer adoption, strong digital health infrastructure, and widespread use of connected devices in healthcare and lifestyle applications.
Market Insights
- The wearable sensor market was valued at USD 1.92 billion in 2024 and will reach USD 8.78 billion by 2032, growing at a CAGR of 20.9%.
- Rising demand for health and fitness monitoring, coupled with advancements in IoT and AI integration, is driving market growth.
- The market is highly competitive, with players focusing on motion, environmental, and biosensing technologies, alongside strategic collaborations across healthcare and consumer electronics.
- High costs and data privacy concerns act as restraints, limiting adoption in price-sensitive and regulation-heavy regions.
- North America leads with a 34% share, Europe follows with 28%, and Asia-Pacific holds 25%, while wristwear dominates the application segment supported by strong consumer adoption.
Market Segmentation Analysis:
By Type
Accelerometers hold the largest share in the wearable sensor market due to their critical role in motion tracking, fitness monitoring, and activity recognition. Their compact design, low power consumption, and high accuracy make them essential in wristbands, smartwatches, and bodywear devices. Increasing demand for health monitoring and sports performance tracking further boosts adoption. Integration with gyroscopes and magnetometers in multi-sensor modules strengthens their dominance, as manufacturers prioritize devices that capture precise body movements and improve overall user experience.
- For instance, InvenSense’s MPU-6050 module offers 3-axis accelerometer + 3-axis gyroscope in a single chip, enabling motion tracking with ranges of ±2g, ±4g, ±8g, or ±16g.
By Application
Wristwear dominates the application segment, driven by strong adoption of smartwatches and fitness trackers. These devices leverage multiple sensors for continuous heart rate monitoring, step counting, sleep analysis, and health alerts. Rising consumer interest in preventive healthcare and lifestyle management supports consistent demand. Major players expand offerings with advanced features such as ECG tracking and oxygen saturation monitoring, solidifying wristwear’s market position. Growing integration with mobile apps and cloud platforms also drives long-term usage among consumers and healthcare providers.
- For instance, Bosch BMA456 accelerometer, which operates in a ±2 g to ±16 g measurement range. The BMA456 delivers 16-bit resolution, weighs in a 2 × 2 × 0.65 mm³ LGA package, and in high-performance mode consumes about 150 µA current; in low-power mode (50 Hz output data rate) consumption drops to around 14 µA.
By Vertical
The consumer segment leads the wearable sensor market, fueled by widespread use in personal fitness and lifestyle devices. Consumers increasingly adopt smartwatches, fitness trackers, and eyewear to monitor activity levels, sleep, and wellness indicators. Affordable pricing, stylish designs, and continuous product innovation attract mass-market buyers. Healthcare applications are growing rapidly but remain secondary to consumer adoption. Expanding awareness of connected health and integration with telemedicine platforms will continue to reinforce consumer-driven demand, ensuring sustained leadership of this vertical.
Market Overview
Rising Adoption of Health and Fitness Monitoring
Growing consumer focus on fitness and preventive healthcare is driving demand for wearable sensors. Devices such as smartwatches, wristbands, and bodywear integrate sensors to track heart rate, sleep patterns, oxygen saturation, and activity levels. Increasing cases of lifestyle diseases and rising awareness of personal health management further accelerate adoption. Fitness-conscious individuals and patients with chronic conditions are key contributors to this growth. Manufacturers leverage advanced biosensors and AI-driven insights, positioning wearable technology as an essential tool for continuous, real-time health monitoring.
- For instance, Panasonic and Kyoto University developed a millimeter-wave spread-spectrum radar prototype operating at 79 GHz, capable of measuring heart rate and heartbeat interval remotely without contact. It also distinguishes multiple individuals separated by as little as 7.5 cm.
Integration with IoT and Connected Ecosystems
Wearable sensors are increasingly integrated into IoT platforms, enabling seamless connectivity with smartphones, smart homes, and healthcare systems. This integration provides real-time data sharing, remote patient monitoring, and personalized insights. Hospitals and clinics adopt wearable-enabled remote diagnostics, reducing in-person visits while improving patient care. Industrial and sports applications also benefit from predictive analytics supported by connected wearable devices. Growing 5G adoption further enhances real-time communication and sensor accuracy. The expansion of smart ecosystems strongly drives demand for wearable sensors across multiple verticals.
- For instance, TE’s piezo film sensors can detect breathing and pulse from contact, registering respiratory rates down to about 5 breaths per minute and pulse vibrations with microstrain sensitivity in the low microstrain (µε) range.
Advancements in Sensor Technology
Continuous innovations in sensor miniaturization, power efficiency, and accuracy significantly enhance wearable devices’ performance. Companies invest in advanced biosensors capable of monitoring multiple health parameters, including blood pressure and glucose levels. Development of flexible, skin-friendly, and energy-efficient sensors boosts adoption in bodywear and medical applications. Improved data analytics and integration with AI platforms provide actionable insights for consumers and healthcare providers. These technological advancements expand the scope of wearable sensors, creating new opportunities across consumer electronics, healthcare, and industrial sectors.
Key Trends & Opportunities
Shift Toward Healthcare and Medical Applications
Wearable sensors are transitioning beyond consumer fitness into advanced healthcare applications. Remote patient monitoring, chronic disease management, and elderly care benefit from continuous data collection. Hospitals and telemedicine providers increasingly use wearable-enabled diagnostics for personalized treatments. The demand for medical-grade accuracy and FDA-approved devices creates opportunities for innovation. As populations age and healthcare systems focus on preventive care, wearable sensors are positioned as a vital component of digital health solutions, driving growth across global healthcare markets.
- For instance, STMicroelectronics introduced the ST1VAFE3BX biosensor chip combining a vertical analog front end (vAFE) for cardio/neurological inputs, a 3-axis accelerometer, and an on-chip AI core.
Growth of Smart Fabrics and Flexible Electronics
Smart textiles and flexible electronics represent a key trend in wearable sensor development. Companies are embedding sensors directly into fabrics, enabling unobtrusive health monitoring and activity tracking. Lightweight, comfortable, and washable designs increase user acceptance in bodywear and sports applications. Flexible sensors also expand opportunities in medical patches and rehabilitation devices. With rising demand for discreet and comfortable solutions, the adoption of textile-integrated wearable sensors is set to accelerate. This trend offers strong potential for innovation and product differentiation.
- For instance, AKM’s AK9757P infrared temperature sensor measures only 1.6 mm × 1.76 mm, and can detect temperature within ±0.2 °C even when separated by a small air gap - this enables its use in wearables like earbuds, hearing aids, and smartwatches.
Key Challenges
Data Privacy and Security Concerns
Wearable sensors continuously collect sensitive health and activity data, raising concerns about privacy and cybersecurity. Breaches in data protection can lead to consumer distrust and regulatory hurdles. Healthcare applications, in particular, require strict compliance with data protection laws such as HIPAA and GDPR. Manufacturers face pressure to implement robust encryption, secure data transfer, and transparent consent mechanisms. Addressing these issues is critical to sustaining adoption, as consumers and institutions demand reliable safeguards for personal and medical information.
High Costs and Limited Battery Life
Advanced wearable sensors often involve high development costs and complex manufacturing processes, making devices expensive for consumers. Limited battery capacity further restricts adoption, as frequent charging reduces user convenience. High-end devices offering medical-grade accuracy or multi-parameter tracking remain unaffordable for price-sensitive markets. Manufacturers face the challenge of balancing affordability with advanced features while improving energy efficiency. Innovations in low-power electronics and cost-effective materials are necessary to overcome these barriers and expand adoption across wider consumer and healthcare segments.
Regional Analysis
North America
North America leads the wearable sensor market with a 34% share, driven by strong consumer adoption of fitness trackers, smartwatches, and healthcare wearables. High awareness of preventive healthcare and widespread access to advanced technology support consistent growth. The U.S. dominates regional demand due to large-scale use of remote patient monitoring and integration of wearable devices into telemedicine platforms. Strong R&D investments by key players and collaborations with healthcare providers enhance market expansion. Government focus on digital health infrastructure and insurance coverage for remote monitoring further strengthens the adoption of wearable sensors in this region.
Europe
Europe holds a 28% share of the wearable sensor market, supported by growing healthcare digitization and consumer adoption of connected devices. Countries such as Germany, the U.K., and France lead due to strong demand for medical-grade wearables and fitness devices. Regulatory support for digital health solutions and investments in telehealth initiatives strengthen regional growth. Expanding aging populations create demand for continuous health monitoring solutions, especially in elderly care. European companies focus on innovation in biosensors and smart textiles, driving product diversification. High consumer awareness and integration of wearables in workplace wellness programs further support market expansion.
Asia-Pacific
Asia-Pacific accounts for a 25% share of the wearable sensor market and represents the fastest-growing region. Rising urbanization, increasing health awareness, and a rapidly expanding middle-class consumer base drive adoption of wearable devices. China, Japan, and India dominate regional growth, with significant demand for smartwatches and bodywear for health monitoring and lifestyle management. Government initiatives promoting digital healthcare and strong investments by regional electronics manufacturers accelerate market expansion. Affordable devices offered by local players expand accessibility, while rising adoption of fitness trends and smartphone penetration reinforce Asia-Pacific as a high-growth hub for wearable sensors.
Latin America
Latin America holds an 8% share of the wearable sensor market, driven by growing consumer interest in fitness tracking and preventive healthcare. Brazil and Mexico lead regional adoption, supported by expanding smartphone penetration and rising awareness of lifestyle management. Healthcare providers are gradually integrating wearable technology for remote monitoring, though adoption remains limited by affordability and infrastructure challenges. Increasing investments from international players and the introduction of cost-effective wearable devices support growth. With a younger demographic showing strong interest in connected devices, Latin America is expected to emerge as a promising market for wearable sensors over the forecast period.
Middle East & Africa
The Middle East & Africa account for a 5% share of the wearable sensor market, with gradual adoption across healthcare, consumer, and industrial applications. The Gulf countries, including the UAE and Saudi Arabia, lead regional demand due to strong investments in digital health infrastructure and rising consumer spending on smart devices. Wearable sensors are increasingly used in corporate wellness programs and chronic disease management. However, limited affordability and lack of awareness in parts of Africa restrict widespread adoption. As governments invest in healthcare modernization and connected ecosystems, the region is poised for steady long-term growth.
Market Segmentations:
By Type:
- Accelerometer
- Gyroscope
By Application:
- Eyewear
- Wristwear
By Vertical:
- Consumer
- Healthcare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The wearable sensor market is highly competitive, with key players including Sensirion AG, Robert Bosch GmbH, Panasonic Corporation, TE Connectivity, Knowles Electronics, LLC. Itasca, IL, USA., STMicroelectronics, Asahi Kasei Microdevices Corporation, Infineon Technologies AG, InvenSense, and NXP Semiconductors. The wearable sensor market is characterized by intense competition, rapid technological advancements, and continuous innovation. Companies focus heavily on improving sensor accuracy, reducing power consumption, and enhancing integration with IoT and AI platforms. The market is shaped by strong demand across consumer electronics, healthcare, and industrial applications, driving ongoing product diversification. Manufacturers invest in R&D to develop miniaturized and multifunctional sensors capable of monitoring multiple health and environmental parameters. Strategic collaborations with healthcare providers, fitness brands, and technology firms strengthen market positioning. This competitive environment ensures sustained innovation, fostering growth opportunities across global wearable applications.
Key Player Analysis
- Sensirion AG
- Robert Bosch GmbH
- Panasonic Corporation
- TE Connectivity
- Knowles Electronics, LLC. Itasca, IL, USA.
- STMicroelectronics
- Asahi Kasei Microdevices Corporation
- Infineon Technologies AG
- InvenSense
- NXP Semiconductors
Recent Developments
- In May 2024, Sensirion introduced SLD 3 series, miniature liquid flow sensor platform, for delivering drugs subcutaneously. Sensirion customizable solutions ensure optimal closing, thereby enhancing patient safety for therapies requiring subcutaneous drug delivery.
- In April 2024, The U.S. Army is considering using wearable technology to monitor traumatic brain injuries in soldiers assigned to high-risk roles. Additionally, the Army is exploring options for providing additional personal protective gear to personnel, such as instructors, who are regularly exposed to blast pressures.
- In January 2024, SOSSEC, Inc. awarded Elbit Systems an Other Transaction Authority contract through the Sensors, Communication, and Electronics Consortium (SCEC) to develop the prototype of the Integrated Headborne Sensor System (IHSS) for dismounted Soldiers in the U.S. Army.
- In May 2023, STMicroelectronics introduces market-first waterproof MEMS pressure sensor with 10-year longevity for Industrial IoT expansion.These sensors are particularly applicable in gas and water-metering equipment, weather monitoring, air conditioning, and home appliances
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for health and fitness monitoring devices.
- Integration of wearable sensors with AI will improve predictive health insights.
- Remote patient monitoring will become a major growth driver in healthcare adoption.
- Smart textiles and flexible electronics will boost demand for body-integrated sensors.
- IoT connectivity and 5G networks will enhance real-time data transmission and accuracy.
- Consumer adoption will rise with affordable devices and multifunctional sensor capabilities.
- Industrial applications will grow, focusing on worker safety and productivity monitoring.
- Battery efficiency improvements will extend device usability and user convenience.
- Regulatory approvals will accelerate adoption of medical-grade wearable devices.
- Continuous innovation in miniaturization will expand applications across new verticals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wearable Sensor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wearable Sensor Market projected to grow between 2025 and 2032?
Which Wearable Sensor Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wearable Sensor Market?
Who are the leading companies in the Wearable Sensor Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wearable Sensor Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wearable Sensor Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.92 billion → 2032: USD 8.78 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wearable Sensor Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wearable Sensor Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wearable Sensor Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wearable Sensor Market Drivers
- 3.3 Wearable Sensor Market Restraints & Challenges
- 3.4 Wearable Sensor Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wearable Sensor Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wearable Sensor Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wearable Sensor category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wearable Sensor Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wearable Sensor Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wearable Sensor market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wearable Sensor Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wearable Sensor Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wearable Sensor Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wearable Sensor (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wearable Sensor Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wearable Sensor Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wearable Sensor Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wearable Sensor Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wearable Sensor Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wearable Sensor Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wearable Sensor Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wearable Sensor Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wearable Sensor Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
