
Market Overview
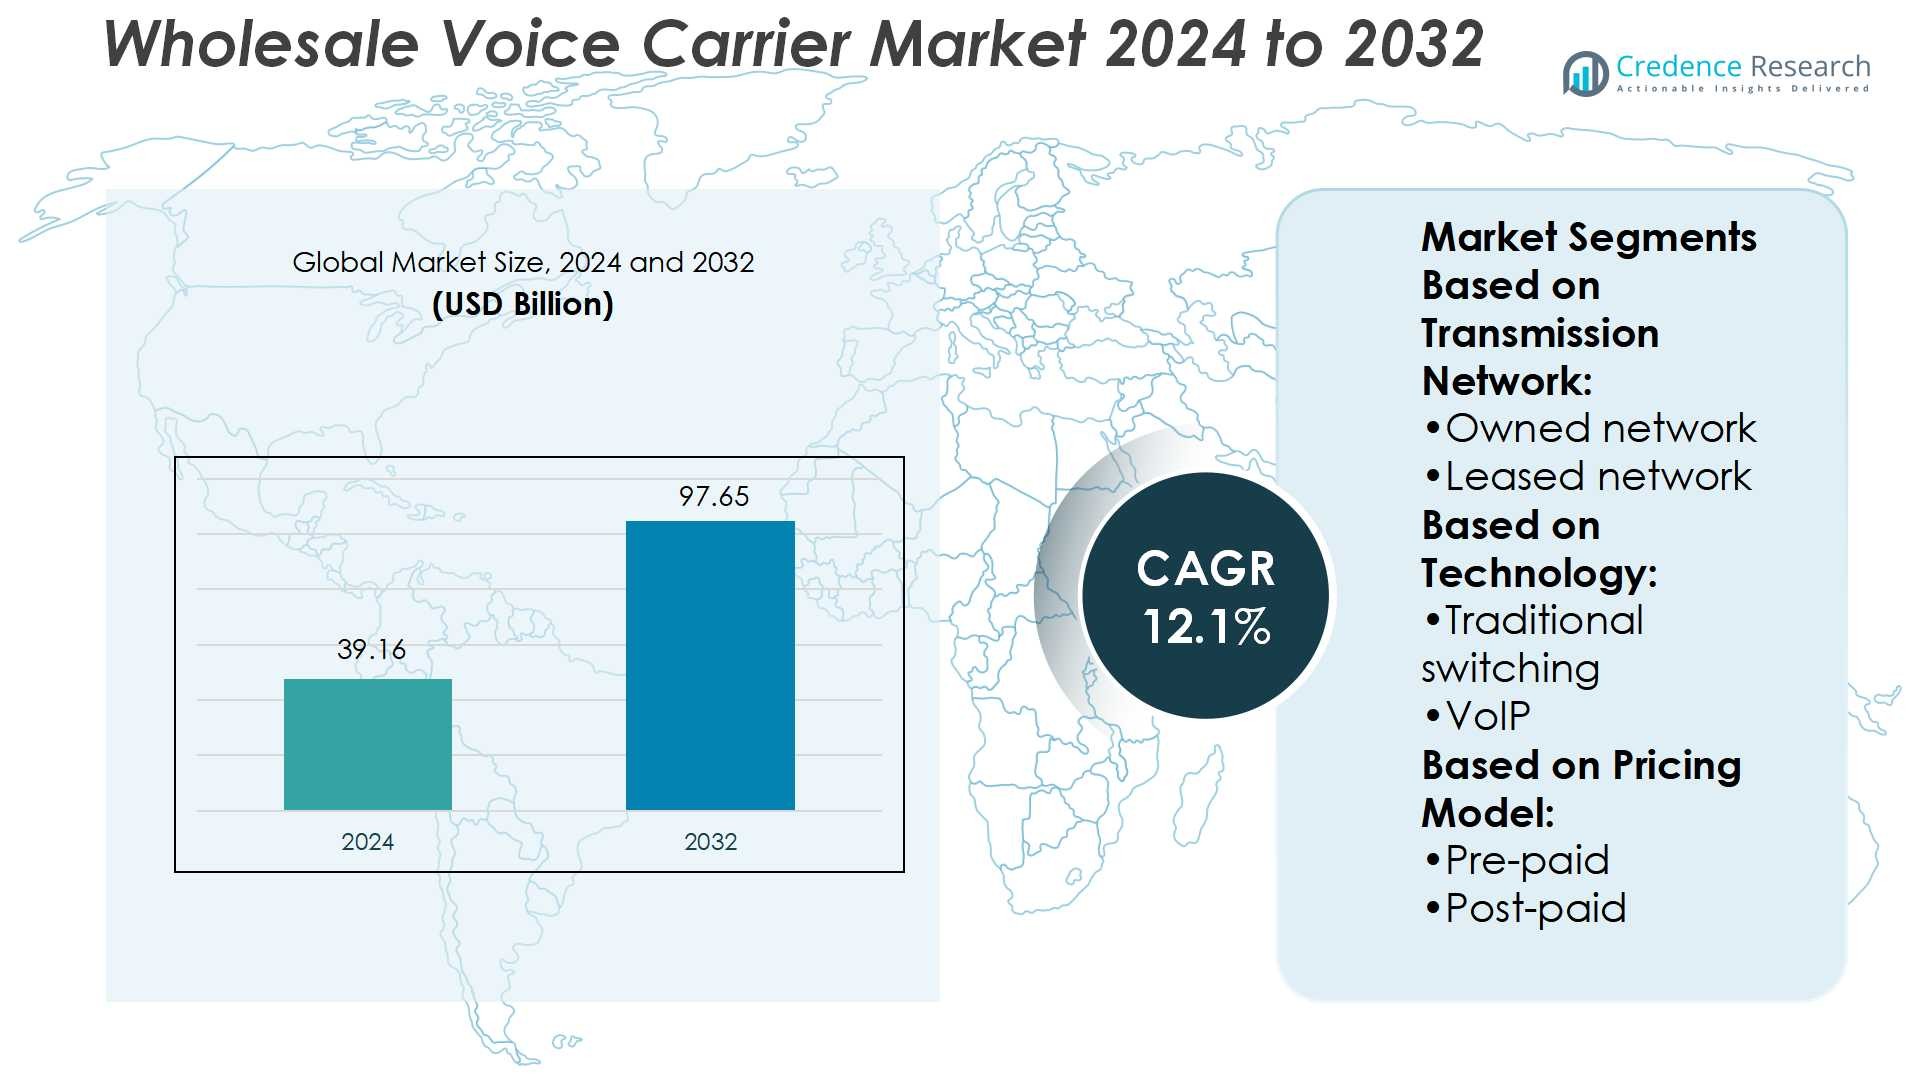
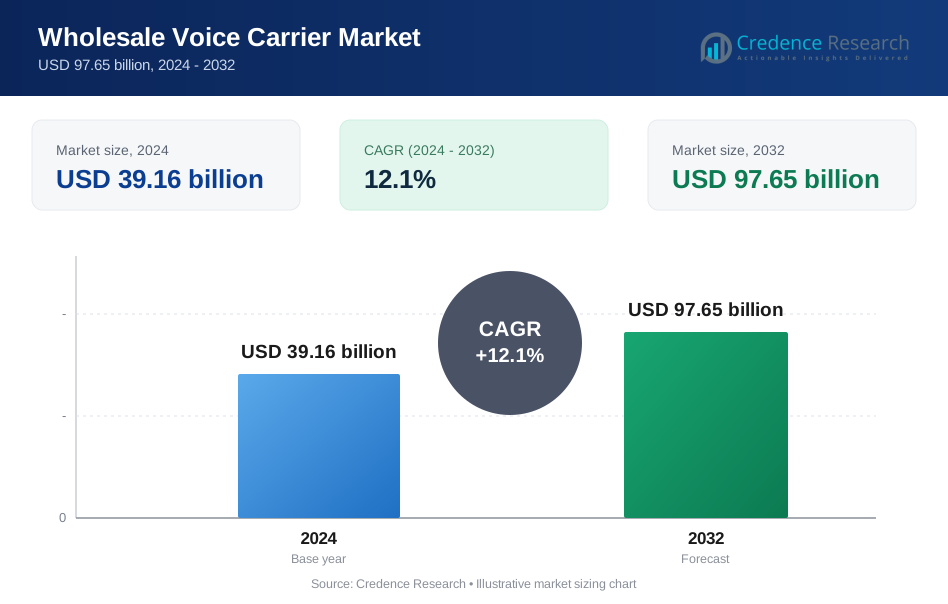
Wholesale Voice Carrier Market size was valued USD 39.16 billion in 2024 and is anticipated to reach USD 97.65 billion by 2032, at a CAGR of 12.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wholesale Voice Carrier Market Size 2024 | USD 39.16 Billion |
| Wholesale Voice Carrier Market, CAGR | 12.1% |
| Wholesale Voice Carrier Market Size 2032 | USD 97.65 Billion |
The wholesale voice carrier market is driven by leading players such as Deutsche Telekom AG, Lumen Technologies, BT, Telstra, Verizon Partner Solutions, Orange, Tata Communications Limited, Cox Communications, IDT Global Services, and NTT Ltd. These companies leverage extensive global networks, advanced VoIP platforms, and cloud-based solutions to deliver secure and efficient communication services. North America leads the market with a 34% share, supported by advanced telecom infrastructure, high enterprise adoption, and strong investments in fiber and 5G. The region’s dominance is reinforced by strategic partnerships, international route expansions, and growing demand for reliable cross-border voice connectivity.
Market Insights
- The wholesale voice carrier market was valued at USD 39.16 billion in 2024 and is projected to reach USD 97.65 billion by 2032, growing at a CAGR of 12.1%.
- Growth is driven by the rising adoption of VoIP and cloud-based solutions, which offer cost efficiency, scalability, and integration with enterprise communication systems.
- The competitive landscape features global players focusing on infrastructure expansion, fraud management, and partnerships to strengthen service quality and global coverage.
- Market restraints include declining profit margins due to pricing pressure, regulatory challenges, and increasing competition from OTT platforms offering low-cost alternatives.
- North America leads with a 34% share, supported by advanced telecom infrastructure and 5G adoption, while VoIP dominates the technology segment with a 67% share, reinforcing its position as the preferred communication model across regions.
Market Segmentation Analysis:
By Transmission Network
The owned network segment dominates the wholesale voice carrier market with a 61% share. Carriers with owned infrastructure benefit from higher reliability, lower latency, and greater control over service quality. These advantages attract enterprises and operators that prioritize consistent international connectivity. Investments in submarine cables and intercontinental fiber routes further strengthen this segment. Demand for secure and scalable connections continues to rise as global data and voice traffic grows, reinforcing the position of owned networks as the preferred choice for major carriers.
- For instance, Google is the primary investor and owner of the Dunant and Grace Hopper submarine cable systems. The Dunant cable, with a capacity of 250 terabits per second (Tbps), and the Grace Hopper cable, with a capacity of 352 Tbps, collectively add significant transatlantic capacity.
By Technology
VoIP leads the technology segment with a 67% share, surpassing traditional switching. This dominance is driven by cost efficiency, scalability, and support for advanced features such as real-time analytics and HD voice. Operators favor VoIP due to its compatibility with cloud communication platforms and seamless integration with enterprise systems. The adoption of 5G networks also enhances VoIP performance, reducing call drop rates and improving latency. These advantages ensure VoIP remains the preferred technology for both retail and wholesale carriers, supporting its strong market leadership.
- For instance, Lumen upgraded its VoIP service for the U.S. Department of Defense (DoD) to support over 250,000 concurrent voice connections through its voice cloud system, using cloud data centers certified at DoD Impact Level-5 for security.
By Pricing Model
The post-paid model accounts for 58% of the wholesale voice carrier market, making it the leading segment. Enterprises and telecom operators prefer post-paid agreements for predictable billing and transparent usage tracking. This model provides flexibility in handling large-scale international traffic, with discounts on higher volumes. Post-paid contracts also foster long-term relationships between carriers and clients, ensuring stable revenue streams. While pre-paid models appeal to smaller players and niche operators, post-paid remains dominant due to its alignment with enterprise-grade requirements and cross-border voice traffic management.
Key Growth Drivers
Rising International Voice Traffic
The wholesale voice carrier market benefits from the steady rise in international voice traffic. Growth in global trade, tourism, and cross-border migration drives higher demand for reliable international communication. Carriers expand coverage through owned and leased networks to meet this need. Enterprises, especially in financial services and logistics, require high-quality international voice services for operational efficiency. The increasing reliance on international connectivity for both consumer and enterprise use continues to strengthen the demand base for wholesale voice carriers worldwide.
- For instance, BT’s Global Voice solutions currently route over 320 million minutes per month on its SIP platform across more than 350 customers, hosting more than 4 million telephone numbers for those clients.
Adoption of VoIP and IP-Based Solutions
VoIP adoption is a major driver, as it reduces operational costs while offering scalability and flexibility. IP-based networks enable carriers to provide enhanced services like real-time analytics, call monitoring, and high-definition voice. Businesses prefer VoIP for its integration with cloud platforms and enterprise applications. The rollout of 5G networks further improves VoIP performance by lowering latency and increasing capacity. These advancements ensure strong migration from legacy switching systems to IP-based frameworks, positioning VoIP as a long-term growth driver in wholesale voice services.
- For instance, Telstra’s IP Telephony over ADSL limits concurrent calls per site to 3 calls and mandates a minimum of 512 kbps uplink and downlink speed to ensure quality. Each voice line requires a fraction of that bandwidth, typically around 100 kbps, depending on the codec.
Expansion of Telecom Infrastructure
Global investments in telecom infrastructure are fueling wholesale voice market growth. Carriers are deploying submarine cables, upgrading terrestrial fiber, and expanding points of presence in high-demand regions. These developments enhance coverage, capacity, and call quality across continents. Expanding digital economies in Asia Pacific, Africa, and Latin America further increase infrastructure demand. Operators leverage these advancements to serve international businesses and retail carriers with reliable services. Infrastructure growth ensures scalability for future demand while strengthening the competitive position of wholesale carriers in the global market.
Key Trends & Opportunities
Shift Toward Cloud-Based Voice Services
Carriers are rapidly transitioning to cloud-based voice platforms, enabling flexible and cost-effective service delivery. Cloud systems support advanced features such as unified communications, AI-driven call routing, and real-time data analytics. Enterprises increasingly adopt these services to enhance collaboration and reduce infrastructure costs. This trend opens opportunities for carriers to bundle voice with digital solutions, including collaboration and messaging platforms. Cloud integration not only modernizes operations but also positions wholesale carriers as strategic partners in the evolving digital communications landscape.
- For instance, Tata Communications carries 32 billion voice minutes every year via its carrier services, connecting through 1,600+ communications service provider relationships and interconnecting with 700+ mobile network operators.
Emergence of Wholesale Voice Aggregators
The rise of wholesale voice aggregators presents a strong opportunity for market players. Aggregators consolidate multiple carrier routes and provide optimized pricing, reliability, and quality to clients. This model attracts enterprises seeking cost-effective international communication without managing multiple vendor relationships. Carriers that partner with or acquire aggregators can broaden their service portfolios and reach new customer segments. The aggregator trend supports competitive differentiation, fosters operational efficiency, and creates growth opportunities in markets with diverse international voice demands.
- For instance, IDT Express, a division of IDT Corporation, is a wholesale voice carrier that terminates over 20 billion minutes annually. The company offers over 550 direct routes and more than 1,000 CLI-certified routes, relying on its extensive network to deliver reliable voice termination services.
Key Challenges
Declining Profit Margins
Profitability in the wholesale voice carrier market is challenged by price erosion and strong competition. The commoditization of voice services has led to reduced average revenue per minute. Additionally, regulatory pressure and interconnect rate reductions further compress margins. Carriers face difficulty sustaining profitability while maintaining service quality and infrastructure investment. To overcome this, players must diversify into value-added services such as fraud management, analytics, and unified communication. Margin pressure remains a persistent barrier to long-term growth and stability in the market.
Impact of Over-the-Top (OTT) Services
OTT platforms like WhatsApp, Skype, and Zoom significantly disrupt the wholesale voice carrier market. These applications bypass traditional carriers by offering free or low-cost international calling over data networks. As consumer and enterprise users increasingly adopt OTT services, wholesale carriers face declining voice traffic volumes. This substitution effect threatens revenue streams, particularly in high-margin international calling segments. Carriers must innovate by integrating voice with digital services, offering enterprise-grade security, and leveraging partnerships to remain relevant against the rapid growth of OTT alternatives.
Regional Analysis
North America
North America holds a 34% share of the wholesale voice carrier market, driven by advanced telecom infrastructure and high enterprise demand. The region benefits from strong investments in IP-based networks, data centers, and 5G rollouts. Enterprises in finance, healthcare, and logistics rely heavily on international voice connectivity, reinforcing carrier revenues. U.S. and Canadian operators lead with robust international routes, supported by partnerships with global carriers. Growth is further supported by the adoption of VoIP and cloud-based communication solutions. Regulatory compliance and fraud prevention initiatives also strengthen the region’s competitive edge in wholesale voice services.
Europe
Europe accounts for 28% of the wholesale voice carrier market, supported by extensive cross-border communication within the EU. The region’s carriers benefit from harmonized regulations, dense fiber connectivity, and strong demand from multinational corporations. Countries such as Germany, the UK, and France remain key contributors due to their strong enterprise ecosystems. The adoption of VoIP and cloud-based services accelerates digital transformation across industries. EU policies promoting fair interconnect rates create a balanced competitive environment. Europe’s strategic position as a hub between Asia, Africa, and the Americas enhances its importance in global wholesale voice operations.
Asia Pacific
Asia Pacific commands a 22% share of the wholesale voice carrier market, fueled by rapid telecom infrastructure growth and rising international traffic. The region is home to a large base of mobile subscribers and increasing demand for cross-border communication from expanding digital economies. China, India, and Southeast Asia drive growth with high adoption of VoIP and cloud-based voice services. Investments in submarine cables and 5G deployments strengthen capacity and call quality. Carriers benefit from partnerships with global players to expand coverage. Asia Pacific’s expanding digital ecosystem ensures sustained growth for wholesale voice services.
Latin America
Latin America holds an 8% share of the wholesale voice carrier market, with demand supported by growing cross-border trade and tourism. Brazil and Mexico dominate regional growth due to their large populations and expanding enterprise sectors. Carriers invest in fiber-optic networks and submarine cable connections to improve international call reliability. The adoption of VoIP and digital voice services is rising as businesses seek cost-effective communication tools. Regulatory reforms in telecom markets encourage competition and infrastructure development. Despite challenges like price sensitivity, Latin America shows steady potential for wholesale voice service expansion.
Middle East & Africa
The Middle East & Africa region contributes a 7% share to the wholesale voice carrier market, driven by increasing mobile penetration and growing demand for international connectivity. Key markets such as the UAE, South Africa, and Saudi Arabia lead with expanding telecom investments and strategic geographic positioning. Carriers in the region focus on enhancing international routes and deploying submarine cables to support rising traffic. The adoption of VoIP and digital solutions grows as enterprises modernize communication. Despite margin pressures and infrastructure gaps in some areas, the region remains a growth frontier for wholesale voice services.
Market Segmentations:
By Transmission Network:
- Owned network
- Leased network
By Technology:
- Traditional switching
- VoIP
By Pricing Model:
- Pre-paid
- Post-paid
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The competitive landscape of the wholesale voice carrier players such as Deutsche Telekom AG (Germany), Lumen Technologies (U.S.), BT (U.K.), Telstra (Australia), Verizon Partner Solutions (U.S.), Orange (France), Tata Communications Limited (India), Cox Communications, Inc. (U.S.), IDT Global Services (U.S.), and NTT Ltd. (U.S.). The wholesale voice carrier market is shaped by strong global networks, advanced technology adoption, and service innovation. Companies focus on expanding international routes, deploying VoIP platforms, and integrating cloud-based communication systems to enhance efficiency and reduce costs. The market is highly competitive, with carriers investing in submarine cables, fiber connectivity, and 5G infrastructure to strengthen scalability and call quality. Strategic partnerships and alliances play a key role in extending global coverage and addressing growing international traffic. Emphasis on fraud prevention, analytics, and enterprise-grade services ensures differentiation in this price-sensitive environment.
Key Player Analysis
- Deutsche Telekom AG (Germany)
- Lumen Technologies. (U.S.)
- BT (U.K.)
- Telstra (Australia)
- Verizon Partner Solutions (U.S.)
- Orange (France)
- Tata Communications Limited. (India)
- Cox Communications, Inc. (U.S.)
- IDT global Services (U.S.)
- NTT Ltd. (U.S.)
Recent Developments
- In February 2025, AT&T expanded its voice core partnership with Nokia through a multi-year deal focused on network security, automation, and Voice-over-New-Radio capabilities, including deployment of Nokia’s Digital Operations software for automated service delivery.
- In February 2025, Nokia, Vodafone, and RingCentral showcased Immersive Voice and Audio Services at MWC 2025, introducing three-dimensional sound experiences that enhance business communications through metadata-assisted spatial audio technology.
- In July 2024, New York-listed Greek bulker owner Diana Shippinsg acquired an extension for the time charter contract with Nippon Yusen Kabushiki Kaisha (NYK Line) for one of its newcastlemax vessels.
- In February 2024, 5g-KPN, the top telecom provider in the Netherlands, and iBASIS, a well-known global supplier of communications solutions for operators and digital players, extended their outsourcing contract for voice and mobile services for an extra three years.
Report Coverage
The research report offers an in-depth analysis based on Transmission Network, Technology, Pricing Model and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rising adoption of VoIP as enterprises shift from legacy systems.
- Cloud-based communication platforms will drive integration of voice with digital services.
- Expansion of submarine cables and fiber networks will strengthen international coverage.
- 5G rollouts will improve call quality, reduce latency, and support advanced voice solutions.
- Carriers will focus on value-added services such as fraud detection and analytics.
- Partnerships with digital service providers will expand customer reach and offerings.
- Pricing pressure will push operators toward efficiency and service diversification.
- Demand from emerging markets will grow with rising mobile and internet penetration.
- Enterprise demand for secure and reliable voice connectivity will remain strong.
- Consolidation and strategic alliances will reshape the competitive landscape globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising International Voice Traffic
Growth in global trade, tourism, and cross-border migration is increasing the need for reliable international voice communication. Enterprises and operators require robust international connectivity, driving demand for wholesale voice carrier services.
Adoption of VoIP and IP-Based Solutions
VoIP technology offers cost efficiency, scalability, and advanced features such as real-time analytics and HD voice, making it the preferred choice for carriers and enterprises. The shift from legacy systems to IP-based frameworks is accelerating market growth.
Expansion of Telecom Infrastructure
Investments in submarine cables, fiber networks, and 5G rollouts are enhancing global coverage, capacity, and call quality. This infrastructure expansion enables carriers to meet rising international traffic and support future demand.
Shift Toward Cloud-Based Voice Services
Carriers are adopting cloud-based platforms to deliver flexible, cost-effective, and feature-rich voice services. Cloud integration allows bundling of voice with digital solutions, appealing to enterprises seeking unified communications.
Emergence of Wholesale Voice Aggregators
Aggregators consolidate multiple carrier routes, offering optimized pricing and reliability to clients. This model attracts enterprises looking for cost-effective international communication and enables carriers to expand their service portfolios.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wholesale Voice Carrier Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wholesale Voice Carrier Market projected to grow between 2025 and 2032?
Which Wholesale Voice Carrier Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wholesale Voice Carrier Market?
Who are the leading companies in the Wholesale Voice Carrier Market?
Which region commanded the largest share of the Wholesale Voice Carrier Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Traditional switching
- 1.2.2 VoIP
- 1.3 By Pricing Model
- 1.3.1 Pre-paid
- 1.3.2 Post-paid
- 1.4 By Transmission Network
- 1.4.1 Owned network
- 1.4.2 Leased network
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 39.16 billion → 2032: USD 97.65 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wholesale Voice Carrier Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wholesale Voice Carrier Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wholesale Voice Carrier Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wholesale Voice Carrier Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wholesale Voice Carrier Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wholesale Voice Carrier Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wholesale Voice Carrier Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wholesale Voice Carrier Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 39.16 billion → 2032: USD 97.65 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wholesale Voice Carrier Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional switching
- 12.3.7.2 VoIP
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Pricing Model - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pre-paid
- 12.4.7.2 Post-paid
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Transmission Network - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Owned network
- 12.5.7.2 Leased network
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wholesale Voice Carrier Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Wholesale Voice Carrier Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Wholesale Voice Carrier Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Deutsche Telekom AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Lumen Technologies
- 17.4 BT
- 17.5 Telstra
- 17.6 Verizon Partner Solutions
- 17.7 Orange
- 17.8 Tata Communications Limited
- 17.9 Cox Communications
- 17.10 IDT Global Services
- 17.11 NTT Ltd.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

