
Market Overview
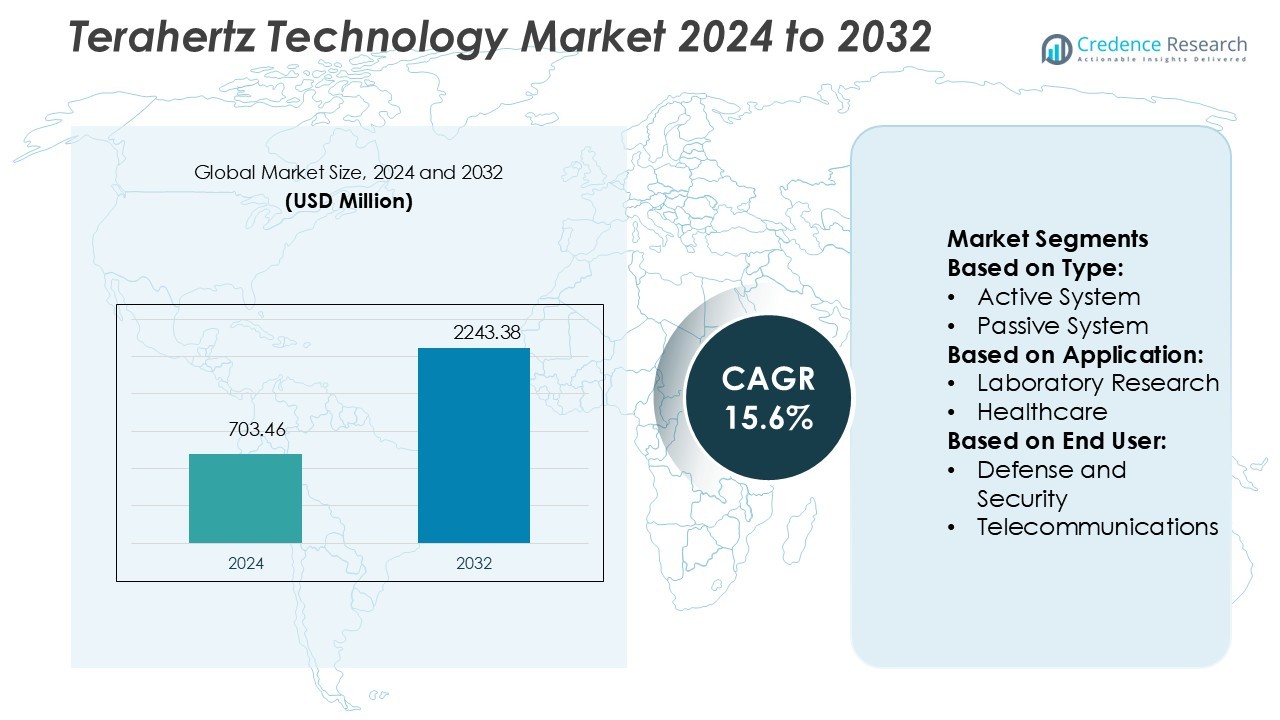
Terahertz Technology Market size was valued USD 703.46 million in 2024 and is anticipated to reach USD 2243.38 million by 2032, at a CAGR of 15.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Terahertz Technology Market Size 2024 | USD 703.46 Million |
| Terahertz Technology Market, CAGR | 15.6% |
| Terahertz Technology Market Size 2032 | USD 2243.38 Million |
The terahertz technology market is shaped by leading players including Advantest Corporation, Luna Innovations, HUBNER GmbH & Co. KG, TeraView Limited, Toptica Photonics AG, Gentec Electro-optics Inc., Bakman Technologies LLC, Menlo Systems, QMC Instruments Ltd., and TeraSense Group. These companies focus on advancing terahertz imaging, spectroscopy, and communication systems to serve healthcare, defense, industrial, and telecommunication applications. Strategic initiatives such as R&D investments, product miniaturization, and partnerships with research institutes strengthen their competitive positions. Regionally, North America leads the market with a 36% share, driven by strong adoption in healthcare diagnostics, defense screening, and 6G-related research programs, supported by government funding and advanced infrastructure.
Market Insights
- The Terahertz Technology Market was valued at USD 703.46 million in 2024 and will reach USD 2243.38 million by 2032, growing at a CAGR of 15.6%.
- Strong drivers include rising adoption in healthcare diagnostics, non-destructive industrial testing, and advanced defense screening systems.
- Key trends highlight growing demand for terahertz communication in 6G networks and increasing miniaturization of devices for commercial and industrial use.
- The market is highly competitive with players such as Advantest Corporation, Luna Innovations, HUBNER GmbH & Co. KG, TeraView Limited, Toptica Photonics AG, Gentec Electro-optics Inc., Bakman Technologies LLC, Menlo Systems, QMC Instruments Ltd., and TeraSense Group focusing on R&D and global collaborations.
- Regional analysis shows North America leading with a 36% share, followed by Europe at 28% and Asia-Pacific at 25%, while healthcare applications dominate with 34% share, reinforcing strong growth prospects across industries.
Market Segmentation Analysis:
By Type
The Terahertz Technology Market by type is dominated by Terahertz Imaging Systems, which hold the largest share at 46%. Within this, active systems lead due to their precision in real-time scanning and adaptability for industrial and healthcare uses. Passive systems remain relevant in defense and security for concealed object detection but are less adopted due to lower resolution. Terahertz Spectroscopy, divided into time-domain and frequency-domain methods, is gaining traction in research applications. Communication systems are emerging but currently hold a smaller share due to ongoing R&D and infrastructure limitations.
- For instance, QMC Instruments offers superconducting bolometer arrays with a spectral range from 100 GHz to 30 THz. These arrays operate around 4 K and offer a large linear dynamic range.
By Application
Healthcare applications dominate the market with a 34% share, driven by terahertz imaging’s ability to detect early-stage cancers and skin diseases without harmful radiation. Laboratory research remains strong, particularly in spectroscopy-based molecular analysis, accounting for a significant share. Industrial non-destructive testing (NDT) is growing, supported by rising adoption in aerospace and semiconductor inspection. Military and defense leverage terahertz systems for security screening, while satellite communication and wireless communication are expanding with growing demand for high-bandwidth data transfer. Other applications, including food inspection, are gaining momentum due to stringent safety regulations.
- For instance, Luna’s T-Ray 5600 THz system is an industrial-grade tool that measures multi-layer thickness and density in opaque materials. It is capable of detecting layers as thin as 50 µm and is used for non-invasive quality assurance in applications such as electric vehicle battery manufacturing.
By End User
Defense and security lead with a 38% share, supported by increasing global investments in advanced screening and surveillance systems. Telecommunications is expanding as terahertz communication systems promise ultra-high-speed data transfer for 6G networks. Industrial adoption is rising in electronics and aerospace sectors for defect detection and material inspection. Food and agriculture is growing steadily, using terahertz for contamination detection and quality assessment. Laboratories continue as essential end users for spectroscopy and imaging studies. Other users, including healthcare facilities and academic institutions, provide consistent demand, ensuring steady adoption across diverse industries.
Key Growth Drivers
Rising Demand in Healthcare Applications
Healthcare drives terahertz technology growth due to its non-invasive imaging capabilities. Terahertz systems detect cancers, skin diseases, and dental conditions without ionizing radiation, making them safer than traditional imaging. With healthcare expenditure rising globally and early diagnosis becoming a priority, adoption in hospitals and diagnostic centers is accelerating. Advancements in terahertz-based endoscopes and compact imaging devices strengthen this demand. The growing preference for precision diagnostics ensures healthcare will remain a primary growth engine for the terahertz technology market over the coming years.
- For instance, Menlo Systems offers the TERA Image automated imaging tool, which can be integrated into its THz time-domain spectroscopy systems. The tool scans sample areas of 150 mm × 150 mm and 300 mm × 300 mm, with spatial resolution better than 250 µm.
Expanding Role in Defense and Security
Defense and security agencies adopt terahertz technology for advanced screening and surveillance. Its ability to detect concealed weapons, explosives, and hazardous materials without harmful exposure makes it ideal for airports, border security, and military checkpoints. Governments worldwide are investing in modern security infrastructure, driving large-scale procurement of terahertz scanners. Rising global threats and cross-border tensions further push adoption. Continuous development of portable, high-resolution terahertz imaging devices ensures the segment remains a robust driver, fueling both domestic and international market expansion.
- For instance, TeraView’s TeraPulse 4000 benchtop unit offers a spectral range from 0.06 THz to 5 THz, with a dynamic range greater than 90 dB at peak, enabling detection of fine features in materials relevant to threat detection.
Growth in Industrial and Research Applications
Industrial sectors increasingly integrate terahertz systems for non-destructive testing (NDT), quality control, and semiconductor inspection. The technology’s ability to detect structural defects and material inconsistencies without damage makes it valuable in aerospace, automotive, and electronics. Simultaneously, laboratories and research institutes rely on terahertz spectroscopy for molecular analysis, drug discovery, and chemical characterization. Expanding investments in R&D across Asia-Pacific and Europe reinforce this adoption. With industries focusing on high precision and research centers demanding advanced tools, these applications significantly accelerate terahertz technology market growth.
Key Trends & Opportunities
Emergence of Terahertz Communication in 6G Networks
Terahertz frequencies are central to next-generation wireless communication. With 6G development underway, terahertz communication systems promise ultra-fast data rates, low latency, and enhanced bandwidth. Telecommunications providers and technology companies are actively investing in terahertz transceivers and antenna systems. This trend creates opportunities for equipment manufacturers and semiconductor companies to commercialize 6G-ready solutions. Growing demand for real-time data transmission in autonomous vehicles, IoT ecosystems, and satellite communication further highlights terahertz communication as a transformative market opportunity over the next decade.
- For instance, Gentec-EO’s T-RAD lock-in radiometers can be paired with various pyroelectric THz detector heads, including those with 5-mm or 9-mm apertures, which operate at room temperature.
Miniaturization and Commercialization of Terahertz Devices
Manufacturers are focusing on miniaturizing terahertz components to create portable, cost-effective devices. Advances in photonics and semiconductor fabrication enable smaller, more efficient terahertz imaging and spectroscopy systems. This trend accelerates adoption in medical diagnostics, food inspection, and industrial testing, where compact and user-friendly solutions are preferred. Commercial availability of handheld scanners and integration with AI-based analysis platforms open new opportunities for mass-market penetration. The shift from bulky laboratory equipment to commercially viable devices positions miniaturization as a key growth opportunity in the market.
- For instance, Bakman Technologies’ portable, turn-key frequency-domain THz spectrometers offer continuous frequency sweep capability from roughly 100 GHz up to 1.8 THz, with frequency resolution down to 100 MHz depending on the model.
Key Challenges
High Cost of Terahertz Systems
The cost of terahertz equipment remains a major barrier to widespread adoption. Advanced imaging and spectroscopy systems require expensive photonic and electronic components, making them unaffordable for small healthcare facilities, research labs, or industrial units. High installation and maintenance expenses further limit deployment. While large defense and government organizations can absorb these costs, commercial industries struggle with return-on-investment challenges. Unless production costs decline and affordable models emerge, market penetration in developing regions and small-scale applications will remain limited.
Technical Complexity and Limited Standardization
Terahertz technology requires complex system integration, precise calibration, and specialized expertise for operation. This technical complexity slows adoption outside of advanced research labs and defense agencies. Additionally, the market lacks standardized protocols for device performance, safety, and data interpretation. Inconsistent regulatory frameworks across regions further restrict commercialization. Without standardized benchmarks, interoperability and scalability of terahertz devices remain limited. Addressing these gaps through global standards and workforce training is crucial to unlock the full commercial potential of terahertz technology.
Regional Analysis
North America
North America dominates the terahertz technology market with a 36% share, supported by strong adoption across healthcare, defense, and industrial sectors. The U.S. leads with investments in non-invasive medical imaging, airport security screening, and R&D programs, while Canada strengthens growth through academic research and telecommunications development. Government funding and presence of leading companies accelerate commercialization. Expanding demand for high-speed communication technologies also drives 6G-related research. With well-established healthcare infrastructure and stringent security regulations, North America remains the largest revenue contributor and sets benchmarks in technological innovation and product deployment within the global terahertz technology landscape.
Europe
Europe holds a 28% share of the terahertz technology market, with robust applications in healthcare, security, and industrial non-destructive testing. Germany and the U.K. drive adoption through significant research investments in spectroscopy and imaging systems. The European Union’s strict food safety and product quality regulations foster demand for terahertz inspection solutions in agriculture and manufacturing. Defense modernization across France and Italy adds to market expansion. Collaborative research projects among universities, industries, and government bodies further strengthen regional leadership. Europe’s strong focus on sustainability, regulatory compliance, and advanced manufacturing ensures consistent adoption across diverse industries in the region.
Asia-Pacific
Asia-Pacific accounts for 25% of the terahertz technology market and emerges as the fastest-growing region with a 5.0% CAGR. China, Japan, and South Korea drive growth through large-scale R&D, semiconductor manufacturing, and healthcare adoption. Expanding investments in 6G communication trials significantly boost demand for terahertz communication systems. India’s rising healthcare spending and industrial growth create new opportunities for imaging and testing applications. Government support for defense modernization and food safety monitoring enhances adoption. The presence of leading electronics and telecommunication players, coupled with increasing commercialization efforts, positions Asia-Pacific as the key growth hub for the next decade.
Latin America
Latin America represents a 5.2% share of the terahertz technology market, driven mainly by healthcare diagnostics, food quality inspection, and emerging industrial applications. Brazil leads the region with investments in medical imaging technologies and industrial testing solutions, while Mexico follows with adoption in defense and communication research. The region faces challenges due to limited R&D infrastructure and high equipment costs, slowing large-scale adoption. However, strengthening food safety regulations and government initiatives to modernize healthcare infrastructure create opportunities. As industries and laboratories adopt compact and cost-effective systems, Latin America is expected to show steady growth in terahertz adoption.
Middle East & Africa
The Middle East & Africa region holds a 5.8% share in the terahertz technology market, with steady growth driven by investments in defense and security infrastructure. Countries like the UAE and Saudi Arabia are adopting terahertz-based scanning systems for border control and airport security. Industrial adoption is limited but growing in oil and gas inspection and petrochemical applications. Africa shows gradual uptake through academic research and healthcare projects. While high equipment costs restrict widespread deployment, increasing government funding for advanced technologies and strategic security initiatives will support gradual market expansion across the region in the coming years.
Market Segmentations:
By Type:
- Active System
- Passive System
By Application:
- Laboratory Research
- Healthcare
By End User:
- Defense and Security
- Telecommunications
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the terahertz technology market features prominent players such as QMC Instruments Ltd., Luna Innovations, Menlo Systems, TeraView Limited, Gentec Electro-optics Inc., Bakman Technologies LLC, HUBNER GmbH & Co. KG, TeraSense Group, Advantest Corporation, and Toptica Photonics AG. The competitive landscape of the terahertz technology market is defined by rapid innovation, strong research collaborations, and expanding commercialization efforts across industries. Companies are focusing on developing advanced imaging, spectroscopy, and communication systems that address healthcare diagnostics, defense security, industrial non-destructive testing, and emerging 6G communication demands. Strategic partnerships with research institutions and government agencies are accelerating product development and standardization. The market also witnesses rising emphasis on miniaturization, affordability, and integration with AI-driven analytics, enabling broader adoption across laboratories, hospitals, and industrial facilities. As demand increases globally, competition centers on technological differentiation, application-specific solutions, and regional expansion strategies.
Key Player Analysis
- QMC Instruments Ltd.
- Luna Innovations
- Menlo Systems
- TeraView Limited
- Gentec Electro-optics Inc.
- Bakman Technologies LLC
- HUBNER GmbH & Co. KG
- TeraSense Group
- Advantest Corporation
- Toptica Photonics AG
Recent Developments
- In July 2024, US-based wellness solution provider Viiva launched its Viiva Discovery Station (VDS) in India, introducing terahertz technology to the market. Terahertz technology is widely used for detecting defects in tablet coatings, product inspection in various industries, material characterization in physics, identifying concealed weapons at airports, and detecting cancer and dental caries.
- In July 2024, TicWave Solutions GmbH announced the launch of their latest silicon-based terahertz product line, now available on their website. The new product categories include Terahertz Cameras, Terahertz Sources, and Terahertz Imaging Systems.
- In January 2024, Gentec Electro-Optics, a provider of laser beam and terahertz technology, launched a new PRONTO-250-FLEX laser power meter. It has flexible calibration options, allowing customers to pay only for the services they avail.
- In December 2023, TeraView Limited hosted a delegation from Malaysia at its headquarters in the UK. The visit is expected to pave the way for future partnerships & opportunities in applying terahertz technology. It aimed to explore potential collaborations between TeraView and critical stakeholders in Malaysia’s technology and research sectors.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with increasing adoption of terahertz imaging in healthcare diagnostics.
- Rising demand for advanced security screening will strengthen defense and homeland security applications.
- Industrial non-destructive testing will see higher uptake in aerospace, automotive, and semiconductor sectors.
- Terahertz communication will play a key role in the evolution of 6G networks.
- Miniaturization of terahertz devices will drive broader adoption across commercial and industrial sectors.
- Integration with AI and machine learning will enhance precision in spectroscopy and imaging.
- Food and agriculture industries will adopt terahertz systems for quality control and safety monitoring.
- Collaborative research between governments, academia, and private companies will accelerate innovation.
- Cost optimization and improved production efficiency will increase market penetration in developing regions.
- Standardization efforts and regulatory frameworks will support global commercialization and interoperability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Healthcare Applications
Terahertz technology enables non-invasive imaging for early detection of cancers, skin diseases, and dental conditions without harmful radiation, driving rapid adoption in hospitals and diagnostic centers as healthcare spending and focus on precision diagnostics increase globally.
Expanding Role in Defense and Security
Defense and security agencies are investing in terahertz-based screening systems for detecting concealed weapons and hazardous materials at airports and borders, fueled by global security concerns and government funding for advanced surveillance infrastructure.
Growth in Industrial and Research Applications
Industries such as aerospace, automotive, and electronics are integrating terahertz systems for non-destructive testing and quality control, while research institutes use terahertz spectroscopy for molecular analysis and drug discovery, supported by rising R&D investments.
Emergence of Terahertz Communication in 6G Networks
The development of 6G wireless networks is driving demand for terahertz communication systems, which offer ultra-fast data rates and low latency, prompting telecommunications providers and technology companies to invest in terahertz transceivers and related infrastructure.
Miniaturization and Commercialization of Terahertz Devices
Advances in photonics and semiconductor fabrication are enabling the production of compact, portable terahertz devices, making the technology more accessible for commercial, medical, and industrial applications and opening new market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Industrial Gases market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Terahertz Technology Market projected to grow between 2025 and 2032?
Which Terahertz Technology Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Terahertz Technology Market?
Who are the leading companies in the Terahertz Technology Market?
Which region commanded the largest share of the Terahertz Technology Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Active System
- 1.2.2 Passive System
- 1.2.3 Terahertz Spectroscopy
- 1.2.4 Terahertz Communication Systems
- 1.3 By End User
- 1.3.1 Defense and Security
- 1.3.2 Telecommunications
- 1.3.3 Industrial
- 1.3.4 Food and Agriculture
- 1.3.5 Laboratories
- 1.3.6 Healthcare Facilities
- 1.4 By Application
- 1.4.1 Healthcare
- 1.4.2 Laboratory Research
- 1.4.3 Industrial Non-Destructive Testing
- 1.4.4 Military and Defense
- 1.4.5 Wireless & Satellite Communication
- 1.4.6 Food Inspection
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 703.46 million → 2032: USD 2,243.38 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Terahertz Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Terahertz Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Terahertz Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Terahertz Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Terahertz Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Terahertz Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Terahertz Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Terahertz Technologies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 703.46 million → 2032: USD 2,243.38 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Terahertz Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Active System
- 12.3.7.2 Passive System
- 12.3.7.3 Terahertz Spectroscopy
- 12.3.7.4 Terahertz Communication Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Defense and Security
- 12.4.7.2 Telecommunications
- 12.4.7.3 Industrial
- 12.4.7.4 Food and Agriculture
- 12.4.7.5 Laboratories
- 12.4.7.6 Healthcare Facilities
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Healthcare
- 12.5.7.2 Laboratory Research
- 12.5.7.3 Industrial Non-Destructive Testing
- 12.5.7.4 Military and Defense
- 12.5.7.5 Wireless & Satellite Communication
- 12.5.7.6 Food Inspection
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Terahertz Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Terahertz Technologies Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Terahertz Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Terahertz Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Advantest Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Luna Innovations
- 18.4 HUBNER GmbH & Co. KG
- 18.5 TeraView Limited
- 18.6 Toptica Photonics AG
- 18.7 Gentec Electro-optics Inc.
- 18.8 Bakman Technologies LLC
- 18.9 Menlo Systems
- 18.10 QMC Instruments Ltd.
- 18.11 TeraSense Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

