
Market Overview
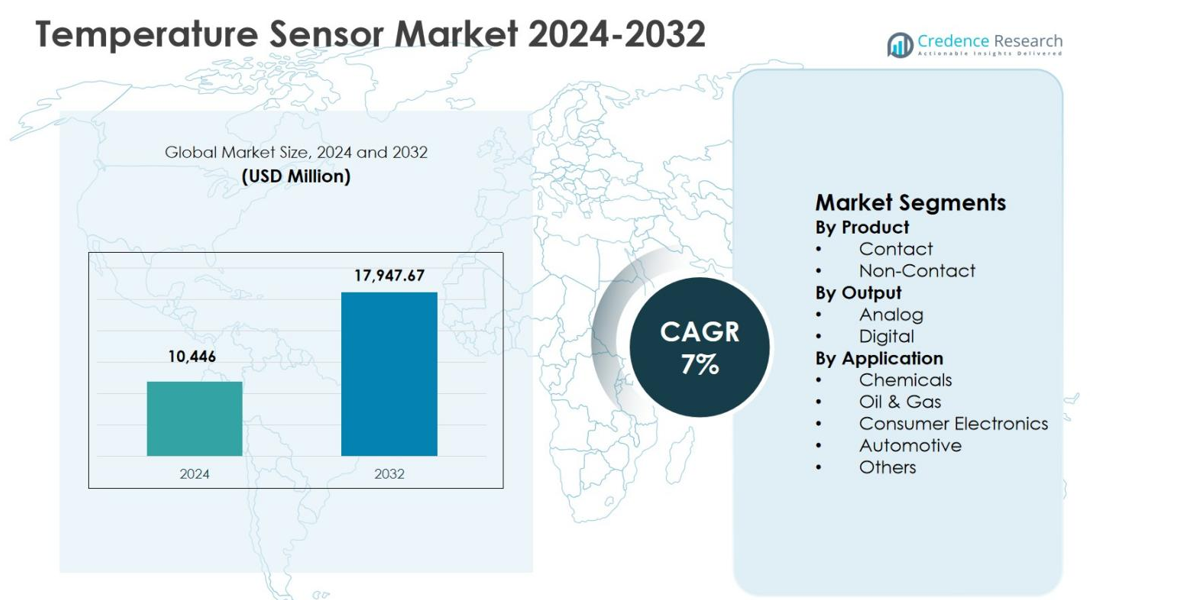
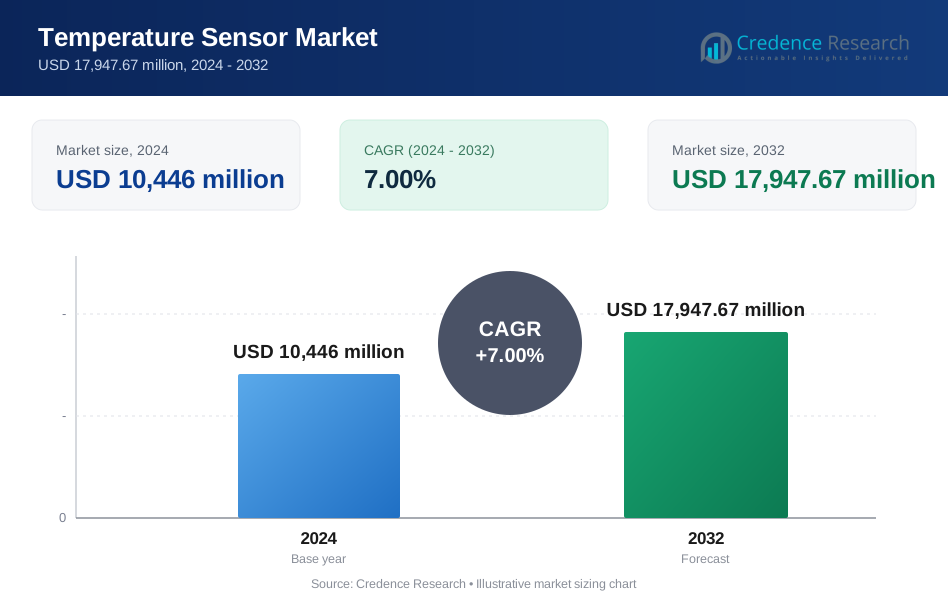
The Temperature Sensor Market size was valued at USD 10,446 million in 2024 and is anticipated to reach USD 17,947.67 million by 2032, growing at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Temperature Sensor Market Size 2024 | USD 10,446 million |
| Temperature Sensor Market, CAGR | 7% |
| Temperature Sensor Market Size 2032 | USD 17,947.67 million |
The Temperature Sensor Market is led by established global manufacturers such as NXP Semiconductors N.V., Analog Devices, Inc., Infineon Technologies AG, TE Connectivity Ltd., Amphenol Corporation, Microchip Technology Inc., ON Semiconductor Corporation, Sensirion AG, Emerson Electric Co., and Maxim Integrated Products, Inc., which drive innovation through advanced sensing technologies and diversified product portfolios. These companies focus on high-accuracy digital and non-contact sensors for automotive, industrial automation, and consumer electronics applications. Regionally, Asia Pacific dominated the Temperature Sensor Market with a 34.9% share in 2024, supported by large-scale electronics manufacturing, expanding automotive production, and strong semiconductor ecosystems. North America followed with a 31.8% share, driven by automation and electric vehicle adoption, while Europe accounted for 27.6%, supported by automotive and industrial demand.
Market Insights
- The Temperature Sensor Market was valued at USD 10,446 million in 2024 and is projected to reach USD 17,947.67 million by 2032, growing at a CAGR of 7% during the forecast period, supported by rising adoption across automotive, industrial, and electronics sectors.
- Market growth is primarily driven by automotive electrification and industrial automation, with the automotive application segment holding a 34.6% share in 2024, reflecting high sensor integration in battery management, power electronics, and thermal control systems.
- Key market trends include rapid adoption of digital sensing solutions, where digital temperature sensors accounted for 58.1% share in 2024, driven by IoT integration, real-time monitoring needs, and smart manufacturing expansion.
- Market restraint includes pricing pressure and product commoditization, especially in contact sensors, despite contact temperature sensors leading with a 62.4% share in 2024, limiting margin expansion for manufacturers.
- Regionally, Asia Pacific led with a 34.9% share in 2024, followed by North America at 31.8% and Europe at 27.6%, driven by electronics manufacturing, automotive production, and industrial modernization initiatives.
Market Segmentation Analysis:
By Product:
The Temperature Sensor Market, by product, is dominated by Contact temperature sensors, which accounted for 62.4% market share in 2024, owing to their high accuracy, reliability, and wide adoption across industrial and automotive applications. Contact sensors such as thermocouples and RTDs are extensively used in harsh and high-temperature environments, particularly in manufacturing, chemicals, and oil & gas operations. Their cost-effectiveness, long operational life, and compatibility with legacy systems further drive adoption. In contrast, non-contact sensors are gaining traction in specialized applications but currently hold a smaller share.
- For instance, Thermetrics Corporation deploys tube skin thermocouples in refining facilities worldwide to monitor temperatures in Coker units and Primary Reformers, using superior metallurgy for harsh petrochemical processes.
By Output:
Based on output, Digital temperature sensors held the dominant share of 58.1% in 2024 in the Temperature Sensor Market, supported by increasing demand for precise, real-time temperature monitoring and seamless integration with digital control systems. Digital sensors offer higher noise immunity, improved signal accuracy, and ease of integration with IoT-enabled devices and smart systems. These advantages make them highly preferred in automotive electronics, consumer devices, and industrial automation. Analog sensors maintain steady demand in cost-sensitive and legacy applications but face slower growth due to limited data processing capabilities.
- For instance, Sensirion's STS31-DIS offers ±0.2°C accuracy over 0°C to 90°C in a compact 2.5 x 2.5 mm DFN package, supporting battery-driven consumer applications like smart thermostats and wearables with 1.7 µA average current.
By Application:
Among applications, the Automotive segment led the Temperature Sensor Market with a 34.6% share in 2024, driven by rising vehicle electrification, stringent emission regulations, and growing adoption of advanced driver-assistance systems. Temperature sensors are critical for battery management systems, engine control units, exhaust monitoring, and cabin climate control. Increasing production of electric and hybrid vehicles significantly boosts sensor deployment per vehicle. Consumer electronics and oil & gas applications also contribute steadily; however, automotive remains dominant due to high-volume production and continuous technological integration.
Key Growth Drivers
Expanding Automotive Electrification
The rapid growth of electric and hybrid vehicles is a major driver for the Temperature Sensor Market. Modern vehicles rely on multiple temperature sensors to monitor batteries, power electronics, motors, and thermal management systems. Stringent emission regulations and vehicle safety standards further increase sensor deployment in both internal combustion and electric vehicles. In addition, the rising adoption of advanced driver-assistance systems and onboard diagnostics increases the need for accurate temperature monitoring, supporting sustained demand across passenger and commercial automotive segments.
- For instance, SEMITEC delivered about 2 million water temperature sensors for EV battery coolant systems, enabling high-sensitivity detection of coolant temperature changes to enhance vehicle safety and thermal management.
Growth in Industrial Automation and Process Control
Rising automation across manufacturing, chemicals, oil & gas, and energy sectors is significantly driving the Temperature Sensor Market. Temperature sensors are essential for maintaining process stability, operational safety, and energy efficiency in automated environments. Increasing investments in Industry 4.0 and smart factory initiatives accelerate demand for sensors that enable continuous monitoring and real-time data feedback. The focus on reducing equipment downtime, improving product quality, and meeting regulatory compliance requirements further strengthens market growth.
- For instance, Johnson Controls developed temperature sensors for HVAC systems that optimize heating and cooling. These sensors help buildings cut energy consumption by up to 30% through precise control in energy-intensive facilities.
Increasing Demand from Consumer Electronics
The expanding consumer electronics sector is a key growth driver for the Temperature Sensor Market. Devices such as smartphones, laptops, wearables, and smart home products increasingly incorporate temperature sensors for thermal protection and performance optimization. Ongoing miniaturization and higher functionality of electronic devices have increased sensor integration per unit. Rising consumer demand for connected and high-performance electronics, particularly in emerging economies, continues to support steady growth in this segment.
Key Trends & Opportunities
Integration with IoT and Smart Monitoring Systems
The integration of temperature sensors with IoT and smart monitoring platforms represents a major trend and opportunity in the Temperature Sensor Market. Connected sensors enable real-time data collection, predictive maintenance, and remote system management across industrial, automotive, and building automation applications. This capability improves operational efficiency and reduces maintenance costs. Growing adoption of smart infrastructure and digitalized industrial processes creates strong demand for advanced digital sensors with wireless connectivity and data analytics capabilities.
- For instance, Odoo integrates IoT temperature and vibration sensors in car manufacturing plants to monitor machine performance, alerting teams to overheating or anomalies for proactive maintenance that reduces breakdowns and downtime.
Advancements in Non-Contact Temperature Sensing
Technological advancements in non-contact temperature sensing are creating new opportunities in the Temperature Sensor Market. Improvements in infrared sensing accuracy, response speed, and reliability are expanding usage across healthcare, consumer electronics, and industrial safety applications. Non-contact sensors enable temperature measurement in hazardous, moving, or sterile environments where traditional contact sensors are unsuitable. Increasing demand for touch-free and safety-oriented solutions further accelerates adoption of advanced non-contact sensing technologies.
- For instance, OMRON's ES1-N infrared thermosensor offers ±0.5°C reproducibility and 0.14-second (95%) response time for precise non-contact measurements from -50 to 500°C. The laser pointer variant enhances reliability in dynamic consumer applications like safety monitoring.
Key Challenges
Accuracy, Drift, and Calibration Issues
Ensuring long-term accuracy and calibration stability remains a key challenge in the Temperature Sensor Market. Sensors operating in extreme temperatures, high vibration, or corrosive conditions are susceptible to performance drift over time. Frequent calibration requirements increase operational costs and complexity, particularly in industrial and automotive applications. Inaccurate temperature readings can impact safety, efficiency, and regulatory compliance, compelling manufacturers to invest in advanced materials and robust sensor designs.
Pricing Pressure and Competitive Intensity
Pricing pressure driven by intense competition presents a significant challenge for the Temperature Sensor Market. The presence of numerous global and regional suppliers has increased product commoditization, especially for standard sensor types. Price sensitivity among end users limits margin expansion, while rapid technological evolution requires continuous investment in research and development. Balancing cost efficiency with innovation and product differentiation remains a persistent challenge for market participants.
Regional Analysis
North America
North America accounted for 31.8% market share in 2024 in the Temperature Sensor Market, driven by strong demand from automotive, aerospace, industrial automation, and healthcare sectors. The region benefits from early adoption of advanced sensing technologies and widespread integration of IoT-enabled monitoring systems. High investments in electric vehicle production and smart manufacturing further support market growth. The presence of leading sensor manufacturers and semiconductor companies enhances innovation and supply chain efficiency. Strict regulatory standards related to safety and energy efficiency also encourage continuous deployment of temperature sensors across critical applications.
Europe
Europe held a 27.6% market share in 2024 in the Temperature Sensor Market, supported by stringent environmental regulations and strong automotive and industrial bases. Countries such as Germany, France, and the United Kingdom drive demand through extensive use of sensors in automotive manufacturing, renewable energy systems, and industrial process control. The region’s focus on vehicle electrification, emission reduction, and factory automation accelerates sensor adoption. Additionally, robust research and development activities and the presence of established automotive OEMs and industrial equipment manufacturers strengthen regional market performance.
Asia Pacific
Asia Pacific dominated the Temperature Sensor Market with a 34.9% market share in 2024, led by rapid industrialization, expanding consumer electronics manufacturing, and growing automotive production. China, Japan, South Korea, and India are key contributors due to large-scale electronics manufacturing hubs and increasing adoption of electric vehicles. Rising investments in smart factories and infrastructure development further boost sensor demand. Cost-efficient manufacturing capabilities and a strong semiconductor ecosystem support high-volume production, making Asia Pacific the leading regional market for temperature sensors.
Latin America
Latin America captured a 3.8% market share in 2024 in the Temperature Sensor Market, driven by growing industrial activity and gradual expansion of the automotive and oil & gas sectors. Countries such as Brazil and Mexico are witnessing increased deployment of temperature sensors in manufacturing, energy, and process industries. Investments in industrial modernization and infrastructure development support steady market growth. Although adoption remains lower compared to developed regions, increasing regulatory focus on safety and efficiency is expected to strengthen demand for temperature sensors across key applications.
Middle East & Africa
The Middle East & Africa accounted for 1.9% market share in 2024 in the Temperature Sensor Market, supported by demand from oil & gas, energy, and industrial processing industries. Temperature sensors play a critical role in monitoring extreme operating conditions across refineries and power generation facilities. Growing investments in industrial diversification and infrastructure projects in Gulf countries further support adoption. While market size remains comparatively smaller, increasing focus on automation, energy efficiency, and operational safety continues to create growth opportunities across the region.
Market Segmentations:
By Product
- Contact
- Non-Contact
By Output
- Analog
- Digital
By Application
- Chemicals
- Oil & Gas
- Consumer Electronics
- Automotive
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
NXP Semiconductors N.V., Analog Devices, Inc., Infineon Technologies AG, TE Connectivity Ltd., Amphenol Corporation, Microchip Technology Inc., ON Semiconductor Corporation, Sensirion AG, Emerson Electric Co., and Maxim Integrated Products, Inc. form the core competitive structure of the Temperature Sensor Market. The market is characterized by strong competition driven by continuous product innovation, portfolio expansion, and strategic partnerships. Leading players focus on developing high-accuracy digital and non-contact temperature sensors tailored for automotive electrification, industrial automation, and consumer electronics applications. Investments in research and development remain central, particularly for enhancing sensor precision, miniaturization, and IoT compatibility. Companies are also strengthening their global presence through capacity expansions and collaborations with OEMs to secure long-term supply agreements. Additionally, competitive differentiation increasingly depends on reliability, compliance with stringent safety standards, and the ability to offer integrated sensing solutions, intensifying rivalry among established players and regional manufacturers alike.
Key Player Analysis
- Emerson Electric Co.
- Sensirion AG
- Infineon Technologies AG
- Amphenol Corporation
- Microchip Technology Inc.
- NXP Semiconductors N.V.
- TE Connectivity Ltd.
- Analog Devices, Inc.
- ON Semiconductor Corporation
- Maxim Integrated Products, Inc.
Recent Developments
- In October 2025, Industrial Control Solutions (ICS) completed the acquisition of Duro-Sense Corporation, expanding its capabilities in temperature measurement and industrial sensing solutions to enhance precision monitoring in aerospace and industrial applications.
- In November 2025, DwyerOmega acquired Consistec, a Brazilian manufacturer of temperature monitoring solutions, strengthening its portfolio and global presence in innovative sensing and control solutions.
- In June 2025, Sensirion also introduced new digital humidity and temperature sensors (SHT40-AD1P-R2 and SHT41-AD1P-R2) to broaden its portfolio for precise environmental sensing.
- In July 2025, COTEMP Sensing acquired LPG Industries Inc. to expand its high-performance temperature measurement solutions for power generation
Report Coverage
The research report offers an in-depth analysis based on Product, Output, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Temperature Sensor Market will continue to expand due to increasing adoption in automotive electrification and advanced thermal management systems.
- Growing implementation of Industry 4.0 and smart manufacturing will sustain long-term demand for accurate temperature monitoring solutions.
- Integration of temperature sensors with IoT platforms will enhance real-time monitoring, predictive maintenance, and operational efficiency.
- Demand for digital temperature sensors will rise as industries shift toward connected and data-driven control systems.
- Non-contact temperature sensing technologies will gain wider adoption in safety-critical and high-speed industrial applications.
- Consumer electronics innovation will drive higher sensor integration per device to support performance optimization and thermal protection.
- Advancements in sensor miniaturization will enable broader use in compact and portable electronic devices.
- Regulatory emphasis on safety, emissions, and energy efficiency will reinforce sensor deployment across multiple industries.
- Emerging economies will offer growth opportunities due to industrial expansion and infrastructure development.
- Competitive intensity will encourage continuous innovation, cost optimization, and strategic collaborations among market participants.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Temperature Sensor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Temperature Sensor Market projected to grow between 2024 and 2032?
What are the key factors driving the growth of the temperature sensor market?
How does accuracy impact the selection of temperature sensors?
What are the emerging trends in the temperature sensor market?
Who are the leading companies in the Temperature Sensor Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Temperature Sensor Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Temperature Sensor Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10,446 million → 2032: USD 17,947.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Temperature Sensor Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Temperature Sensor Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Temperature Sensor Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Temperature Sensor Market Drivers
- 3.3 Temperature Sensor Market Restraints & Challenges
- 3.4 Temperature Sensor Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Temperature Sensor Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Temperature Sensor Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Temperature Sensor category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Temperature Sensor Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Temperature Sensor Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Temperature Sensor market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Temperature Sensor Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Temperature Sensor Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Temperature Sensor Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Temperature Sensor (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Temperature Sensor Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Temperature Sensor Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Temperature Sensor Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Temperature Sensor Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Temperature Sensor Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Temperature Sensor Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Temperature Sensor Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Temperature Sensor Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Temperature Sensor Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
