
Radiation Hardened Electronics Market Overview:
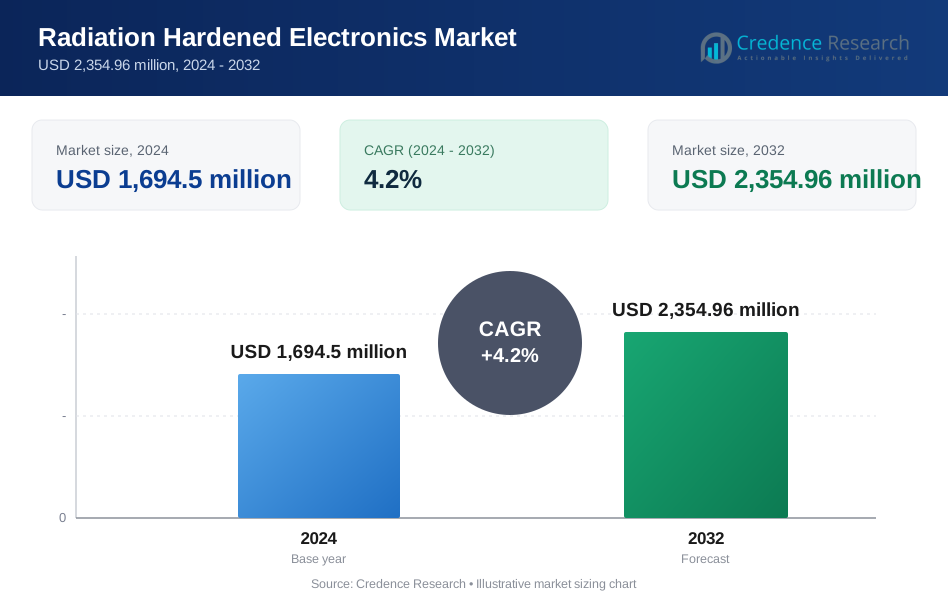
The Radiation Hardened Electronics Market size was valued at USD 1,694.5 million in 2024 and is anticipated to reach USD 2,354.96 million by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Radiation Hardened Electronics Market Size 2024 | USD 1,694.5 million |
| Radiation Hardened Electronics Market, CAGR | 4.2% |
| Radiation Hardened Electronics Market Size 2032 | USD 2,354.96 million |
The radiation-hardened electronics market is led by prominent players such as Honeywell International Inc., BAE Systems, Microchip Technology Inc., Infineon Technologies AG, and STMicroelectronics. These companies offer a diverse range of radiation-tolerant components for space, defense, and nuclear applications. Texas Instruments, Renesas Electronics, Teledyne Technologies, and TTM Technologies also contribute significantly, leveraging advanced design and manufacturing capabilities. North America remains the dominant regional market, holding over 40% share in 2024, driven by extensive defense funding, a mature space sector, and strong presence of key manufacturers. Europe and Asia Pacific follow, supported by growing space and military investments.

Radiation Hardened Electronics Market Insights
- The Radiation Hardened Electronics Market was valued at USD 1,694.5 million in 2024 and is projected to reach USD 2,354.96 million by 2032, growing at a CAGR of 4.2%.
- Growth is driven by increasing satellite launches, defense modernization, and demand for reliable electronics in high-radiation environments like space and nuclear plants.
- Key trends include miniaturization for CubeSats and the expansion of rad-hard electronics into medical and industrial sectors beyond traditional defense and space use.
- North America holds the largest regional share at over 40% due to strong military and space programs, followed by Europe at 25% and Asia Pacific at 20%; integrated circuits lead the component segment with a 35% share.
- High development costs, limited foundry access, and long qualification cycles pose challenges, especially for new market entrants and commercial-scale applications.
Radiation Hardened Electronics Market Segmentation Analysis:
By Component
Integrated Circuits dominate the radiation-hardened electronics market by component, accounting for over 35% of the share in 2024. These circuits form the backbone of mission-critical systems in space and defense sectors. Their demand is driven by increasing satellite deployments and deep-space missions that require radiation-tolerant performance. Memory devices follow closely, especially in space applications where data retention under radiation exposure is vital. Microcontrollers and microprocessors are gaining traction in avionics and nuclear systems for real-time control tasks. Power management components support voltage regulation and energy efficiency, while sensors and other modules cater to monitoring and diagnostics in harsh conditions.
- For instance, BAE Systems’ RAD750 processor demonstrates radiation tolerance up to 1 megarad total ionizing dose and has supported more than 200 space missions, including Mars rovers.
By Technique
Rad-Hard by Design (RHBD) holds the largest share among techniques, contributing approximately 48% of the market in 2024. This approach enables radiation tolerance at the circuit level without relying heavily on manufacturing processes. RHBD is favored for its cost-effectiveness and scalability in high-volume applications, particularly in defense electronics and commercial space systems. Rad-Hard by Process (RHBP) remains essential for highly critical applications that demand robust shielding, such as military-grade processors and space-grade ICs. Other techniques, including Rad-Hard by Shielding (RHBS), support legacy and hybrid systems, especially where design-level modifications are impractical.
- For instance, Infineon’s radiation-tolerant MOSFET designs achieve single-event burnout immunity above 60 MeV·cm²/mg through layout-level hardening.
By Application
Space is the dominant application segment, representing over 40% of the market in 2024. The rise in small satellite constellations, deep-space exploration programs, and communication satellite launches continues to drive demand for radiation-hardened components. Avionics and defense follow closely, driven by missile systems, unmanned aerial vehicles (UAVs), and secure communication platforms. Nuclear power plants utilize these electronics for safe operation and system diagnostics under extreme environments. The medical segment benefits from usage in radiation therapy equipment and imaging systems. Other applications, such as research labs and testing environments, account for niche but steady demand across global institutions.
Radiation Hardened Electronics Market Key Growth Drivers
Expanding Space Missions and Satellite Programs
The surge in global satellite launches and interplanetary missions fuels strong demand for radiation-hardened electronics. Spacecraft electronics must endure high radiation levels from cosmic rays and solar flares. Agencies like NASA, ESA, ISRO, and private firms such as SpaceX and Blue Origin increasingly rely on radiation-tolerant systems for mission reliability. The rising deployment of low Earth orbit (LEO) satellites for broadband internet and Earth observation adds further momentum. For example, mega-constellations like Starlink require thousands of radiation-hardened components to ensure uninterrupted function. Additionally, the Artemis program and Mars exploration missions emphasize robust electronics for extended space travel. These developments drive continuous innovation in radiation-resistant memory, processors, and power systems. The need for space-qualified parts with higher density, lower power consumption, and resistance to total ionizing dose (TID) and single-event effects (SEE) supports market expansion.
- For instance, NASA’s Mars Perseverance rover uses the BAE Systems RAD750 processor, qualified for 1 megarad total ionizing dose and validated against heavy-ion single-event effects.
Increased Defense Investments in Secure and Resilient Systems
Global defense budgets continue to rise, with a strong focus on advanced electronics that remain operational in nuclear and electromagnetic warfare environments. Militaries prioritize systems that can withstand intense radiation during missile operations, electronic warfare, and nuclear events. Radiation-hardened electronics play a vital role in aircraft avionics, navigation systems, missile guidance, radar, and secure communication. Countries like the U.S., China, Russia, and India heavily invest in hardened chips for battlefield reliability. For instance, the U.S. Department of Defense mandates radiation tolerance in strategic programs like nuclear command-and-control and missile defense networks. As defense digitization deepens, the need for hardened components extends to drones, autonomous systems, and next-gen combat platforms. This sustained procurement cycle and regulatory demand for secure electronics ensure a stable growth channel for rad-hard technology providers.
- For instance, Honeywell’s radiation-hardened space and defense processors withstand total ionizing doses above 1 megarad and support strategic command-and-control systems used by the U.S. Department of Defense.
Advancements in Semiconductor Manufacturing and Design Techniques
Technological progress in radiation-hardened design and manufacturing boosts performance while reducing costs and size. Foundries are adopting advanced CMOS process nodes to improve density and efficiency in rad-hard chips. Techniques such as silicon-on-insulator (SOI), error-correcting code (ECC), and triple modular redundancy (TMR) are becoming mainstream in radiation-tolerant designs. Companies now offer scalable solutions that balance cost, weight, and resistance benefiting commercial space and medical sectors. Foundry partnerships, like those between GlobalFoundries and defense primes, enable mass production of certified parts. The evolution of Rad-Hard by Design (RHBD) methods empowers developers to achieve radiation tolerance through layout-level modifications rather than expensive process changes. Additionally, open-source design ecosystems and EDA tools support innovation in smaller enterprises. These advancements enhance reliability, improve energy efficiency, and extend the life of devices deployed in hostile radiation environments.
Radiation Hardened Electronics Market Key Trends & Opportunities
Miniaturization of Radiation-Hardened Components for CubeSats and UAVs
There is a growing trend toward miniaturized rad-hard electronics to meet the needs of CubeSats, nanosatellites, and small UAV platforms. These systems demand lightweight, compact, and power-efficient components without compromising radiation tolerance. As CubeSats become more functional with capabilities ranging from Earth imaging to communications their need for reliable rad-hard microcontrollers, memory, and sensors increases. Manufacturers are shrinking form factors while integrating more features on single chips. Companies like BAE Systems and Microchip offer space-grade components optimized for size, weight, and power (SWaP) constraints. Additionally, small satellite missions are expanding into deep space, requiring better shielding and higher fault tolerance. This shift creates opportunities for specialized suppliers and fosters innovations in modular, plug-and-play rad-hard solutions for compact platforms across civil, military, and academic domains.
- For instance, Microchip’s SAMRH71 radiation-hardened microcontroller integrates an Arm Cortex-M7 core running at 100 MHz and withstands total ionizing dose levels up to 100 krad, supporting compact satellite avionics.
Commercialization of Rad-Hard Electronics Beyond Traditional Markets
The use of radiation-hardened electronics is expanding beyond space and defense into medical, nuclear energy, and industrial test environments. For instance, in oncology, radiation therapy machines require robust sensors and controllers to operate under high-radiation exposure. Similarly, nuclear reactors and fuel processing plants deploy hardened control systems to ensure safety and uninterrupted operations. In industrial automation, test and measurement devices used in particle accelerators and research labs are adopting radiation-tolerant designs. This broader adoption is supported by improved cost-efficiency of Rad-Hard by Design (RHBD) and off-the-shelf availability of qualified parts. The medical and energy sectors increasingly seek components that offer long-term reliability, diagnostics capability, and compliance with radiation safety standards. This diversification opens new revenue streams and encourages cross-sector partnerships to develop sector-specific, application-hardened solutions.
Radiation Hardened Electronics Market Key Challenges
High Development Costs and Qualification Barriers
Radiation-hardened electronics are costly to develop, manufacture, and certify. Extensive testing under ionizing environments, long qualification cycles, and strict reliability benchmarks raise production overheads. For small and medium-sized companies, entering the market requires large upfront investment in R&D, tools, and testing facilities. Even minor design iterations must undergo exhaustive radiation validation slowing time-to-market and increasing cost per unit. Aerospace and defense customers demand legacy compatibility, further limiting design flexibility. Additionally, compliance with standards such as MIL-STD-883 or ESA’s ESCC adds complexity to the product lifecycle. As a result, product pricing remains high, limiting adoption in cost-sensitive commercial applications. Market players must balance technical performance with affordability while maintaining long-term supply assurance.
Limited Foundry Access and Supply Chain Bottlenecks
Access to radiation-hardened semiconductor foundries remains constrained, with few global facilities offering certified manufacturing lines. Foundries prioritize high-volume commercial customers, leaving limited capacity for niche rad-hard production. Moreover, geopolitical tensions and export restrictions affect global sourcing, especially for defense-related contracts. The supply chain for specialty substrates like SOI wafers and shielding materials is narrow and vulnerable to disruption. Lead times for qualified components often extend several months, delaying integration into mission-critical systems. Inconsistent availability impacts program timelines in aerospace, defense, and nuclear sectors. To overcome this, OEMs and governments are investing in localized production and multi-sourcing strategies-but full supply chain resilience remains a challenge in the near term.
Radiation Hardened Electronics Market Regional Analysis
North America
North America holds the largest share in the radiation-hardened electronics market, accounting for over 40% in 2024. The region benefits from robust investments in defense, aerospace, and space exploration. Agencies like NASA and the U.S. Department of Defense heavily rely on radiation-hardened systems for satellites, missile defense, and nuclear applications. Major players such as Honeywell, BAE Systems, and Microchip Technology lead product innovation and supply. Increasing satellite launches under commercial and government programs further boost demand. Continued funding for modernizing military platforms and expanding space missions sustains North America's dominance in both design and end-use adoption.
Europe
Europe captures approximately 25% of the global market share in 2024, driven by active participation in space and defense initiatives. The European Space Agency (ESA) and national defense agencies support rad-hard electronics deployment in navigation, reconnaissance, and Earth observation satellites. Countries like France, Germany, and the U.K. lead the demand through aerospace firms such as Airbus and Thales. European regulations emphasize component reliability and long-term sustainability in critical missions. Growing R&D in radiation-hardened CMOS and cooperation between public and private sectors strengthen regional capabilities. The focus on autonomous systems and defense resilience supports steady market expansion across Europe.
Asia Pacific
Asia Pacific holds nearly 20% of the radiation-hardened electronics market share in 2024 and is the fastest-growing region. Rapid expansion of space programs in China, India, and Japan drives demand for radiation-tolerant systems in satellites and launch vehicles. China's BeiDou and India’s Gaganyaan missions increase procurement of domestic rad-hard components. Defense modernization, particularly in missile systems and UAVs, further accelerates adoption. Regional players are investing in in-house design capabilities and collaborating with global suppliers. Rising semiconductor manufacturing infrastructure and favorable government policies enhance regional production. Asia Pacific is poised for strong growth due to increasing strategic autonomy and space ambitions.
Latin America
Latin America accounts for a small share of around 5% in the global market in 2024 but shows gradual progress. Countries like Brazil and Argentina are developing limited satellite capabilities for communication and surveillance. While the region lacks large-scale defense or nuclear programs, investments in space research and scientific missions create niche opportunities. Regional universities and research institutes collaborate with international space agencies, driving limited demand for rad-hard components. Import dependency remains high, with limited local manufacturing capacity. However, growing awareness of space-based applications may lead to future government initiatives that could expand market participation.
Middle East & Africa (MEA)
The Middle East & Africa region contributes roughly 3% to the global radiation-hardened electronics market in 2024. The demand is primarily driven by defense modernization in countries like Israel, the UAE, and Saudi Arabia. These nations invest in advanced missile systems and secure communication technologies that rely on rad-hard components. Space-related developments are emerging, with the UAE’s Mars mission and growing satellite capabilities drawing attention to radiation-resilient electronics. However, limited domestic manufacturing and reliance on imports constrain broader growth. As regional security and space ambitions rise, MEA is expected to see steady but low-scale adoption in niche segments.
Radiation Hardened Electronics Market Segmentations:
By Component
- Integrated Circuits
- Memory
- Microcontrollers and Microprocessors
- Power Management
- Others (Sensors, etc.)
By Technique
- Rad-Hard by Design (RHBD)
- Rad-Hard by Process (RHBP)
- Others (Rad-Hard by Shielding (RHBS), etc.)
By Application
- Space
- Avionics & Defense
- Nuclear Power Plants
- Medical
- Others (Research & Institutes, Test & Measurement, etc.)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The radiation-hardened electronics market features a mix of established defense contractors, semiconductor giants, and specialized solution providers. Key players such as Honeywell International Inc., BAE Systems, and Microchip Technology Inc. lead the market with a broad portfolio of radiation-tolerant components used in satellites, defense systems, and nuclear applications. Infineon Technologies AG and STMicroelectronics focus on expanding rad-hard capabilities using advanced CMOS processes. Companies like Texas Instruments and Renesas Electronics offer reliable radiation-tolerant ICs for space and avionics. Teledyne Technologies and TTM Technologies support custom-built, high-reliability systems for mission-critical deployments. Competitive strategies include technology licensing, government partnerships, and investment in high-volume manufacturing for RHBD (Rad-Hard by Design) components. Emerging focus areas include miniaturization, AI integration in hardened systems, and dual-use components that meet both commercial and military standards. Ongoing R&D, government funding, and space program contracts continue to shape competitive positioning and innovation cycles across the market.
Key Player Analysis
- Advanced Micro Devices, Inc.
- BAE Systems
- Honeywell International Inc.
- Infineon Technologies AG
- Microchip Technology Inc.
- Renesas Electronics Corporation
- STMicroelectronics
- Teledyne Technologies Incorporated
- Texas Instruments Incorporated
- TTM Technologies Inc.
Recent Developments
- In August 2024, Moog introduced a radiation-hardened space computer designed to enhance high-speed computing capabilities for future space missions. This advanced system aims to support the next generation of space technology by ensuring reliable performance in harsh space environments.
- In June 2024, Infineon launched the radiation-hardened 1 and 2 Mb parallel interface ferroelectric RAM (F-RAM) devices designed for space applications. These non-volatile memory solutions provide high endurance, fast random access, and exceptional radiation resistance, making them ideal for satellites and space instruments requiring robust data storage and reliability in extreme environments.
- In November 2023, Infineon Technologies AG announced the expansion of its radiation-hardened asynchronous static RAMs range with built-in Error Correction Code (ECC) memory for space and other challenging environments.
Report Coverage
The research report offers an in-depth analysis based on Component, Technique, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Satellite mega-constellations will drive strong demand for compact radiation-hardened components.
- Defense sector will continue to invest in rad-hard systems for next-gen missiles and UAVs.
- Miniaturized rad-hard electronics will gain adoption in CubeSats and nanosatellite platforms.
- Medical equipment using radiation exposure will increasingly adopt hardened electronics for safety.
- Nuclear power plant upgrades will expand the use of reliable radiation-tolerant control systems.
- Asia Pacific will emerge as the fastest-growing region due to rising space and defense programs.
- Rad-Hard by Design techniques will gain preference for cost-effective product development.
- Public-private partnerships will boost domestic production and reduce reliance on imports.
- Semiconductor advances will improve performance, energy efficiency, and integration levels.
- Limited foundry access and long qualification cycles will remain key barriers to scalability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Space Missions and Satellite Programs
The surge in global satellite launches, including mega-constellations and deep-space missions, is fueling demand for radiation-hardened electronics that can withstand cosmic rays and solar flares. Agencies and private firms require robust, reliable components for mission-critical space applications, driving continuous innovation and market growth.
Increased Defense Investments in Secure and Resilient Systems
Rising global defense budgets and modernization efforts are boosting the adoption of radiation-hardened electronics in avionics, missile systems, and secure communications. Military programs mandate radiation tolerance for operational reliability in nuclear and electromagnetic warfare environments, ensuring steady procurement and market expansion.
Advancements in Semiconductor Manufacturing and Design Techniques
Technological progress in radiation-hardened design, such as advanced CMOS nodes, SOI, and Rad-Hard by Design (RHBD) methods, is improving performance, reducing costs, and enabling miniaturization. These advancements make rad-hard electronics more accessible for commercial space, medical, and industrial applications.
Miniaturization for CubeSats and UAVs
The trend toward smaller, lighter, and more power-efficient radiation-hardened components is driven by the proliferation of CubeSats, nanosatellites, and UAVs. Miniaturized rad-hard electronics enable new mission profiles and expand the addressable market for suppliers.
Commercialization Beyond Traditional Markets
Radiation-hardened electronics are increasingly being adopted in medical equipment, nuclear power plants, and industrial test environments. This diversification beyond space and defense is opening new revenue streams and supporting broader market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Radiation Hardened Electronics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Radiation Hardened Electronics Market projected to grow between 2024 and 2032?
Which Radiation Hardened Electronics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Radiation Hardened Electronics Market?
Who are the leading companies in the Radiation Hardened Electronics Market?
Which region commanded the largest share of the Radiation Hardened Electronics Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Integrated Circuits
- 1.2.2 Memory
- 1.2.3 Microcontrollers and Microprocessors
- 1.2.4 Power Management
- 1.2.5 Others (Sensors, etc.)
- 1.3 By Technique
- 1.3.1 Rad-Hard by Design (RHBD)
- 1.3.2 Rad-Hard by Process (RHBP)
- 1.3.3 Others (Rad-Hard by Shielding (RHBS), etc.)
- 1.4 By Application
- 1.4.1 Space
- 1.4.2 Avionics & Defense
- 1.4.3 Nuclear Power Plants
- 1.4.4 Medical
- 1.4.5 Others (Research & Institutes, Test & Measurement, etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,694.5 million → 2032: USD 2,354.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Radiation Hardened Electronics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Radiation Hardened Electronics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Radiation Hardened Electronics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Radiation Hardened Electronics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Radiation Hardened Electronics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Radiation Hardened Electronics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Radiation Hardened Electronics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Radiation Hardened Electronics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,694.5 million → 2032: USD 2,354.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Radiation Hardened Electronics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Integrated Circuits
- 12.3.7.2 Memory
- 12.3.7.3 Microcontrollers and Microprocessors
- 12.3.7.4 Power Management
- 12.3.7.5 Others (Sensors, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technique - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rad-Hard by Design (RHBD)
- 12.4.7.2 Rad-Hard by Process (RHBP)
- 12.4.7.3 Others (Rad-Hard by Shielding (RHBS), etc.)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Space
- 12.5.7.2 Avionics & Defense
- 12.5.7.3 Nuclear Power Plants
- 12.5.7.4 Medical
- 12.5.7.5 Others (Research & Institutes, Test & Measurement, etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Radiation Hardened Electronics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Radiation Hardened Electronics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Radiation Hardened Electronics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Radiation Hardened Electronics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BAE Systems
- 18.4 Microchip Technology Inc.
- 18.5 Infineon Technologies AG
- 18.6 STMicroelectronics
- 18.7 Texas Instruments Incorporated
- 18.8 Renesas Electronics Corporation
- 18.9 Teledyne Technologies Incorporated
- 18.10 TTM Technologies Inc.
- 18.11 Advanced Micro Devices, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

