
Residual Current Circuit Breaker (RCCB) Market Overview:
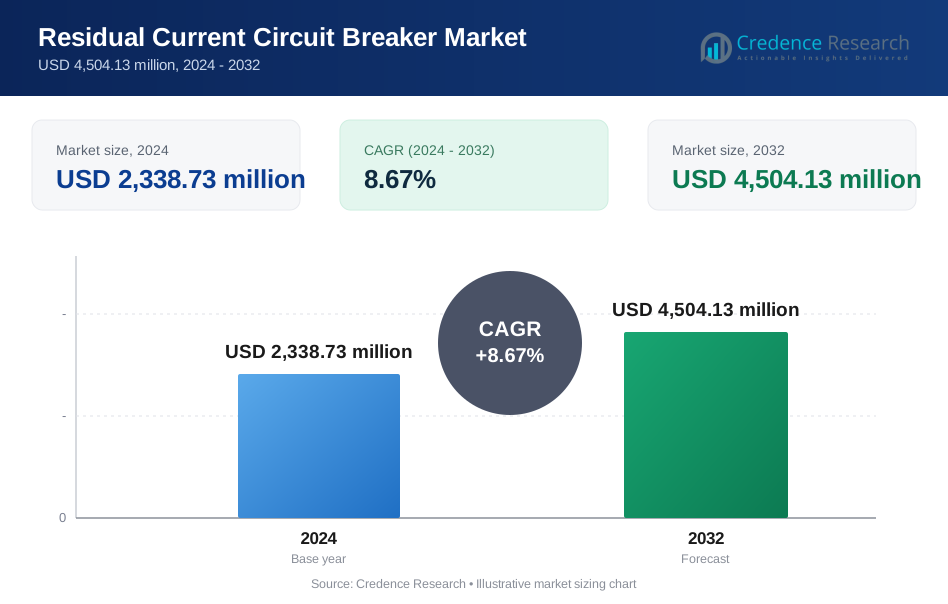
The Residual Current Circuit Breaker (RCCB) Market size was valued at USD 1,800.00 million in 2018, reached USD 2,338.73 million in 2024, and is anticipated to reach USD 4,504.13 million by 2032, at a CAGR of 8.67% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Residual Current Circuit Breaker (RCCB) Market Size 2024 | USD 12525 million |
| Residual Current Circuit Breaker (RCCB) Market, CAGR | 5.7% |
| Residual Current Circuit Breaker (RCCB) Market Size 2032 | USD 19515 million |
The Residual Current Circuit Breaker market is led by major players such as Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation, and Legrand. These companies dominate through broad product portfolios, strong R&D capabilities, and global distribution networks. Schneider Electric holds a prominent position with advanced smart RCCB solutions, while Siemens and ABB focus on industrial-grade innovations. Eaton and Legrand maintain strength in residential and commercial segments. Regionally, Asia Pacific leads the global market with a 43.9% share in 2024, driven by rapid urbanization, infrastructure expansion, and regulatory mandates across China, India, and Southeast Asia. North America follows with a 24.4% share, supported by stringent electrical safety standards and adoption of intelligent building systems. Europe ranks third, holding 20.3%, driven by strong compliance frameworks and retrofit demand. The competitive landscape remains innovation-driven, with regional players focusing on cost-effective solutions to expand presence in price-sensitive markets.

Residual Current Circuit Breaker (RCCB) Market Insights
- The Residual Current Circuit Breaker market was valued at USD 2,338.73 million in 2024 and is projected to reach USD 4,504.13 million by 2032, growing at a CAGR of 8.67%.
- Rising demand for electrical safety, regulatory compliance, and infrastructure development is driving adoption across residential and industrial sectors.
- Smart RCCBs with IoT integration and remote diagnostics are gaining popularity, especially in smart homes and industrial automation.
- Key players like Schneider Electric, Siemens AG, ABB, Eaton, and Legrand lead the market with wide portfolios and global presence, while price-sensitive regions attract low-cost regional competitors.
- Asia Pacific dominates with a 43.9% share in 2024, followed by North America at 24.4% and Europe at 20.3%; among segments, 30mA sensitivity and residential end-use lead due to widespread safety regulations and consumer awareness.
Residual Current Circuit Breaker (RCCB) Market Segmentation Analysis:
By Sensitivity
In the Residual Current Circuit Breaker market, the 30mA sensitivity segment holds the dominant market share due to its widespread use in residential and light commercial applications. This sensitivity level offers a balance between user safety and operational stability, making it ideal for general-purpose protection against electric shocks. The 10mA segment is gaining traction in high-risk environments such as healthcare and childcare facilities, driven by increasing safety standards. Higher ratings like 100mA and 300mA are preferred in industrial settings for equipment protection. The "Others" category includes customized solutions, supporting niche demands across specialized sectors.
- For instance, Schneider Electric offers Acti9 iID RCCBs rated at 10 mA and 30 mA with a conditional short-circuit current of 10 kA, designed to trip instantaneously (typically within 30–40 milliseconds) during earth leakage faults.
By End-user:
The residential sector leads the RCCB market, holding the highest revenue share, fueled by rapid urbanization, rising home electrical safety awareness, and regulatory enforcement. Growth in smart homes and renovation of aging infrastructure further drives residential installations. The commercial segment follows, supported by demand from office buildings, malls, and educational institutions where frequent human interaction demands enhanced safety. The industrial segment, though smaller in share, is growing steadily due to strict compliance needs in manufacturing and processing units, where electrical hazards and machinery protection are critical considerations.
- For instance, ABB supplies F200 series RCCBs widely used in residential and commercial buildings, supporting rated currents up to 63 A and sensitivity options from 30 mA to 300 mA for compliant electrical protection.
By Distribution Channel:
Offline distribution channels dominate the Residual Current Circuit Breaker market, accounting for the largest share, driven by well-established retail networks, electrical wholesalers, and contractor-based procurement practices. Installers and bulk buyers rely on physical product verification and technical consultation, which offline channels effectively provide. However, the online segment is growing rapidly, supported by increasing digital adoption, availability of a wide product range, and fast delivery. E-commerce platforms are favored by small contractors and DIY buyers seeking convenience and competitive pricing, especially in emerging economies with rising internet penetration.
Residual Current Circuit Breaker (RCCB) Market Key Growth Drivers
Rising Focus on Electrical Safety Regulations
Governments and regulatory bodies worldwide are tightening safety standards for residential, commercial, and industrial electrical systems. This push stems from rising incidents of electrical fires, shocks, and infrastructure damage. As a result, demand for reliable fault protection devices like Residual Current Circuit Breakers (RCCBs) has surged. Mandatory installation rules in new residential projects, retrofitting requirements in older buildings, and frequent audits in commercial establishments are fueling market expansion. In Europe, IEC 60364 standards have driven wider adoption, while in emerging markets, governments are integrating RCCBs into urban infrastructure codes. This regulatory pressure is encouraging builders, facility managers, and industries to prioritize advanced safety equipment. As awareness grows around life and asset protection, RCCBs are being recognized as essential components in modern electrical installations.
- For instance, Schneider Electric supplies Acti9 RCCBs tested to IEC 61008, with trip times below 30 milliseconds at rated residual current, supporting compliance in residential and commercial wiring.
Urbanization and Infrastructure Development
Rapid urbanization across Asia, Africa, and Latin America is creating vast demand for electrical safety infrastructure, including RCCBs. New housing projects, smart cities, industrial parks, and commercial developments are being equipped with modern electrical systems that mandate current leakage protection. As cities expand, the electrical grid becomes more complex, raising the risk of faults and overloads. Governments and private developers are thus investing in safer, intelligent distribution networks. Residential complexes increasingly prefer 30mA RCCBs for human protection, while industrial units deploy higher sensitivity devices to protect machinery. The growing construction of data centers, hospitals, and schools further supports market demand. RCCBs offer scalable protection options suited to varied infrastructure types, making them a key enabler in the safe expansion of global urban spaces.
- For instance, ABB deploys F200 Series RCCBs in urban projects, supporting rated currents from 16 A up to 125 A and operating voltages of 230–400 V (up to 415 V). These units provide essential leakage protection for diverse environments, including housing, hospitals, and data centers.
Growing Awareness and Adoption of Smart Electrical Devices
The growing penetration of smart homes and buildings is transforming the demand profile of electrical components. Consumers now prefer safety devices with real-time monitoring, diagnostics, and remote reset capabilities. RCCBs are evolving with integrated communication features, enabling them to connect with home automation systems or industrial control platforms. These smart RCCBs alert users during faults and log performance data for predictive maintenance. Such innovation boosts value-added adoption in both developed and developing markets. As energy management becomes a priority, intelligent breakers also help optimize load distribution and improve energy efficiency. This aligns with sustainability goals and lowers downtime in critical facilities. The integration of IoT, cloud analytics, and AI into RCCBs is not just enhancing safety but also creating long-term operational and cost-saving advantages.
Key Trends & Opportunities
Integration with Renewable Energy and EV Infrastructure
The expansion of solar PV systems, wind farms, and electric vehicle (EV) charging stations creates new use cases for RCCBs. These systems often operate in outdoor or unstable environments, increasing the risk of leakage currents and faults. Residual current protection becomes essential for both safety and compliance. RCCBs compatible with DC and mixed-frequency currents are in demand, particularly in EV charging stations and hybrid power setups. As EV adoption increases, public and private infrastructure is incorporating dedicated RCCBs to meet safety norms. Similarly, net-metered renewable energy installations in homes and businesses require advanced protection to handle bidirectional current flow. This shift opens strong opportunities for specialized RCCB product lines tailored to clean energy ecosystems.
- For instance, ABB offers Type B RCCBs designed for EV charging, capable of detecting smooth DC residual currents above 6 mA and operating across 230–400 V systems used in public charging stations.
Technology Advancements and Product Innovation
RCCB manufacturers are investing in compact, modular, and multifunctional devices to serve evolving market needs. Recent innovations include arc fault detection, remote reset capability, and Wi-Fi-enabled breakers that integrate into building management systems. These features enhance user convenience, improve system diagnostics, and reduce operational downtime. Miniaturized RCCBs are gaining traction in residential applications where space-saving is critical. Simultaneously, industrial users demand high-capacity breakers that support high sensitivity and withstand harsh conditions. Product customization based on sensitivity levels, tripping speed, and environmental endurance is becoming a major differentiator. Such innovations not only increase safety but also enhance brand competitiveness, creating a strong trend towards premium and application-specific RCCB offerings.

Residual Current Circuit Breaker (RCCB) Market Key Challenges
Lack of Awareness and Improper Installation in Developing Regions
Despite regulatory efforts, many developing regions still face low awareness about the importance of RCCBs. Electrical contractors and end-users often prioritize cost over safety, leading to underuse or incorrect installation of protection devices. In rural or semi-urban areas, local electricians may lack adequate training, causing mismatched sensitivity selection or failure to ensure proper grounding. This compromises the RCCB’s performance and user safety. Moreover, counterfeit or substandard products can enter the supply chain due to limited oversight. Such challenges slow the market’s growth in cost-sensitive economies, especially where retrofitting older buildings is not enforced or financially supported by local authorities.
Price Sensitivity and Fragmented Product Landscape
The RCCB market is price-sensitive, especially in emerging economies where low-cost imports compete aggressively. Tier-1 players face challenges in balancing innovation with affordability. The fragmented nature of the market—with numerous regional and unbranded players—creates inconsistency in quality and standards. End-users often struggle to differentiate between products, leading to poor purchasing decisions. This fragmentation also leads to fluctuating distribution margins and limited brand loyalty. In some cases, advanced RCCBs with smart features are perceived as expensive or unnecessary. These barriers reduce penetration in lower-tier market segments and hinder growth in regions where affordability plays a central role in procurement decisions.
Regional Analysis
North America
North America accounted for a significant share of the Residual Current Circuit Breaker market, reaching USD 569.70 million in 2024, up from USD 446.40 million in 2018. The market is projected to grow to USD 1,094.96 million by 2032 at a CAGR of 8.7%. The region holds approximately 24.4% of the global market in 2024. Strong regulatory frameworks, advanced electrical infrastructure, and increased adoption of smart safety devices across residential and commercial segments support this growth. The U.S. leads due to high safety standards, ongoing modernization of grid systems, and consistent investments in residential construction and smart home solutions.
Europe
Europe captured around 20.3% of the global Residual Current Circuit Breaker market in 2024, with its value increasing from USD 383.40 million in 2018 to USD 474.23 million. It is forecasted to reach USD 850.17 million by 2032, growing at a CAGR of 7.7%. Regulatory mandates such as IEC 60364 drive adoption across residential and commercial installations. Germany, France, and the UK lead demand due to strict building codes, strong awareness of electrical safety, and widespread adoption of smart home technologies. Retrofitting initiatives in older infrastructure and growing renewable energy deployments contribute to regional expansion.
Asia Pacific
Asia Pacific dominates the global market with a 43.9% share in 2024, rising from USD 770.40 million in 2018 to USD 1,026.34 million. It is projected to reach USD 2,095.78 million by 2032, registering the highest CAGR of 9.5%. Rapid urbanization, construction growth, and strong government emphasis on infrastructure safety fuel demand. China and India lead in installations due to massive residential and industrial developments. Rising electrification in Southeast Asia and increasing demand for affordable protection devices support continued expansion. The presence of large domestic manufacturers and price-competitive offerings further accelerates regional adoption.
Latin America
Latin America holds a modest 6.3% share of the global RCCB market in 2024, with the market rising from USD 115.20 million in 2018 to USD 148.25 million. It is expected to reach USD 265.16 million by 2032 at a CAGR of 7.7%. Brazil and Mexico are the key contributors, driven by increasing construction activities and improved enforcement of electrical safety standards. Government programs aimed at upgrading public infrastructure and expanding residential housing drive market demand. The region’s potential is growing as awareness of fire and shock risks spreads, pushing higher penetration of RCCBs in both new and retrofit installations.
Middle East
The Middle East Residual Current Circuit Breaker market grew from USD 55.80 million in 2018 to USD 66.87 million in 2024, capturing a 2.9% global market share. It is anticipated to reach USD 113.08 million by 2032, growing at a CAGR of 6.9%. The market is driven by smart city developments and commercial projects in the UAE and Saudi Arabia. Regulatory alignment with international safety codes boosts installations across residential and hospitality sectors. Large-scale infrastructure initiatives, including airports, malls, and tourism hubs, require modern electrical safety equipment, supporting steady demand for RCCBs in the region.
Africa
Africa holds the smallest share of the global RCCB market at 2.3% in 2024, growing from USD 28.80 million in 2018 to USD 53.33 million. The market is projected to reach USD 84.99 million by 2032, registering a CAGR of 5.6%. Growth is supported by ongoing electrification programs, especially in Sub-Saharan Africa. South Africa and Nigeria lead the regional demand due to urban expansion and rising construction activity. However, market penetration remains limited due to affordability constraints and low awareness. Government and donor-driven infrastructure projects offer long-term opportunities as regulatory frameworks around electrical safety improve.

Residual Current Circuit Breaker (RCCB) Market Segmentations:
By Sensitivity:
- 10mA
- 30mA
- 100mA
- 300mA
- Others
By End-user:
- Residential
- Commercial
- Industrial
By Distribution Channel:
- Online
- Offline
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Residual Current Circuit Breaker (RCCB) market features a competitive landscape led by global players such as Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation, and Legrand. These companies dominate due to their wide product portfolios, strong distribution networks, and technological innovation. Key players focus on integrating smart functionalities, miniaturized designs, and DC compatibility to serve evolving residential, commercial, and industrial demands. Emerging firms and regional manufacturers compete on price, especially in Asia Pacific and Latin America. Strategic moves like product launches, mergers, and geographic expansions remain central to maintaining market presence. For instance, Schneider Electric continues to enhance its EcoStruxure-enabled RCCBs, while Siemens invests in smart grid-compatible solutions. Companies also emphasize sustainability by developing energy-efficient breakers. The competitive intensity is heightened by the growing role of online sales channels, allowing new entrants to capture niche segments. Overall, innovation, customization, and regulatory alignment define the market’s competitive dynamics.
Key Player Analysis
- Schneider Electric
- Siemens AG
- ABB Ltd.
- Eaton Corporation
- Legrand
- Hager Group
- Mitsubishi Electric Corporation
- General Electric
- Honeywell International Inc.
- Larsen & Toubro Limited
- Fuji Electric Co., Ltd.
- Hitachi Industrial Equipment Systems Co., Ltd.
- Rockwell Automation
- Havells India Ltd.
Recent Developments
- In February 2025, DOMO Chemicals and Siemens Smart Infrastructure partnered to advance sustainability in the electrical industry, resulting in the launch of the SENTRON 5SV3 residual current circuit breaker (RCCB). This innovative device features TECHNYL® 4EARTH® polyamide, composed of 50% recycled content, including chemically recycled PA6 from post-industrial and post-consumer sources. The material meets UL certification standards and maintains the same performance and safety as conventional alternatives. This collaboration reflects a growing industry shift toward eco-friendly materials and circular design practices, setting new benchmarks for sustainable electrical safety solutions.
- In February 2025, Schneider Electric participated in ELECRAMA 2025, showcasing its Dsine DZ MCCB (Molded Case Circuit Breaker) series. This new series is specifically designed to operate with renewable energy, featuring advanced system integration and modular digital trip components with customizable system interfaces for higher breaking capacity, efficiency, and enhanced protective optimization. This product launch addresses the increasing demand for circuit protection in renewable energy applications.
- In October 2024, Mitsubishi Electric announced plans to strengthen its production facilities for energy-efficient circuit breakers in the United States. This strategic move indicates a commitment to meeting the growing demand for advanced and sustainable circuit protection solutions in the North American market.
Report Coverage
The research report offers an in-depth analysis based on Sensitivity, End-user, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily due to rising awareness of electrical safety in residential sectors.
- Smart RCCBs with remote monitoring features will see higher adoption in smart buildings.
- Regulatory mandates will continue to drive demand across new and retrofitted construction projects.
- Asia Pacific will remain the largest and fastest-growing regional market.
- Manufacturers will invest in compact, modular, and high-sensitivity RCCB designs.
- Integration with solar and EV infrastructure will open new application areas.
- Online distribution channels will expand, especially in emerging economies.
- Industrial RCCBs with higher current ratings will gain traction in manufacturing zones.
- Training and certification for proper installation will improve adoption in low-awareness regions.
- Competition will increase between global brands and regional low-cost manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Residual Current Circuit Breaker market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Residual Current Circuit Breaker market projected to grow between 2024 and 2032?
Which Residual Current Circuit Breaker market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Residual Current Circuit Breaker market?
Who are the leading companies in the Residual Current Circuit Breaker market?
Which region commanded the largest share of the Residual Current Circuit Breaker market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Residual Current Circuit Breaker Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Residual Current Circuit Breaker Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,338.73 million → 2032: USD 4,504.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Residual Current Circuit Breaker Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Residual Current Circuit Breaker Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Residual Current Circuit Breaker Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Residual Current Circuit Breaker Market Drivers
- 3.3 Residual Current Circuit Breaker Market Restraints & Challenges
- 3.4 Residual Current Circuit Breaker Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Residual Current Circuit Breaker Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Residual Current Circuit Breaker Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Residual Current Circuit Breaker category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Residual Current Circuit Breaker Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Residual Current Circuit Breaker Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Residual Current Circuit Breaker market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Residual Current Circuit Breaker Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Residual Current Circuit Breaker Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Residual Current Circuit Breaker Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Residual Current Circuit Breaker (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Residual Current Circuit Breaker Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Residual Current Circuit Breaker Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Residual Current Circuit Breaker Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Residual Current Circuit Breaker Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Residual Current Circuit Breaker Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Residual Current Circuit Breaker Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Residual Current Circuit Breaker Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Residual Current Circuit Breaker Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Residual Current Circuit Breaker Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
