
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Venous Thromboembolism (VTE) Treatment Market Size 2023 | USD 1,306.82 million |
| Venous Thromboembolism (VTE) Treatment Market, CAGR | 7.85% |
| Venous Thromboembolism (VTE) Treatment Market Size 2032 | USD 2,579.87 million |
Market Overview
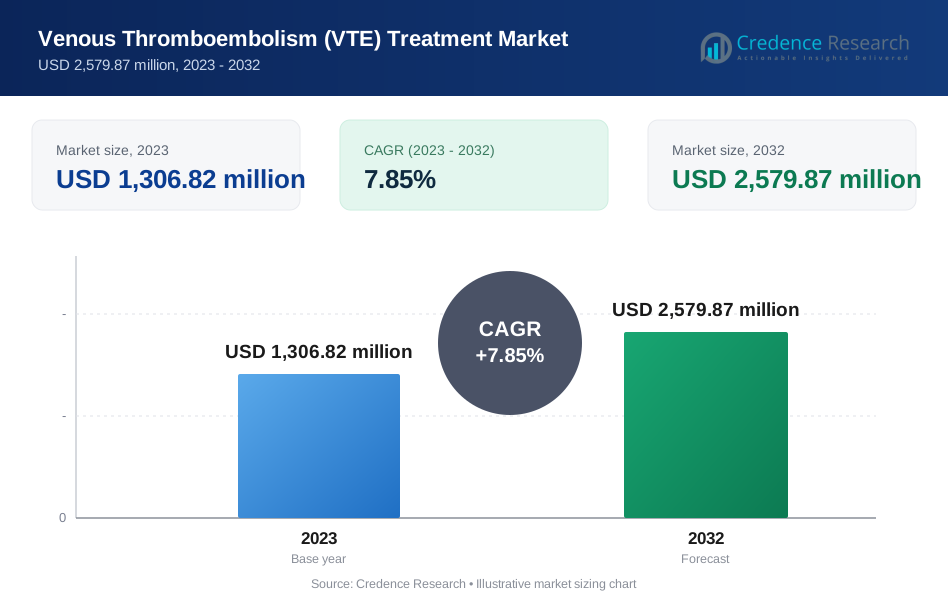
The Global Venous Thromboembolism (VTE) Treatment Market is projected to grow from USD 1,306.82 million in 2023 to USD 2,579.87 million by 2032, at a compound annual growth rate (CAGR) of 7.85%.
The Global Venous Thromboembolism (VTE) Treatment Market is experiencing robust growth, primarily driven by an aging global population and rising incidence of obesity, which are significant risk factors for VTE. Advances in pharmacological treatments and increasing awareness about the critical nature of early VTE diagnosis and treatment are further propelling market expansion. Additionally, improvements in healthcare infrastructure and extended post-surgical care are contributing to the demand for effective VTE management solutions. The market is also benefiting from the development of novel anticoagulants and the growing adoption of preventive measures in medical settings to reduce the incidence of hospital-acquired thrombosis.
The Global Venous Thromboembolism (VTE) Treatment Market is geographically diverse, with North America leading due to its advanced healthcare infrastructure, high awareness levels, and strong adoption of innovative therapies. Europe follows closely, driven by a growing aging population and government initiatives to manage VTE effectively. The Asia-Pacific region is emerging rapidly, fueled by increasing healthcare investments and rising incidences of VTE. Key players in the market include Boehringer Ingelheim, Bayer, and Pfizer, who dominate through extensive product portfolios, continuous innovation, and strategic collaborations, ensuring their stronghold in this expanding market.
Market Drivers
Escalating Prevalence and Awareness of VTE
The Global Venous Thromboembolism (VTE) Treatment Market is primarily driven by the rising prevalence of VTE, which is increasingly linked to obesity, sedentary lifestyles, and an aging global population. For instance, data from the Centers for Disease Control and Prevention (CDC) indicates that VTE affects an estimated 900,000 people in the United States each year. As these risk factors become more common, the incidence of VTE naturally increases, driving up the demand for effective treatment solutions. Additionally, there is a growing awareness of the dangers associated with VTE, including its potential to cause severe complications or even death if not treated promptly. This heightened awareness is leading to earlier diagnosis and more proactive management of the condition, further stimulating market growth.
Technological Innovations and Geriatric Demographics
Technological advancements in the medical field are revolutionizing the prevention and treatment of VTE. The introduction of new anticoagulants that offer improved safety profiles and easier dosing regimens, alongside innovative mechanical devices like advanced compression systems, are key contributors to market expansion. For example, statistics from the United Nations Department of Economic and Social Affairs show that the number of persons aged 65 or above is projected to double to 1.5 billion by 2050. Concurrently, the global demographic shift towards a larger elderly population, who are at higher risk for VTE, is causing a surge in the demand for treatments that are both effective and safe for long-term use.
Government Support and Healthcare Development
Government initiatives aimed at reducing the incidence of VTE through better patient education, preventive measures, and funding for research into more effective treatments are vital drivers of the market. These programs not only enhance patient outcomes but also reduce long-term healthcare costs associated with managing chronic complications of VTE. Moreover, as healthcare infrastructure continues to expand and improve, particularly in developing regions, access to quality care and advanced VTE treatments is becoming more widespread, facilitating early detection and management of the disease.
Economic Factors Influencing Market Dynamics
The market is further buoyed by rising global disposable incomes, which allow for greater expenditure on health services, including advanced VTE treatments. This economic uplift is enabling patients worldwide to access higher-quality healthcare options and benefit from the latest advancements in VTE treatment and prevention. As healthcare systems continue to evolve and the global middle class expands, the capacity for patients to seek timely and effective treatment is significantly enhanced, supporting continued growth in the VTE treatment market.
Market Trends
Advancements in Treatment Modalities and Digital Health Solutions
Innovation continues to drive the VTE treatment market, particularly through the development of novel anticoagulants that offer improved safety profiles and greater efficacy, reducing the risk of bleeding complications associated with long-term anticoagulation therapy. A study published in the Journal of Medical Internet Research found that telehealth interventions for VTE management reduced hospital readmissions by 45% compared to standard care. This shift towards remote management is particularly significant given that, according to the American Heart Association, VTE-related healthcare costs in the U.S. are estimated to be between $7 billion and $10 billion annually. Digital tools facilitate ongoing patient education, real-time health monitoring, and efficient management of treatment plans from the comfort of the patient’s home, thereby reducing hospital visits and associated healthcare costs. Moreover, the focus on cost-effectiveness continues to be a crucial aspect of product development, aiming to make VTE treatment more accessible to a broader range of patients globally, ensuring that high-quality care is not just available but also affordable.
Integrating Prevention and Personalized Care in VTE Management
The Global Venous Thromboembolism (VTE) Treatment Market is witnessing a significant shift towards preventive strategies and personalized medicine. Increasingly, healthcare providers are emphasizing the importance of VTE prevention as a fundamental aspect of patient care, particularly in post-surgical settings. This involves the use of prophylactic anticoagulants, compression devices, and encouraging early mobilization to minimize the risk of clot formation. Concurrently, the field of personalized medicine is revolutionizing VTE treatment by tailoring therapeutic approaches to individual patient profiles, which considers genetic predispositions and existing comorbidities. This personalized approach ensures that treatment is both more effective and better suited to each patient's unique health needs, significantly improving patient outcomes.
Market Challenges Analysis
Financial and Adherence Barriers in VTE Treatment
The Global Venous Thromboembolism (VTE) Treatment Market faces significant challenges related to the high cost of treatment, particularly with novel anticoagulants. These medications, while effective, can be prohibitively expensive for many patients, limiting their access to essential care. A cross-sectional study conducted across 32 countries showed that only 39.5% of medical patients at risk of VTE had received appropriate prophylaxis compared to 58.5% of surgical patients. The medical patients’ appropriate prophylaxis compliance rate varied from 3 to 70% between countries. This financial barrier is especially pronounced in regions with limited healthcare coverage or where out-of-pocket expenses are substantial. Additionally, patient adherence to long-term anticoagulant therapy presents a persistent challenge. The need for consistent, daily medication can be burdensome, leading to non-adherence and, consequently, an increased risk of recurrent VTE. Ensuring that patients follow their prescribed treatment regimen is critical to preventing complications but remains difficult due to factors such as side effects, complexity of treatment plans, and patient forgetfulness.
Clinical and Diagnostic Hurdles in VTE Management
Another set of challenges in the VTE treatment market revolves around the clinical complexities associated with anticoagulant therapy and the difficulties in achieving early and accurate diagnosis. Anticoagulant therapy, while effective in preventing clot formation, carries a significant risk of bleeding, particularly in long-term use. This necessitates careful patient monitoring and management, which can be resource-intensive and requires a high level of clinical vigilance. Furthermore, diagnosing VTE early remains a major challenge in clinical practice. Symptoms of VTE can be nonspecific and easily mistaken for other conditions, leading to delays in treatment initiation and increasing the risk of severe complications. In addition to these issues, the market also suffers from a lack of highly effective and targeted treatment options. Although progress has been made, there is still a need for more innovative therapies that can provide better outcomes with fewer side effects. Finally, reimbursement issues and a general lack of awareness about VTE, especially in underdeveloped regions, further complicate the landscape, making it difficult for healthcare providers to offer and patients to receive optimal care.
Market Segmentation Analysis:
By Type:
The Global Venous Thromboembolism (VTE) Treatment Market is segmented by type into Deep Vein Thrombosis (DVT), Pulmonary Embolism (PE), and Others. Deep Vein Thrombosis represents a significant portion of the market due to its high incidence rate, particularly in aging populations and those with sedentary lifestyles. Pulmonary Embolism, often a severe complication of DVT, also commands a substantial share, driving the demand for effective treatment options. The “Others” category includes less common forms of VTE and related conditions, contributing to the overall market by addressing niche medical needs. The increasing awareness and early diagnosis of these conditions are propelling the demand for targeted and effective treatment solutions.
By Treatment:
The market is categorized into Mechanical Devices, Thrombolytic Therapy, Anti-Clotting Medications, and Others. Anti-Clotting Medications, including anticoagulants, dominate the market due to their widespread use in both prevention and treatment of VTE. Thrombolytic Therapy, used primarily in acute cases to dissolve clots, holds a significant market share, especially in severe cases of PE. Mechanical Devices, such as compression stockings and filters, are gaining traction as complementary therapies, particularly in patients who cannot tolerate medications. The “Others” segment includes emerging therapies and treatment innovations, reflecting ongoing advancements in VTE management. The diverse treatment options cater to varying patient needs, ensuring comprehensive care across different VTE presentations.
Segments:
Based on Type:
- Deep Vein Thrombosis
- Pulmonary Embolism
- Others
Based on Treatment:
- Mechanical Devices
- Thrombolytic Therapy
- Anti-Clotting Medications
- Others
Based on End-user:
- Homecare
- Specialty Centres
- Hospitals
- Others
Based on Distribution Channel :
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America
North America currently leads the market with a substantial share of approximately 40%, primarily due to its well-established healthcare system, high awareness of VTE, and widespread adoption of novel anticoagulant therapies. For instance, according to data from the Centers for Disease Control and Prevention, VTE affects an estimated 900,000 people in the U.S. each year, with 60,000-100,000 Americans dying from deep vein thrombosis and pulmonary embolism. The United States, in particular, dominates the North American market, benefiting from extensive research and development activities in VTE treatments and a large patient population.
Europe
Europe follows closely with a market share of around 35%, driven by its aging population, increasing incidence of VTE, and strong focus on preventive healthcare measures. For instance, a survey conducted by the European Society of Cardiology found that the annual incidence of VTE in Europe is approximately 104-183 per 100,000 person-years. Countries like Germany, the UK, and France are at the forefront of VTE treatment advancements, with their healthcare systems readily embracing innovative therapies and diagnostic tools.
Key Player Analysis
- Boehringer Ingelheim
- Bayer
- Janssen
- Arjo
- DJO Global
- ALN Implants chirurgicaux (ALN Surgical Implants)
- Bristol-Myers Squibb
- Pfizer
- Daiichi-Sankyo
- Portola
- Stryker Corporation
- AngioDynamics, Inc.
- Enovis Corporation
- LifeTech Scientific Corporation
- Medtronic plc
- Argon Medical Devices
- Cardinal Health (Medtronic)
- Cook Medical
- Boston Scientific Corporation
- Koninklijke Philips N.V.
Competitive Analysis
The competitive landscape of the Global Venous Thromboembolism (VTE) Treatment Market is dominated by leading pharmaceutical companies such as Boehringer Ingelheim, Bayer, Pfizer, and Bristol-Myers Squibb. These companies maintain a competitive edge through robust portfolios of anticoagulant therapies, including well-known products like Xarelto (Bayer), Eliquis (Pfizer/Bristol-Myers Squibb), and Pradaxa (Boehringer Ingelheim). Their strong market positions are reinforced by ongoing research and development efforts aimed at improving the safety and efficacy profiles of VTE treatments. Additionally, strategic partnerships, mergers, and acquisitions enable these companies to expand their global reach and enhance their product offerings. Emerging players like AngioDynamics and Stryker Corporation are also making strides in the market by focusing on innovative mechanical devices and combination therapies, further intensifying competition. Overall, the market is characterized by continuous innovation and strategic maneuvers aimed at capturing greater market share in this growing therapeutic area.
Recent Developments
- In August 2024, Daiichi Sankyo announced that the EMA has validated the Type II Variation application for ENHERTU®.
- In March 2024, Bayer announced advancements in its Pharma business to fuel long-term, sustainable growth as part of its Pharma strategy.
- In March 2023, Boehringer Ingelheim reported strong performance in 2022, with 30 million patients benefiting from its innovative medicines.
Market Concentration & Characteristics
The Global Venous Thromboembolism (VTE) Treatment Market exhibits a moderate to high level of market concentration, with a few key players such as Boehringer Ingelheim, Bayer, Pfizer, and Bristol-Myers Squibb dominating the industry. These companies hold significant market shares due to their extensive portfolios of anticoagulant therapies and strong global distribution networks. The market is characterized by intense competition, driven by continuous innovation in treatment options and the development of novel anticoagulants with improved safety and efficacy profiles. Additionally, the market is marked by strategic collaborations and mergers, allowing leading players to expand their reach and enhance their product offerings. The high entry barriers, including regulatory challenges and the need for substantial R&D investments, further contribute to the market's concentrated nature, making it challenging for new entrants to establish a foothold. Overall, the market's characteristics emphasize the importance of innovation, strategic partnerships, and global reach in maintaining a competitive edge.
Report Coverage
The research report offers an in-depth analysis based on Type, Treatment, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for novel anticoagulants with improved safety profiles will continue to drive market growth.
- Personalized medicine approaches will become increasingly important in tailoring VTE treatments to individual patient needs.
- The adoption of combination therapies is expected to rise, offering enhanced treatment outcomes for VTE patients.
- Digital health tools and remote monitoring will play a significant role in managing VTE treatment and improving patient adherence.
- The market will see increased investment in research and development for advanced mechanical devices and innovative treatment modalities.
- Emerging markets will contribute significantly to the growth of the VTE treatment market as healthcare infrastructure improves.
- The focus on cost-effective treatment options will drive the development of more accessible VTE therapies.
- Government initiatives and public health campaigns will enhance awareness and early detection of VTE, boosting demand for treatments.
- Strategic partnerships and mergers among key players will shape the competitive landscape and expand market reach.
- The integration of AI and data analytics in VTE treatment planning will improve patient outcomes and optimize treatment strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Venous Thromboembolism (VTE) TreatmentMarket?
What factors are driving the growth of the Global Venous Thromboembolism (VTE)Treatment Market?
What are the key segments within the Global Venous Thromboembolism (VTE) Treatment Market?
Who are the major players in the Global Venous Thromboembolism (VTE) Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Venous Thromboembolism (VTE) Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Venous Thromboembolism (VTE) Treatment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,306.82 million → 2032: USD 2,579.87 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Venous Thromboembolism (VTE) Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Venous Thromboembolism (VTE) Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Venous Thromboembolism (VTE) Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Venous Thromboembolism (VTE) Treatment Market Drivers
- 3.3 Venous Thromboembolism (VTE) Treatment Market Restraints & Challenges
- 3.4 Venous Thromboembolism (VTE) Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Venous Thromboembolism (VTE) Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Venous Thromboembolism (VTE) Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Venous Thromboembolism (VTE) Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Venous Thromboembolism (VTE) Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Venous Thromboembolism (VTE) Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Venous Thromboembolism (VTE) Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Venous Thromboembolism (VTE) Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Venous Thromboembolism (VTE) Treatment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Venous Thromboembolism (VTE) Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Venous Thromboembolism (VTE) Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Venous Thromboembolism (VTE) Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Venous Thromboembolism (VTE) Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Venous Thromboembolism (VTE) Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Venous Thromboembolism (VTE) Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Venous Thromboembolism (VTE) Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Venous Thromboembolism (VTE) Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Venous Thromboembolism (VTE) Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Venous Thromboembolism (VTE) Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Venous Thromboembolism (VTE) Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
