
Market Overview:
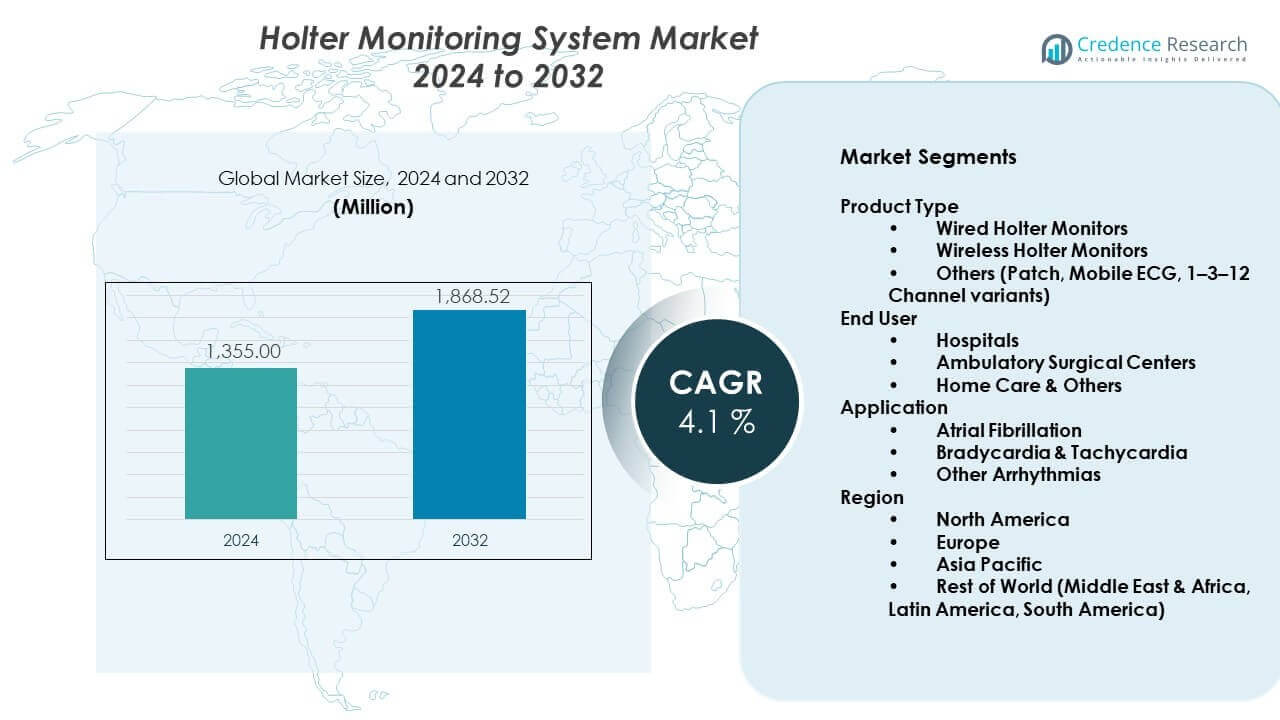
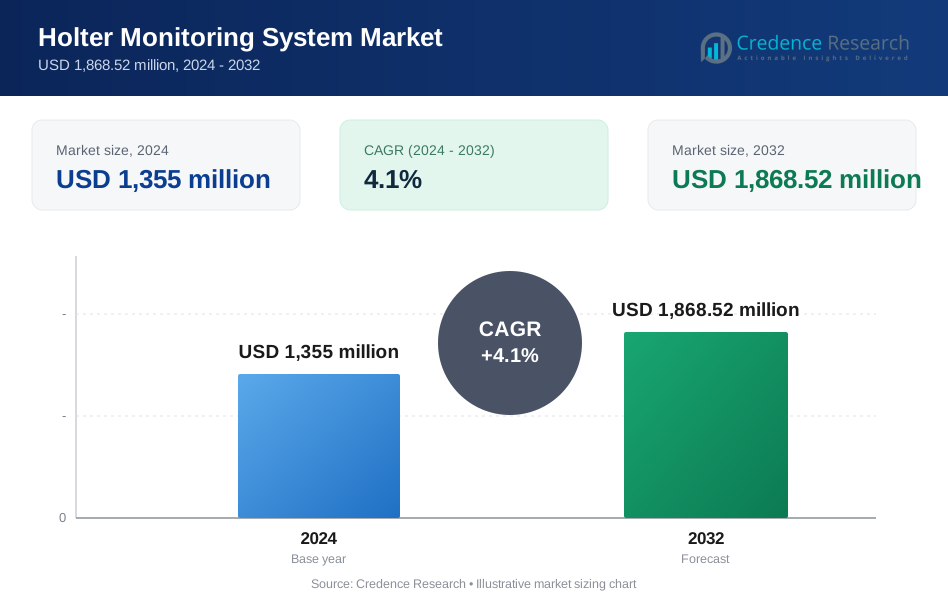
The Holter Monitoring System Market is projected to grow from USD 1,355 million in 2024 to USD 1,868.52 million by 2032. The market is expected to expand at a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Holter Monitoring System Market Size 2024 | USD 1,355 million |
| Holter Monitoring System Market, CAGR | 4.1 % |
| Holter Monitoring System Market Size 2032 | USD 1,868.52 million |
The Holter Monitoring System Market grows due to rising cardiovascular disease prevalence worldwide. Aging populations increase demand for long-term heart rhythm monitoring. Physicians prefer Holter devices for noninvasive and continuous diagnostics. Portable designs improve patient comfort and compliance. Digital data storage enhances diagnostic accuracy and review speed. Hospitals seek cost-effective tools for outpatient monitoring. Expanding preventive cardiology programs support routine screening use. Advances in wireless connectivity improve data transmission efficiency. Clinical reliance on early arrhythmia detection sustains consistent system demand.
North America leads the market due to advanced healthcare infrastructure and high cardiac screening rates. The United States drives adoption through strong reimbursement support. Europe follows with wide use across hospitals and cardiac clinics. Countries like Germany and the UK show steady system upgrades. Asia Pacific emerges as a fast-growing region. Rising healthcare access in China and India supports expansion. Latin America and the Middle East show gradual growth through improving diagnostic capacity.
Market Insights:
- The Holter Monitoring System Market was valued at USD 1,355 million in 2024 and is projected to reach USD 1,868.52 million by 2032, registering a CAGR of 4.1% during the forecast period.
- North America leads with about 38% share due to advanced healthcare systems, followed by Europe at 27% supported by standardized cardiac care, and Asia Pacific at 23% driven by expanding diagnostics access.
- Asia Pacific represents the fastest-growing region with nearly 23% share, supported by rising cardiovascular awareness, urbanization, and private hospital investments.
- By end user, hospitals dominate with nearly 52% share due to high patient volumes and strong reliance on continuous cardiac diagnostics.
- By product type, wireless Holter monitors account for around 45% share, reflecting preference for mobility, patient comfort, and outpatient monitoring use.
Market Drivers:
Rising Cardiovascular Disease Burden And Diagnostic Demand Expansion
The Holter Monitoring System Market gains momentum from rising cardiac disorder prevalence worldwide. Heart rhythm disorders affect adults across varied age groups. Hospitals rely on continuous monitoring for accurate diagnosis. Clinicians value extended data capture beyond standard ECG tests. Early arrhythmia detection supports timely clinical decisions. Public health programs promote routine cardiac assessments. Urban lifestyles increase cardiac risk exposure. Diagnostic demand grows across outpatient and ambulatory settings. These factors sustain steady system adoption.
- For instance, the CDC reports heart disease as the leading cause of death in the United States.
Growing Preference For Noninvasive And Continuous Monitoring Solutions
The Holter Monitoring System Market benefits from preference for noninvasive diagnostics. Patients favor wearable devices over hospital-based tests. Physicians trust continuous rhythm records for clinical clarity. Long-term monitoring improves symptom correlation accuracy. Portable devices reduce patient movement restrictions. Outpatient care models depend on such flexibility. Diagnostic centers adopt devices for workflow efficiency. It supports broader patient screening coverage. This preference strengthens recurring device utilization.
- For instance, iRhythm’s Zio XT patch supports up to 14 days of continuous ECG monitoring cleared by the FDA.
Expansion Of Hospital And Diagnostic Infrastructure Worldwide
The Holter Monitoring System Market grows with expanding healthcare infrastructure. Hospitals invest in advanced cardiac diagnostic tools. Diagnostic chains increase presence in tier-two cities. Private healthcare spending supports equipment upgrades. Cardiology departments expand service portfolios. Integrated care models require continuous monitoring solutions. Device availability improves across emerging markets. Trained clinical staff support effective device usage. Infrastructure growth reinforces long-term demand.
Supportive Clinical Guidelines And Preventive Cardiology Adoption
The Holter Monitoring System Market receives support from preventive cardiology focus. Medical guidelines emphasize early rhythm disorder detection. Physicians follow protocol-based monitoring recommendations. Screening programs target high-risk populations. Insurance frameworks support diagnostic monitoring coverage. Preventive care reduces long-term treatment burden. Clinicians prefer objective rhythm data for assessment. It aligns with evidence-based care standards. This driver maintains consistent clinical reliance.
Market Trends:
Shift Toward Compact Wearable And Lightweight Monitoring Devices
The Holter Monitoring System Market shows strong movement toward compact designs. Manufacturers focus on lighter and smaller form factors. Patients experience better comfort during extended wear periods. Improved ergonomics support higher compliance rates. Wearable formats suit active patient lifestyles. Device aesthetics influence patient acceptance levels. Clinics prefer easy-to-fit solutions. It improves overall test completion rates. This trend reshapes product development priorities.
For instance, Philips BioTel Heart devices use lightweight wearable sensors designed for extended patient use.
Integration Of Advanced Software And Automated Data Interpretation
The Holter Monitoring System Market reflects rising software integration trends. Automated analysis reduces clinician review time. Algorithms support faster arrhythmia identification. Digital dashboards improve data visualization clarity. Cloud-based access supports remote physician review. Hospitals value efficiency gains in reporting. Software updates extend device lifecycle value. It enhances diagnostic workflow precision. Technology-led differentiation becomes more visible.
- For instance, GE HealthCare’s MUSE cardiology system supports automated ECG and Holter data analysis used in hospitals worldwide.
Growing Adoption Of Remote Monitoring And Telecardiology Models
The Holter Monitoring System Market aligns with telecardiology expansion. Remote data access supports decentralized care delivery. Physicians review reports without physical device handling. Rural healthcare benefits from specialist reach. Home-based monitoring reduces hospital visit frequency. Health systems prioritize virtual care models. Data transmission reliability improves service trust. It supports continuity of care strategies. Remote adoption reshapes service delivery models.
Standardization Of Diagnostic Protocols Across Care Settings
The Holter Monitoring System Market experiences protocol standardization growth. Hospitals adopt uniform monitoring durations. Diagnostic criteria align across institutions. Standard reports improve inter-clinician communication. Training programs reinforce consistent device usage. Standard workflows reduce diagnostic variability. Healthcare networks favor predictable outcomes. It strengthens clinical confidence in results. Standardization supports scalable deployment.
Market Challenges Analysis:
High Device Costs And Budget Constraints Across Healthcare Providers
The Holter Monitoring System Market faces cost-related challenges. Advanced devices require higher upfront investment. Small clinics struggle with capital allocation. Maintenance expenses impact long-term ownership cost. Budget limits delay replacement cycles. Public hospitals face procurement restrictions. Price sensitivity affects adoption speed. It pressures manufacturers to balance cost and performance. Financial constraints slow penetration in low-income regions.
Data Management Complexity And Skilled Workforce Limitations
The Holter Monitoring System Market encounters operational challenges in data handling. Continuous monitoring generates large data volumes. Clinicians require specialized interpretation skills. Training gaps affect diagnostic accuracy. Workflow overload strains cardiology departments. Data storage compliance adds administrative burden. Smaller centers lack technical support teams. It increases dependence on external service providers. Operational complexity restricts smooth adoption.
Market Opportunities:
Untapped Demand In Emerging Economies With Rising Cardiac Awareness
The Holter Monitoring System Market holds strong opportunity in emerging regions. Cardiac awareness programs increase diagnostic demand. Urbanization raises lifestyle-related heart risks. Private healthcare investment expands diagnostic capacity. Middle-income populations seek preventive screening. Local hospitals upgrade cardiac services. Device affordability improvements support market entry. It opens new revenue channels. Emerging markets offer long-term growth potential.
Product Innovation Focused On Home-Based And Long-Term Monitoring
The Holter Monitoring System Market gains opportunity through home-use expansion. Patients prefer monitoring within familiar environments. Long-duration devices capture intermittent arrhythmias effectively. Manufacturers develop extended battery solutions. Simplified device operation suits home deployment. Home monitoring reduces hospital resource strain. Care providers support decentralized diagnostics. It aligns with patient-centric care models. Innovation-driven offerings strengthen competitive positioning.
Market Segmentation Analysis:
Product Type Analysis
The Holter Monitoring System Market includes wired, wireless, and alternative device formats. Wired Holter monitors retain use in hospitals due to stable signal quality. Wireless Holter monitors gain strong preference for patient comfort and mobility. Healthcare providers value ease of use and flexible data transfer. Patch and mobile ECG formats support discreet monitoring needs. Multi-channel variants improve rhythm capture accuracy. Product choice depends on clinical setting and monitoring duration. Technology evolution supports wider segment balance.
- For instance, GE HealthCare’s SEER 1000 Holter recorder supports 2- and 3-channel ECG recording with Bluetooth connectivity and up to 7-day monitoring with CardioDay integration.
End User Analysis
The Holter Monitoring System Market serves hospitals, ambulatory surgical centers, and home care settings. Hospitals represent the largest user base due to high diagnostic volumes. Cardiology departments rely on continuous rhythm assessment tools. Ambulatory surgical centers adopt systems for preoperative screening. Outpatient diagnostics benefit from faster turnaround times. Home care use expands with portable device availability. Patients prefer monitoring outside clinical environments. End-user diversity supports steady demand distribution.
- For instance, cardiology units use multi-channel Holter systems like GE SEER 1000 for extended cardiac rhythm capture
Application Analysis
The Holter Monitoring System Market addresses atrial fibrillation, bradycardia, tachycardia, and other arrhythmias. Atrial fibrillation monitoring drives significant clinical demand. Long-duration recording improves detection of intermittent episodes. Bradycardia and tachycardia assessment supports therapy planning. Physicians depend on accurate rhythm trend data. Other arrhythmias require extended observation periods. Diagnostic precision improves treatment confidence. Application diversity sustains broad clinical adoption.
Segmentation:
Product Type
- Wired Holter Monitors
- Wireless Holter Monitors
- Others (Patch, Mobile ECG, 1–3–12 Channel variants)
End User
- Hospitals
- Ambulatory Surgical Centers
- Home Care & Others
Application
- Atrial Fibrillation
- Bradycardia & Tachycardia
- Other Arrhythmias
Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Regional Performance And Market Leadership
The Holter Monitoring System Market shows strong dominance in North America with nearly 38% market share. The United States drives regional demand through advanced cardiac diagnostics. Hospitals maintain high adoption of continuous monitoring technologies. Strong reimbursement coverage supports routine Holter use. High cardiovascular disease prevalence sustains diagnostic volume. Physicians rely on long-term rhythm monitoring for accurate treatment planning. Mature healthcare infrastructure reinforces regional leadership.
Europe Regional Adoption And Clinical Standardization Trends
Europe accounts for around 27% of the Holter Monitoring System Market share. Countries such as Germany, the UK, and France lead regional usage. Public healthcare systems emphasize preventive cardiac screening. Clinical guidelines promote extended rhythm monitoring protocols. Hospitals invest in standardized diagnostic workflows. Growing elderly populations increase arrhythmia detection needs. Regional focus on quality care supports steady system demand.
Asia Pacific And Rest Of World Growth Outlook
Asia Pacific holds close to 23% share in the Holter Monitoring System Market and shows rapid expansion. China and India lead growth through rising cardiac awareness. Healthcare access improves across urban centers. Private hospitals increase diagnostic equipment investments. Home-based monitoring adoption gains momentum. The Rest of World region contributes about 12% share. Improving healthcare infrastructure supports gradual market penetration.
Key Player Analysis:
- Philips Healthcare
- GE Healthcare
- Hillrom (Baxter)
- Schiller AG
- Fukuda Denshi
- Medtronic
- iRhythm Technologies
Competitive Analysis:
The Holter Monitoring System Market features strong competition among global medical device manufacturers. Leading players focus on product reliability, data accuracy, and clinical acceptance. Companies compete through portfolio breadth across wired, wireless, and patch-based systems. Strategic emphasis remains on software analytics and clinician workflow support. Established brands benefit from hospital trust and long-term contracts. Mid-sized players target ambulatory and home care settings. Innovation cycles remain frequent to maintain differentiation. It reflects moderate consolidation with clear technology-driven positioning.
Recent Developments:
- In July 2025, Philips Healthcare renewed and expanded its strategic partnership with Medtronic, building on over 30 years of collaboration in patient monitoring technology. The multi-year partnership agreement focuses on integrating next-generation Medtronic technologies into Philips' patient monitoring systems, including world-class Nellcor™ pulse oximetry, Microstream™ capnography, and BIS™ brain monitoring. Under this renewed agreement, Philips will bundle essential supplies including ECG electrodes, non-invasive blood pressure cuffs, and batteries with Philips' Medtronic-enabled monitors, providing a streamlined offering for healthcare providers. Both companies have established a joint pledge program emphasizing rigorous validation and testing for patient safety. Additionally, in September 2025, Philips launched its new smart telemetry platform with the Telemetry Monitor 5500, designed to address clinical challenges including staff shortages and alarm fatigue through streamlined alarm management and automated clinical tasks. Concurrently, Philips entered into a national partnership with Optum Healthcare, making its Mobile Cardiac Telemetry (MCOT) and Extended Holter (ePatch) solutions available to Optum's 3.4 million members across 22 US states. Earlier, in January 2024, Philips announced a strategic partnership with smartQare to acquire the Healthdot remote patient monitoring business, merging viQtor and Healthdot RPM portfolios into a single integrated digital solution. Furthermore, in March 2022, Philips acquired Cardiologs, a France-based medical technology company specializing in AI-powered cardiac diagnostics, to strengthen its ECG analysis and reporting capabilities with machine learning algorithms built on a database of over 20 million ECG recordings.
- iRhythm Technologies announced the commercial launch of its Zio long-term continuous monitoring (LTCM) system in Japan on May 1, 2025, commercially introduced as the Zio ECG Recording and Analysis System. The system provides up to 14 days of continuous uninterrupted ECG monitoring leveraging a deep-learned artificial intelligence algorithm approved by Japan's Pharmaceuticals and Medical Devices Agency (PMDA), representing a significant advancement over traditional wired Holter monitors that capture only 24 to 48 hours of data. The launch occurred through iRhythm's exclusive distribution partner Senko Medical Instrument, with nationwide availability anticipated by July 2025, addressing the growing demand for early and accurate arrhythmia detection in Japan, the world's second-largest ambulatory cardiac monitoring market. Furthermore, in September 2024, iRhythm entered into an exclusive license agreement with BioIntelliSense to enhance its ambulatory cardiac monitoring platform by integrating advanced multiparameter sensing technologies including pulse oximetry, accelerometry, and non-invasive blood pressure capabilities. At the American College of Cardiology (ACC) 2025 Scientific Sessions in March 2025, iRhythm presented compelling real-world data from over 1.1 million Zio users, revealing that 64 percent of patients with daily symptoms experiencing actionable arrhythmias remained undetected within the first 48 hours of monitoring with traditional Holter devices, underscoring the clinical advantages of extended monitoring duration. The data demonstrated that Zio long-term continuous monitoring is twice as effective as Holter monitoring and 72 percent more effective than event recorders in diagnosing arrhythmias, translating to reduced emergency department visits and hospitalizations.
Report Coverage:
The research report offers an in-depth analysis based on roduct Type, End User, and Application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will increase for wearable and patient-friendly cardiac monitoring devices across care settings.
- Remote cardiac diagnostics will gain wider acceptance within hospital and outpatient workflows.
- Software-based data analysis will play a stronger role in clinical decision support.
- Home-based Holter monitoring will expand within chronic and preventive cardiac care models.
- Hospitals will continue to adopt integrated cardiac diagnostic ecosystems.
- Emerging economies will experience higher adoption due to expanding healthcare access.
- Preventive cardiology programs will support routine and early rhythm monitoring.
- Device miniaturization will improve comfort and long-term patient compliance.
- Strategic partnerships will strengthen integration with digital health platforms.
- Competitive focus will remain on diagnostic accuracy and clinical workflow efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cardiovascular Disease Prevalence
Increasing rates of heart rhythm disorders and cardiovascular diseases globally are driving demand for continuous and accurate cardiac monitoring, making Holter systems essential for early detection and management.
Preference for Noninvasive and Continuous Monitoring
Patients and clinicians increasingly favor wearable, noninvasive Holter monitors that provide extended, uninterrupted ECG data, improving diagnostic accuracy and patient compliance compared to traditional short-term ECG tests.
Expansion of Preventive Cardiology and Screening Programs
Healthcare systems and public health initiatives are emphasizing routine cardiac screening and early arrhythmia detection, leading to greater adoption of Holter monitoring in both hospital and outpatient settings.
Technological Advancements in Wireless and Digital Solutions
Innovations such as wireless connectivity, automated data analysis, and compact wearable designs enhance patient comfort, streamline clinical workflows, and enable remote monitoring, further boosting market growth.
Growth in Healthcare Infrastructure and Access in Emerging Markets
Expanding hospital networks, increased private healthcare investment, and rising cardiac awareness in emerging economies are opening new opportunities for Holter monitoring system adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Holter Monitoring System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Holter Monitoring System Market projected to grow between 2025 and 2032?
Which Holter Monitoring System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Holter Monitoring System Market?
Who are the leading companies in the Holter Monitoring System Market?
Which region commanded the largest share of the Holter Monitoring System Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Home Care & Others
- 1.3 By Application
- 1.3.1 Atrial Fibrillation
- 1.3.2 Bradycardia & Tachycardia
- 1.3.3 Other Arrhythmias
- 1.4 By Product Type
- 1.4.1 Wired Holter Monitors
- 1.4.2 Wireless Holter Monitors
- 1.4.3 Others (Patch, Mobile ECG, 1–3–12 Channel variants)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,355 million → 2032: USD 1,868.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Holter Monitoring System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Holter Monitoring System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Holter Monitoring System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Holter Monitoring System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Holter Monitoring System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Holter Monitoring System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Holter Monitoring System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Holter Monitoring System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,355 million → 2032: USD 1,868.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Holter Monitoring System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Home Care & Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Atrial Fibrillation
- 12.4.7.2 Bradycardia & Tachycardia
- 12.4.7.3 Other Arrhythmias
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Wired Holter Monitors
- 12.5.7.2 Wireless Holter Monitors
- 12.5.7.3 Others (Patch, Mobile ECG, 1–3–12 Channel variants)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Holter Monitoring System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Holter Monitoring System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Holter Monitoring System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Holter Monitoring System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Philips Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE Healthcare
- 18.4 Hillrom (Baxter)
- 18.5 Schiller AG
- 18.6 Fukuda Denshi
- 18.7 Medtronic
- 18.8 iRhythm Technologies
- 18.9 CardioNet (BioTelemetry, a Philips company)
- 18.10 BPL Medical Technologies
- 18.11 Spacelabs Healthcare
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

