
Market Overview:
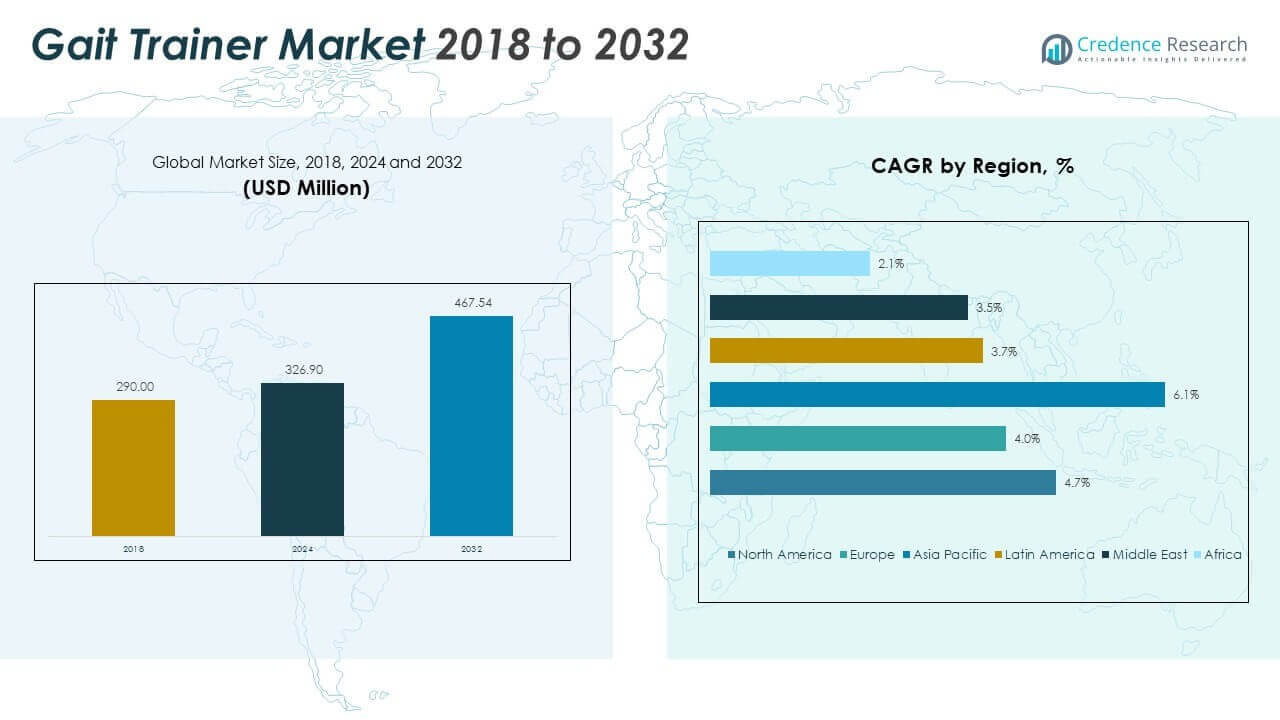
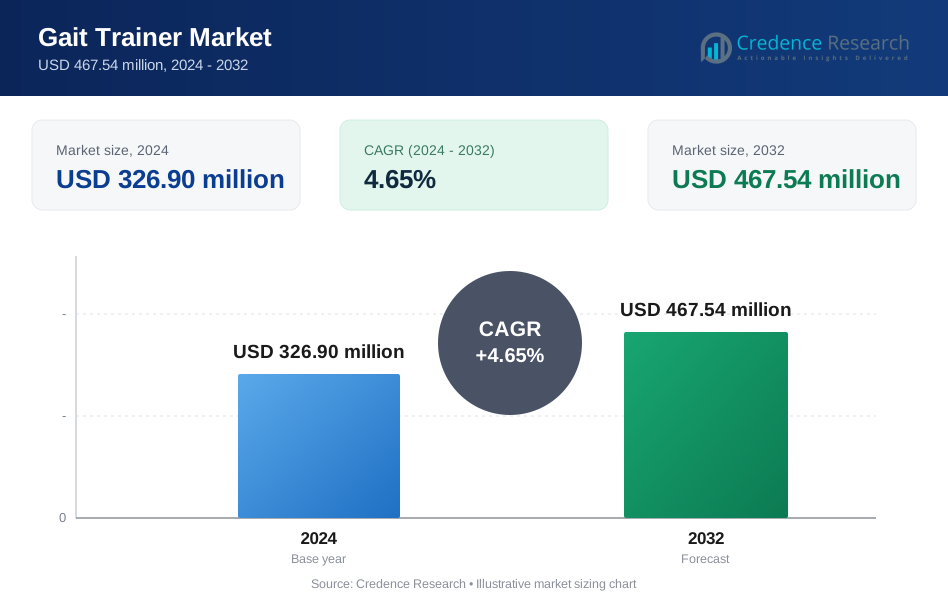
The Global Gait Trainer Market size was valued at USD 290.00 million in 2018 to USD 326.90 million in 2024 and is anticipated to reach USD 467.54 million by 2032, at a CAGR of 4.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gait Trainer Market Size 2024 | USD 326.90 Million |
| Gait Trainer Market, CAGR | 4.65% |
| Gait Trainer Market Size 2032 | USD 467.54 Million |
Market growth is driven by rising cases of neurological and mobility disorders worldwide. Stroke, spinal cord injury, and cerebral palsy increase demand for assisted gait rehabilitation. Aging populations raise the need for long-term mobility support solutions. Hospitals and rehabilitation centers invest in advanced therapy equipment to improve recovery outcomes. Clinical focus on early mobilization supports wider adoption. Technological improvements enhance safety, adjustability, and patient comfort. Insurance coverage for rehabilitation services further supports market expansion.
North America leads the market due to strong healthcare infrastructure and high rehabilitation spending. The United States drives adoption through advanced rehab centers and skilled therapists. Europe follows with strong demand from Germany, France, and the UK, supported by aging demographics. Asia Pacific emerges as a fast-growing region due to improving healthcare access. China and India show rising adoption from expanding rehabilitation facilities. Latin America and the Middle East remain developing but show gradual uptake.
Market Insights:
- The market expanded from USD 290.00 million in 2018 to USD 326.90 million in 2024 and is projected to reach USD 467.54 million by 2032, growing at a CAGR of 4.65%.
- North America leads with about 37.8% share, Europe follows with 27.3%, and Asia Pacific holds 22.2%, driven by strong rehabilitation infrastructure and healthcare spending.
- Asia Pacific is the fastest-growing region, holding around 22.2% share, supported by hospital expansion, rising rehabilitation awareness, and improving access to therapy services.
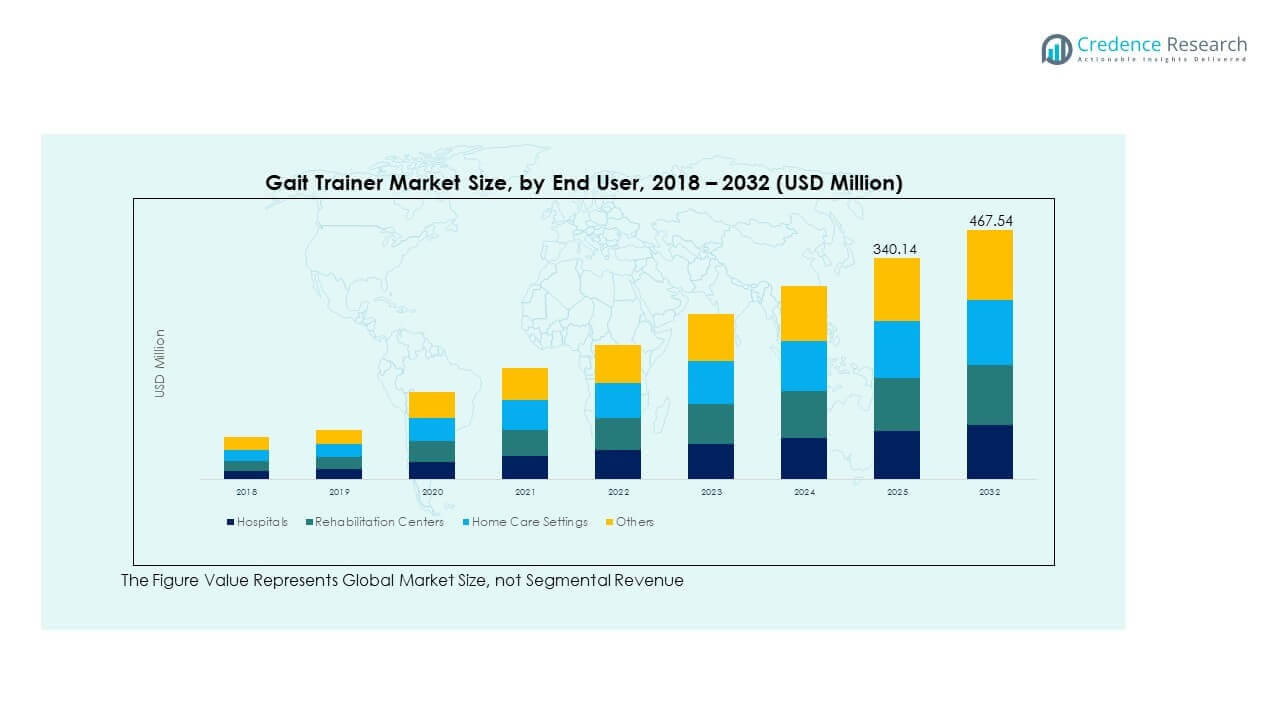
- Hospitals account for the largest end-user share at roughly 35%, reflecting high patient inflow and structured post-acute rehabilitation programs.
- Rehabilitation centers follow with about 30% share, supported by specialized therapy focus and growing demand for dedicated mobility recovery services.
Market Drivers:
Rising Burden Of Neurological And Mobility Related Disorders Worldwide
The Global Gait Trainer Market benefits from higher cases of stroke and spinal cord injury. Cerebral palsy cases continue to require long-term gait therapy. Traumatic brain injuries increase rehabilitation needs across age groups. Hospitals focus on structured mobility recovery programs. Gait trainers support controlled and repeatable walking therapy. Clinicians prefer equipment that improves patient confidence. Early rehabilitation improves functional outcomes. This demand sustains steady equipment adoption.
Growing Geriatric Population Requiring Assisted Rehabilitation Solutions
Aging populations face higher risk of balance and mobility loss. Elderly patients often need supervised gait training. Rehabilitation centers expand services for senior care. Gait trainers reduce fall risk during therapy sessions. Care providers value adjustable support systems. Demand rises for devices that support gradual mobility return. Long-term care facilities invest in rehabilitation equipment. This driver supports stable market demand.
- For instance, Biodex reports that its Gait Trainer 3 enables programmable step counts exceeding 1,000 steps per therapy session, improving safety and stability during elderly rehabilitation.
Expansion Of Rehabilitation Infrastructure Across Hospitals And Clinics
Healthcare systems invest in specialized rehabilitation departments. Public and private hospitals add therapy equipment. Gait trainers improve therapy efficiency for therapists. Clinics seek tools that handle multiple patient profiles. Standardized therapy protocols favor mechanical assistance devices. Equipment helps optimize therapist workload. Training outcomes improve with consistent movement patterns. Infrastructure growth drives wider equipment placement.
Supportive Reimbursement And Clinical Adoption For Physical Therapy Services
Insurance programs cover post-acute rehabilitation in many regions. Physicians prescribe gait therapy after major surgeries. Rehabilitation guidelines support assisted walking programs. Therapists rely on proven mechanical support devices. It gains acceptance in post-stroke recovery plans. Structured therapy improves patient adherence. Reimbursement stability supports purchasing decisions. Clinical trust strengthens long-term demand.
Market Trends:
Integration Of Smart Monitoring And Sensor-Based Feedback Systems
Manufacturers add sensors to track gait parameters. Digital displays support therapy progress review. Data helps therapists adjust therapy intensity. Remote monitoring supports long-term patient follow-up. Smart features improve therapy precision. Clinics value measurable rehabilitation outcomes. Technology upgrades increase product differentiation. This trend reshapes product development focus.
- For instance, Motek Medical systems such as the GRAIL (Gait Realtime Analysis Interactive Lab) integrate force plates sampling at 1,000 Hz with 3D motion capture systems, utilizing D-Flow software to process gait parameters in real-time for clinical and research applications.
Growing Preference For Compact And Space Efficient Therapy Equipment
Facilities face space limits in therapy rooms. Compact gait trainers suit outpatient clinics. Lightweight frames ease equipment relocation. Foldable designs support shared therapy spaces. Urban hospitals prefer smaller equipment footprints. Space efficiency lowers installation barriers. Portable systems increase clinical flexibility. Design innovation supports broader adoption.
- For instance, Reha-Stim Medtec offers robotic gait training systems (such as the Gait Trainer GT II) with a compact footprint designed to fit into smaller therapy rooms, supporting shared therapy environments.
Shift Toward Patient-Centric And Adjustable Therapy Configurations
Therapy programs require personalized rehabilitation plans. Adjustable harness systems support varied body types. Speed and support control enhance therapy comfort. Patient engagement improves with adaptable settings. Therapists prefer flexible configuration options. Comfort reduces therapy drop-out rates. Customization improves clinical satisfaction. This trend drives design refinement.
Increasing Use Of Gait Trainers In Pediatric Rehabilitation Programs
Pediatric therapy centers adopt specialized gait trainers. Devices support children with developmental disorders. Early mobility training improves long-term outcomes. Child-friendly designs gain attention. Adjustable height features suit growth needs. Therapists value safe pediatric support systems. Rehabilitation schools invest in such equipment. Pediatric focus expands addressable demand.
Market Challenges Analysis:
High Equipment Cost And Capital Investment Requirements For Providers
The Global Gait Trainer Market faces pricing pressure across regions. Advanced systems require significant upfront investment. Smaller clinics struggle with budget limits. Maintenance costs affect long-term ownership value. Public hospitals face procurement delays. Cost concerns slow replacement cycles. Financing options remain limited in some regions. Price sensitivity restricts wider penetration.
Limited Skilled Workforce And Therapy Training Constraints
Gait trainers require trained therapists for safe use. Skill gaps exist in developing healthcare systems. Improper use may reduce therapy benefits. Training programs demand time and resources. Staff shortages affect therapy capacity. Clinics delay adoption without skilled operators. Knowledge gaps limit advanced feature usage. Workforce limits slow market expansion.
Market Opportunities:
Expansion Of Rehabilitation Services In Emerging Healthcare Markets
Emerging economies invest in rehabilitation infrastructure. Government programs support disability care services. Hospitals expand post-acute therapy units. Demand rises for standardized therapy equipment. It benefits from new hospital construction. Local manufacturing reduces cost barriers. Awareness of rehabilitation improves steadily. These markets offer strong growth potential.
Product Innovation Focused On Home-Based And Community Rehabilitation
Home-based therapy gains acceptance among patients. Compact gait trainers suit non-clinical settings. Community centers add rehabilitation services. Home care reduces hospital burden. Devices with simple controls gain demand. Aging populations prefer home rehabilitation options. Manufacturers target easy-to-use designs. This shift opens new revenue channels.
Market Segmentation Analysis:
By Product
The Global Gait Trainer Market shows clear product-level differentiation across therapy needs. Gait trainer walkers hold strong demand due to simple design and wide clinical use. These devices support early-stage mobility therapy across age groups. Exoskeletons gain traction for advanced rehabilitation programs that target neurological recovery. These systems support controlled movement and posture correction. Treadmill systems remain vital in intensive therapy settings. They enable repetitive gait training under supervised conditions. Product choice depends on therapy intensity and patient mobility levels.
- For instance, Ekso Bionics reports that its EksoNR exoskeleton has helped patients take more than 120 million steps in over 450–500 rehabilitation centers globally. The device is used in programs for conditions including stroke, spinal cord injury (SCI), and acquired brain injury (ABI)
By End User
Hospitals represent a key end user due to high patient inflow and post-acute care demand. These facilities rely on gait trainers for structured recovery programs. Rehabilitation centers show strong adoption driven by specialized therapy focus. These centers prioritize equipment that improves therapy efficiency. Home care settings gain momentum due to preference for long-term rehabilitation at home. Compact and user-friendly devices support this shift. Other end users include clinics and assisted living facilities. These segments support steady demand through diversified care delivery models.
- For instance, Cleveland Clinic deploys robotic gait training systems across multiple rehabilitation units to standardize post-stroke mobility recovery protocols.
Segmentation:
- By Product
- Gait Trainer Walkers
- Exoskeletons
- Treadmill Systems
- By End User
- Hospitals
- Rehabilitation Centers
- Home Care Settings
- Others
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Gait Trainer Market size was valued at USD 110.78 million in 2018 to USD 123.44 million in 2024 and is anticipated to reach USD 176.31 million by 2032, at a CAGR of 4.7 during the forecast period. The Global Gait Trainer Market shows strong maturity across North America. The region holds nearly 37.8% market share in 2024. The United States leads demand through advanced rehabilitation infrastructure. Hospitals adopt gait trainers for post-stroke and injury recovery. Skilled therapists support effective equipment use. Insurance coverage improves therapy access. Canada follows with steady clinical adoption. Focus on early mobility therapy supports demand. Technology upgrades sustain regional leadership.
Europe
The Europe Global Gait Trainer Market size was valued at USD 82.07 million in 2018 to USD 89.17 million in 2024 and is anticipated to reach USD 120.98 million by 2032, at a CAGR of 4.0 during the forecast period. Europe accounts for about 27.3% market share in 2024. Germany, France, and the UK lead regional demand. Aging populations increase rehabilitation needs. Public healthcare systems support structured therapy programs. Rehabilitation centers invest in standardized equipment. Clinical guidelines favor assisted gait therapy. Eastern Europe shows gradual adoption growth. Strong medical device regulation supports product quality.
Asia Pacific
The Asia Pacific Global Gait Trainer Market size was valued at USD 61.19 million in 2018 to USD 72.52 million in 2024 and is anticipated to reach USD 116.09 million by 2032, at a CAGR of 6.1 during the forecast period. Asia Pacific holds nearly 22.2% market share in 2024. The region shows the fastest growth pace. China drives demand through hospital expansion. Japan supports adoption with advanced rehabilitation practices. India shows rising demand from private therapy centers. Urban healthcare investment improves access. Awareness of mobility rehabilitation increases steadily. Local manufacturing supports affordability.
Latin America
The Latin America Global Gait Trainer Market size was valued at USD 17.98 million in 2018 to USD 20.07 million in 2024 and is anticipated to reach USD 26.59 million by 2032, at a CAGR of 3.7 during the forecast period. Latin America represents about 6.1% market share in 2024. Brazil leads regional demand through urban hospitals. Private rehabilitation clinics support equipment adoption. Public healthcare funding remains limited. Imported equipment dominates supply. Therapist availability affects usage rates. Awareness of advanced therapy tools improves slowly. Gradual infrastructure growth supports steady demand.
Middle East
The Middle East Global Gait Trainer Market size was valued at USD 12.18 million in 2018 to USD 12.94 million in 2024 and is anticipated to reach USD 16.88 million by 2032, at a CAGR of 3.5 during the forecast period. The region holds nearly 4.0% market share in 2024. GCC countries drive most demand. Investments focus on premium healthcare facilities. Rehabilitation centers expand within urban hospitals. Medical tourism supports advanced therapy adoption. Equipment imports dominate the market. Skilled workforce availability remains uneven. Government healthcare projects support gradual growth.
Africa
The Africa Global Gait Trainer Market size was valued at USD 5.80 million in 2018 to USD 8.76 million in 2024 and is anticipated to reach USD 10.69 million by 2032, at a CAGR of 2.1 during the forecast period. Africa accounts for about 2.7% market share in 2024. South Africa leads regional adoption. Public hospitals face budget constraints. Rehabilitation infrastructure remains limited in many countries. Imported devices dominate supply chains. Nonprofit programs support mobility care access. Awareness of gait therapy remains low. Long-term healthcare investment offers future potential.
Key Player Analysis:
- Meyland Smith A/S
- Biodex Medical Systems
- Medica Medizintechnik GmbH
- ReWalk Robotics
- AlterG Inc.
- Rex Bionics Ltd.
- Ekso Bionics
- Hocoma AG
- Otto Bock Inc.
- Rifton Equipment
- Medical Depot Inc. (Drive Medical)
Competitive Analysis:
The Global Gait Trainer Market shows moderate concentration with established medical device firms. Companies compete through product reliability and clinical acceptance. Portfolio depth supports presence across hospitals and rehabilitation centers. Firms invest in ergonomic design and safety features. Distribution strength supports regional reach. Brand reputation influences hospital procurement decisions. Smaller players focus on niche therapy needs. It reflects steady competition with gradual technology upgrades. Partnerships with clinics support product validation. Competitive intensity remains stable across developed markets.
Recent Developments:
- Most recently, in December 2025, Ekso Bionics announced an exclusive U.S. distributor agreement with MediTouch's BalanceTutor rehabilitation system, further expanding its rehabilitation technology portfolio. The company reported strong Q3 2025 financial performance with revenue of $4.2 million (up 2% year-over-year), gross margin of 60.3% (up 680 basis points), and net loss of $1.4 million (improved 31% year-over-year). Personal Health products demonstrated particularly strong growth, increasing over 50% year-over-year in the first half of 2025.
- Ekso Bionics has also focused on expanding FDA-cleared indications beyond its current approvals for spinal cord injury, stroke, traumatic brain injury, and multiple sclerosis, with ongoing exploration of applications for Parkinson's disease, ALS, and orthopedic recovery. The company implemented a 1-for-15 reverse stock split in June 2025 to maintain NASDAQ compliance while concentrating on product development and market expansion.
- Ottobock achieved a major milestone in September 2025 with its Frankfurt Initial Public Offering (IPO), returning to public markets after shelving an earlier attempt in 2022. The IPO valued the company at €4.2 billion, with Ottobock raising €808 million-marking Germany's largest IPO since March 2024. The Näder family, descendants of founder Otto Bock, retained an 81% stake in the company, with plans to gradually reduce holdings to 70-75% after a 180-day lock-up period. Cornerstone investors included Hamburg billionaire Klaus-Michael Kühne and Capital Group.
- A major product milestone was achieved in April 2025 when Lifeward announced the national U.S. launch of the ReWalk 7 Personal Exoskeleton. This next-generation device incorporates several advanced innovations including cloud connectivity, customizable walking speeds, a handheld crutch control unit for intuitive operation, a wrist control smartwatch, and the MyReWalk mobile app for activity tracking. The ReWalk 7 received FDA clearance in March 2025, marking a significant advancement in personal exoskeleton technology. The device also features improved battery life and enhanced therapist training capabilities through a new handheld control device, making it optimized for real-world use with unmatched user experience and freedom of movement.
- In March 2025, Lifeward expanded its partnership portfolio by announcing an expanded agreement with MYOLYN, Inc., the developer of the MyoCycle FES Cycling Therapy System. This new partnership extends beyond the existing clinical distribution of MyoCycle Pro to include direct sales support for MyoCycle Home, enabling therapists to refer patients transitioning from clinical therapy to home-based rehabilitation. This strategic expansion aligns with Lifeward's case management infrastructure, allowing the company to serve more patients in their post-clinical recovery phase.
Report Coverage:
The research report offers an in-depth analysis based on product and end user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rehabilitation demand will rise with aging populations.
- Hospitals will expand structured mobility therapy programs.
- Home-based rehabilitation will gain wider acceptance.
- Smart gait trainers will see higher clinical interest.
- Pediatric rehabilitation will support niche demand growth.
- Emerging markets will invest in therapy infrastructure.
- Compact designs will suit space-limited clinics.
- Training programs will improve therapist adoption rates.
- Partnerships will support faster regional expansion.
- Product customization will strengthen competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Burden of Neurological and Mobility Disorders
Increasing incidence of stroke, spinal cord injury, cerebral palsy, and traumatic brain injuries is driving demand for gait trainers as essential tools for structured rehabilitation and mobility recovery across all age groups.
Growing Geriatric Population
Aging populations worldwide are experiencing higher rates of balance and mobility loss, leading to greater need for assisted rehabilitation solutions such as gait trainers in hospitals, rehabilitation centers, and long-term care facilities.
Expansion of Rehabilitation Infrastructure
Healthcare systems are investing in specialized rehabilitation departments and therapy equipment, with hospitals and clinics adding gait trainers to improve therapy efficiency and patient outcomes, especially in emerging markets.
Supportive Reimbursement and Clinical Adoption
Insurance coverage for post-acute rehabilitation and clinical guidelines supporting assisted gait therapy are encouraging hospitals and therapists to adopt gait trainers, ensuring stable and growing demand.
Technological Advancements and Smart Features
Integration of sensor-based feedback, digital monitoring, and compact, adjustable designs is enhancing therapy precision, patient comfort, and clinical outcomes, making gait trainers more attractive to both providers and patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Gait Trainer Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Gait Trainer Market projected to grow between 2025 and 2032?
Which Global Gait Trainer Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Gait Trainer Market?
Who are the leading companies in the Global Gait Trainer Market?
Which region commanded the largest share of the Global Gait Trainer Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Gait Trainer Walkers
- 1.2.2 Exoskeletons
- 1.2.3 Treadmill Systems
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Rehabilitation Centers
- 1.3.3 Home Care Settings
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 326.90 million → 2032: USD 467.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gait Trainer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gait Trainer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gait Trainer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gait Trainer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gait Trainer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gait Trainer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gait Trainer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gait Trainer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 326.90 million → 2032: USD 467.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gait Trainer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Gait Trainer Walkers
- 12.3.7.2 Exoskeletons
- 12.3.7.3 Treadmill Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Rehabilitation Centers
- 12.4.7.3 Home Care Settings
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gait Trainer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gait Trainer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gait Trainer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gait Trainer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Meyland Smith A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Biodex Medical Systems
- 18.4 Medica Medizintechnik GmbH
- 18.5 ReWalk Robotics
- 18.6 AlterG Inc.
- 18.7 Rex Bionics Ltd.
- 18.8 Ekso Bionics
- 18.9 Hocoma AG
- 18.10 Otto Bock Inc.
- 18.11 Rifton Equipment
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

