
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
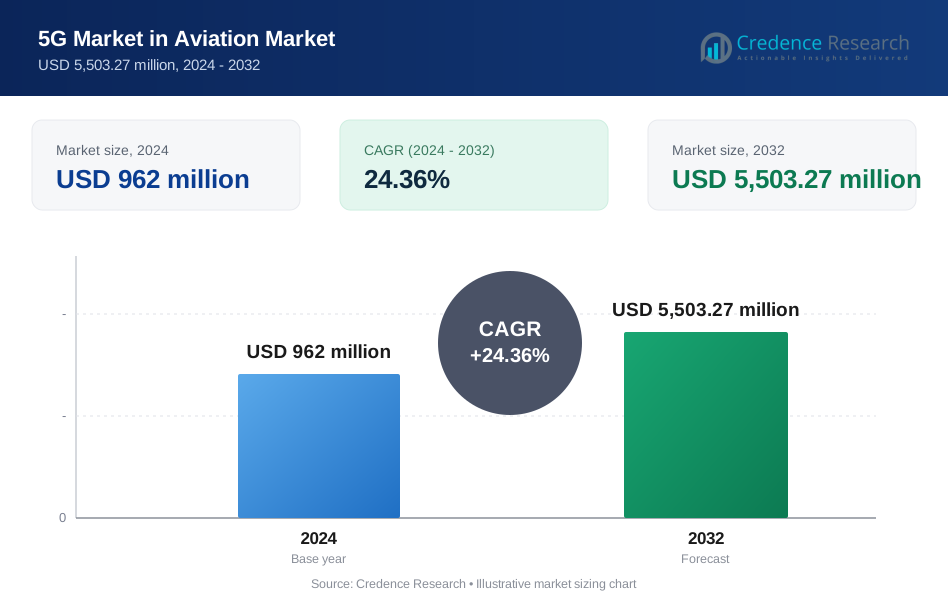
| 5G Market in Aviation Market Size 2024 | USD 962 Million |
| 5G Market in Aviation Market, CAGR | 24.36% |
| 5G Market in Aviation Market Size 2032 | USD 5,503.27 Million |
Market Overview
The 5G market in aviation market is projected to grow from USD 962 million in 2024 to USD 5,503.27 million by 2032, reflecting a compound annual growth rate (CAGR) of 24.36%.
The 5G market in aviation is driven by the increasing demand for faster and more reliable communication systems that enhance operational efficiency and passenger experience. The adoption of 5G technology facilitates real-time data sharing, improved connectivity, and enhanced Internet of Things (IoT) applications, leading to optimized flight operations and maintenance. Additionally, the ongoing modernization of airport infrastructure to support advanced technologies and the growing inclination towards autonomous and connected aircraft further propel this market's growth. These trends underscore a significant shift towards more technologically integrated and efficient aviation ecosystems.
The 5G market in aviation demonstrates significant geographic diversity and involves key players from across the globe. In North America, companies like Cisco Systems Inc., Gogo LLC, and Inseego Corp. are pivotal in advancing 5G integration in aviation. Europe is represented by industry giants such as AeroMobile Communications Limited and OneWeb Ltd, which are pushing the envelope in mobile communications and satellite networks, respectively. In Asia, Huawei Technologies Co., Ltd. leads with cutting-edge 5G solutions. These companies, along with others like Nokia Corporation in Finland and Panasonic Avionics Corporation in the U.S., are instrumental in shaping the global adoption and implementation of 5G in the aviation sector.
Market Drivers
Passenger Demand for Connectivity
As air travel continues to thrive, with over 4.5 billion passengers flying annually, passengers increasingly seek seamless, high-speed internet access during their travel journey from the moment they book their flights to maintaining connectivity in-flight. The robust bandwidth provided by 5G technology supports these growing demands, enabling passengers to enjoy streaming, video calls, and online gaming at high altitudes without interruption. For instance, Inmarsat’s Global Passenger Survey found that 65% of passengers believe inflight Wi-Fi is a necessity. This evolution is transforming passenger expectations and setting new standards for in-flight services.
Enhanced Airport Operations
Airports are capitalizing on 5G to boost operational efficiency and safety. This technology enables real-time monitoring of runways and autonomous snow removal, enhancing response times and reducing the potential for delays. For instance, at Helsinki Airport, autonomous snowplows clear runways with a precision of 2.5 cm, thanks to 5G connectivity. Moreover, 5G facilitates superior data sharing for flight scheduling and terminal logistics, streamlining airport operations and improving the overall efficiency of the air travel ecosystem.
Rise of Connected Technologies
The integration of the Internet of Things (IoT) within aviation is revolutionizing the industry, with sensors now embedded in everything from aircraft components to baggage handling systems. For instance, Airbus’s Skywise platform connects over 9,000 aircraft to optimize operations. The high data transmission capabilities of 5G are essential for effectively managing these vast networks of interconnected systems. This connectivity ensures that data flows seamlessly, enhancing the reliability and efficiency of operations across the aviation sector.
Focus on Efficiency and Improved Flight Experience
The aviation industry’s pursuit of greater efficiency finds a powerful ally in 5G technology, which optimizes maintenance schedules through real-time diagnostics and streamlines air traffic control by facilitating faster communication of data. For instance, Lufthansa Technik reports a 15% reduction in maintenance costs due to predictive maintenance enabled by 5G. Simultaneously, airlines are leveraging 5G to differentiate their services and enhance the flight experience. This technology enables high-quality streaming, virtual reality experiences, and other in-flight entertainment options, making air travel more enjoyable and competitive. For example, Qatar Airways offers Qsuite, which provides passengers with a private space equipped with ambient mood lighting and fully lie-flat beds, all connected through 5G technology.
Market Trends
Comprehensive In-Flight Connectivity and Efficient Airport Operations
The demand for high-speed internet during flights is reshaping passenger expectations, prompting airlines to adopt 5G technology to offer seamless and enhanced in-flight experiences. For instance, the demand for high-speed internet during flights is reshaping passenger expectations, prompting airlines to adopt 5G technology to offer seamless and enhanced in-flight experiences. This includes capabilities for high-quality streaming, where passengers can enjoy speeds up to 1 Gbps, allowing for uninterrupted 4K video streaming. Video conferencing can be conducted with virtually no lag, and immersive virtual reality entertainment becomes a new norm with 5G’s 10 times faster data transmission compared to 4G. Beyond the skies, 5G’s impact extends to the ground where airports utilize this technology to improve operational efficiencies and safety measures. Enhanced features such as real-time runway monitoring with autonomous equipment can lead to a 25% reduction in runway incursion incidents, while advanced air traffic control communication and dynamic holographic displays for passenger information are revolutionizing how airports operate, significantly reducing delays and optimizing passenger flow through terminals.
Emergence of Urban Air Mobility and IoT Integration
As urban air mobility (UAM) gains traction, the role of 5G becomes increasingly crucial. The technology’s low latency of just 1 millisecond and high bandwidth are essential for the safe operation of drones and flying taxis, where reliable and rapid data transmission is vital for navigation and control. For instance, the use of 5G in drone delivery services can increase delivery speeds by up to 70% compared to traditional methods. Simultaneously, the aviation sector’s embrace of the Internet of Things (IoT) is profound, with an extensive network of sensors integrated into various aspects of aviation from aircraft structures to baggage systems. For example, IoT sensors on aircraft can detect maintenance needs, potentially reducing unscheduled aircraft maintenance by up to 30%. 5G’s robust data handling capacities are pivotal in managing these interconnected systems, enabling enhanced diagnostics, predictive maintenance, and overall improved operational efficiency across the industry. These advancements are setting the stage for a more connected and technologically advanced aviation landscape, promising significant improvements in both the passenger experience and airport operations.
Market Challenges Analysis
Infrastructure and Regulatory Hurdles
The deployment of 5G technology within the aviation sector entails substantial infrastructure investment, presenting a significant challenge. This includes the installation of new cell towers, extensive upgrades to existing equipment, and modifications to aircraft to support the new technology. Such endeavors require considerable upfront financial commitments, which may cause airlines and airport authorities to hesitate due to the high costs involved. Moreover, the global aviation industry is governed by stringent regulations that necessitate clear international standards and comprehensive regulatory frameworks for 5G implementation. Ensuring seamless and safe operation across diverse countries and airspaces adds another layer of complexity to the adoption of 5G, requiring coordinated and well-regulated efforts.
Technical and Security Concerns
Potential safety concerns have also emerged, notably the risk of 5G signals interfering with critical navigational instruments such as radio altimeters. These instruments are essential for safe aircraft landing, and any interference could pose serious risks. Although regulatory bodies are actively seeking solutions, this remains a critical issue that necessitates meticulous mitigation strategies. Additionally, the operational characteristics of 5G which utilizes higher frequency bands with shorter ranges demand a dense network of cell towers, particularly around airports. The competition for this spectrum space from other industries further complicates this challenge. Furthermore, the increase in data transmission capabilities with 5G brings to the forefront issues of data privacy and security. It is imperative for airlines and aviation authorities to develop robust cybersecurity measures to safeguard sensitive passenger information and essential flight data against potential breaches, ensuring trust and safety in the use of 5G technologies in aviation.
Market Segmentation Analysis:
By Component:
The 5G market in aviation is segmented into hardware, software, and services. Hardware encompasses the physical components required for 5G deployment, such as antennas and routers, which are crucial for establishing robust 5G networks at airports and on aircraft. The software segment involves the solutions that manage network operations and ensure security and efficiency in data handling, playing a pivotal role in optimizing both in-flight connectivity and ground operations. Services, the third segment, include installation, maintenance, and updates essential for the seamless operation of 5G infrastructures. These services ensure that aviation stakeholders consistently benefit from the latest advancements in 5G technology, thus enhancing overall network performance and reliability.
By Connectivity:
In terms of connectivity, the 5G aviation market is categorized into eMBB (Enhanced Mobile Broadband), URLLC (Ultra-Reliable Low Latency Communication), mMTC (Massive Machine Type Communications), network slicing, and others. eMBB focuses on providing high data rates that enhance in-flight passenger experiences through superior internet speeds and streaming capabilities. URLLC is critical for safety-critical applications, offering highly reliable and low-latency communication essential for autonomous ground operations and potentially unmanned aerial vehicles. mMTC facilitates widespread sensor connectivity, crucial for IoT integration in various aviation applications, from fleet management to baggage handling. Network slicing allows operators to create multiple virtual networks within a single physical 5G network, enabling more tailored services that can meet diverse requirements within the aviation sector, ranging from passenger connectivity to critical communications.
Segments:
Based on Component
- Hardware
- Software
- Services
Based on Connectivity
- eMBB (Enhanced Mobile Broadband)
- URLLC (Ultra-Reliable Low Latency Communication)
- mMTC (Massive Machine Type Communications)
- Network Slicing
- Others
Based on Application
- Monitoring & Tracking
- Connected Vehicle
- Smart Surveillance
- VR & AR
- Others
Based on End-use
- Manufacturing
- Automotive
- Energy & Utilities
- Transportation & Logistics
- healthcare
- Others
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently leads the 5G market in aviation with approximately 35% market share. The United States, in particular, is at the forefront of 5G implementation in the aviation sector, driven by major airlines and airports investing heavily in digital transformation. The region's advanced telecommunications infrastructure and supportive regulatory framework have accelerated 5G adoption. Major hubs like Atlanta, Chicago, and Los Angeles are pioneering 5G-enabled services, enhancing passenger experiences and operational efficiencies. Canada is also making significant strides, focusing on 5G implementation in airports to improve security and passenger flow.
Europe
Europe holds the second-largest market share at around 30%. The region's strong focus on innovation and digital integration in aviation has propelled 5G adoption. Countries like Germany, France, and the UK are leading the charge, with major airports in Frankfurt, Paris, and London implementing 5G networks to enhance operations and passenger services. The European Union's initiatives to standardize 5G implementation across member states have provided a boost to market growth. However, the pace of adoption varies across the continent, with Eastern European countries generally lagging behind their Western counterparts.
Key Player Analysis
- AeroMobile Communications Limited (U.K.)
- Cisco Systems Inc. (The U.S.)
- Telefonaktiebolaget LM Ericsson (Sweden)
- ANUVU Inc. (Global Eagle Entertainment Inc.) (U.S.)
- Gogo LLC (U.S.)
- Huawei Technologies Co., Ltd. (China)
- Inseego Corp. (U.S.)
- Intelsat Corporation (U.S.)
- Nokia Corporation (Finland)
- OneWeb Ltd (U.K.)
- Panasonic Avionics Corporation (U.S.)
- SmartSky Networks LLC (U.S.)
Competitive Analysis
The competitive landscape of the 5G market in aviation is defined by a blend of established telecommunications giants and specialized aviation technology providers. Cisco Systems Inc. and Huawei Technologies Co., Ltd. lead with robust telecommunications infrastructure capabilities, driving advancements in network reliability and data handling. Nokia Corporation focuses on network solutions that enhance safety and efficiency in aviation communications. Telefonaktiebolaget LM Ericsson offers tailored 5G solutions that optimize real-time data transmission critical for aviation operations. In the niche of in-flight connectivity, Gogo LLC and Panasonic Avionics Corporation stand out by enhancing passenger experience through high-speed internet services. Additionally, OneWeb Ltd and Intelsat Corporation are key players in satellite communications, expanding 5G reach to ensure global coverage. Each company contributes to a highly competitive market by focusing on specific aspects of 5G technology to meet diverse aviation needs, from ground operations to in-flight connectivity.
Recent Developments
- In February 2024, Seamless Air Alliance (SAA), California, announced that it will foster the development and integration of 3GPP specified 5G NTN into the aviation sector to enable future connectivity between terrestrial and non-terrestrial satellite networks.
- In December 2023, Gogo Business Aviation received FAA approvals to begin producing Avance LX5 systems for its coming 5G air-to-ground service. The FAA has granted supplemental type certification (STC) and Parts Manufacturer Approval (PMA) of the Avance LX5 line replaceable unit (LRU).
- In October 2023, Montreal-based aircraft manufacturer Bombardier announced a new partnership with Duncan Aviation. The partnership with the Nebraska aerospace company is set to provide 5G connectivity upgrades across several of Bombardier's existing aircraft.
Market Concentration & Characteristics
The 5G market in aviation exhibits a moderate to high level of market concentration, characterized by the presence of several major telecommunications and aviation technology firms that dominate the landscape. This concentration is driven by the substantial capital requirements and technical expertise needed to develop and deploy 5G solutions effectively within the aviation sector. Leading companies such as Cisco Systems, Huawei Technologies, and Nokia Corporation leverage their extensive resources and technological prowess to innovate and capture significant market share. Additionally, the market is marked by strategic collaborations and partnerships between 5G technology providers and aviation companies to tailor and integrate 5G solutions that meet the unique demands of airport operations and in-flight connectivity. These characteristics underscore a competitive environment where technical innovation and strategic alliances are crucial for gaining and maintaining market leadership in the rapidly evolving 5G aviation landscape.
Report Coverage
The research report offers an in-depth analysis based on Component, Connectivity, Application, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Accelerated deployment of 5G infrastructure at airports worldwide to enhance operational efficiencies and passenger experiences.
- Increased investment in R&D to develop more robust and secure 5G networks specifically tailored for aviation requirements.
- Expansion of 5G services to support emerging technologies such as autonomous drones and flying taxis in urban air mobility.
- Greater integration of Internet of Things (IoT) devices in aviation, facilitated by 5G's capability to handle large data volumes.
- Adoption of network slicing to provide customized connectivity solutions for various aviation applications, from crew communications to maintenance.
- Enhanced in-flight connectivity services to offer high-speed internet, streaming, and possibly virtual reality entertainment to passengers.
- Partnerships between aviation stakeholders and 5G technology providers to leverage expertise and accelerate technology adoption.
- Regulatory advancements to ensure the safe and efficient use of 5G in aviation, addressing concerns related to spectrum use and cybersecurity.
- Improvement in global coverage of 5G, reducing connectivity gaps especially in remote and underserved regions.
- Continuous monitoring and upgrading of 5G systems to keep pace with evolving technology standards and increasing data demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the 5G Market in Aviation Market?
What factors are driving the growth of the 5G Market in Aviation Market?
What are the key segments within the 5G Market in Aviation Market?
What are some challenges faced by the 5G Market in Aviation Market?
Who are the major players in the 5G Market in Aviation Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 5G Market in Aviation Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 5G Market in Aviation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 962 million → 2032: USD 5,503.27 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 5G Market in Aviation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 5G Market in Aviation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 5G Market in Aviation Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 5G Market in Aviation Market Drivers
- 3.3 5G Market in Aviation Market Restraints & Challenges
- 3.4 5G Market in Aviation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 5G Market in Aviation Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 5G Market in Aviation Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 5G Market in Aviation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 5G Market in Aviation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. 5G Market in Aviation Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to 5G Market in Aviation. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 5G Market in Aviation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 5G Market in Aviation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 5G Market in Aviation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 5G Market in Aviation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in 5G Market in Aviation
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 5G Market in Aviation Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America 5G Market in Aviation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 5G Market in Aviation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 5G Market in Aviation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 5G Market in Aviation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 5G Market in Aviation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 5G Market in Aviation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 5G Market in Aviation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
