
Market overview
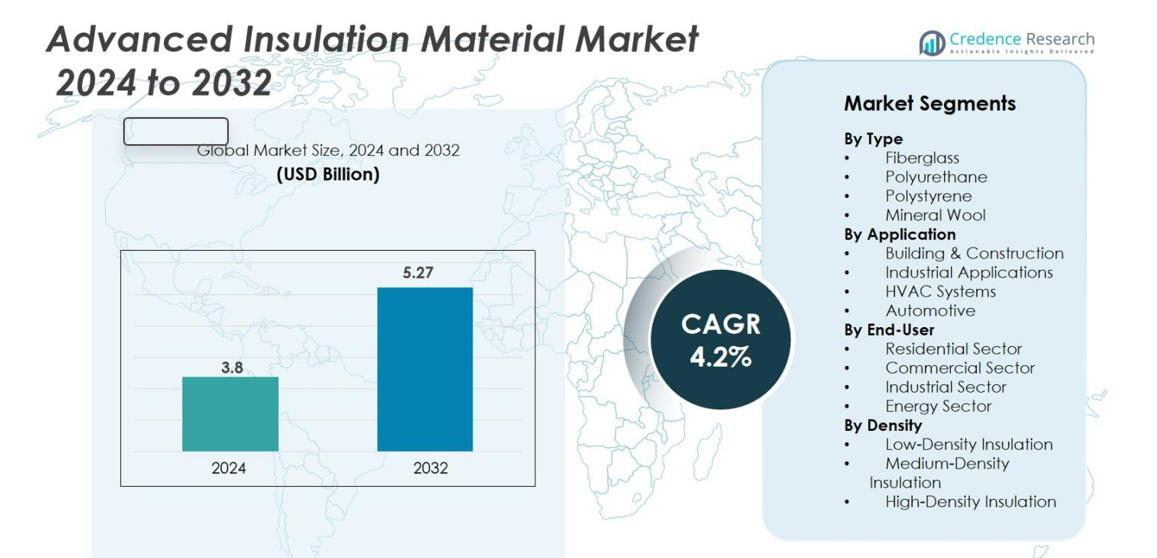
The Advanced Insulation Material market size was valued at USD 3.8 Billion in 2024 and is anticipated to reach USD 5.27 Billion by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Advanced Insulation Material Market Size 2024 | USD 3.8 Billion |
| Advanced Insulation Material Market, CAGR | 4.2% |
| Advanced Insulation Material Market Size 2032 | USD 5.27 Billion |
The Advanced Insulation Material market is shaped by strong competition among major manufacturers such as BASF SE, UBE Industries Ltd., Johns Manville Corporation, Aspen Aerogels Inc., Armacell International S.A., and Nitto Denko Corporation. These companies focus on high-performance fiberglass, polyurethane foams, aerogels, and polystyrene products to meet strict energy-efficiency and fire-safety standards in construction, industrial plants, and HVAC systems. North America leads the market with a 34% share, driven by large commercial projects and industrial insulation demand, while Europe follows due to strong sustainability mandates. Asia-Pacific expands rapidly as infrastructure development, manufacturing growth, and urbanization increase insulation requirements.
Market Insights
- The Advanced Insulation Material market reached USD 3.8 Billion in 2024 and is forecast to reach USD 5.27 Billion by 2032 at a 4.2% CAGR.
- Growing demand for energy-efficient buildings and industrial facilities drives adoption of fiberglass, polyurethane, polystyrene, and aerogel-based insulation across major construction and retrofit projects.
- Leading trends include the shift toward recyclable, lightweight, and high-temperature insulation, with companies such as BASF SE, Aspen Aerogels Inc., and Armacell International S.A. investing in sustainable and thin-profile solutions.
- Cost sensitivity in developing regions and performance concerns in harsh environments restrain adoption, particularly where cheaper traditional insulation remains widely used.
- North America leads with 34% share, followed by Europe at 28%, while Asia-Pacific holds 25% and remains the fastest growing. By type, fiberglass is dominant with 32% share, while the commercial sector leads end-use demand at 35%, supported by large-scale urban construction and retrofitting.
Market Segmentation Analysis:
By Type
Fiberglass leads the market with a 32% share due to strong thermal resistance, low cost, and broad installation flexibility. It remains a preferred choice in residential and commercial insulation because manufacturers offer standardized rolls and batts for walls, attics, and duct lining. Polyurethane and polystyrene follow due to high R-value and moisture barrier benefits, while mineral wool gains traction in fire-rated structures. The shift toward energy-efficient retrofitting in old buildings supports fiberglass demand, as contractors use lightweight fiberglass blankets to minimize heat transfer and reduce long-term heating and cooling loads.
- For instance, Owens Corning produces fiberglass insulation known for its superior thermal performance and sustainability credentials, widely used in residential and commercial buildings.
By Application
Building & Construction dominates the segment with a 41% share, driven by strict energy-efficiency codes and higher demand for thermal and acoustic control. Builders prefer composite fiberglass and polyurethane panels for roofs, facades, and wall cavities. Industrial applications are rising due to high-temperature insulation in oil, gas, and process plants, while HVAC systems use polystyrene boards and flexible mineral wool to reduce energy loss in ducting. Automotive manufacturers adopt lightweight aerogel-based insulations to improve cabin comfort and meet emissions rules linked to fuel efficiency.
- For instance, automotive manufacturers have adopted lightweight aerogel-based insulation materials, produced by suppliers like Aspen Aerogels, to enhance cabin safety and energy efficiency while helping meet stringent emissions and fuel efficiency standards.
By End-User
The Commercial Sector holds a 35% share, making it the leading end-user due to rapid construction of malls, offices, hospitals, airports, and data centers. Facility developers choose high-density fiberglass, polyurethane foams, and mineral wool panels to comply with fire-safety and building insulation standards. The residential sector benefits from renovation projects and green housing programs, while the industrial and energy sectors use advanced insulation in turbines, pipelines, and heat-intensive systems. Rising electricity consumption and strict carbon-reduction policies continue to push commercial users toward advanced insulation solutions that lower operational costs.
Key Growth Drivers
Rising Demand for Energy-Efficient Infrastructure
The push for reduced energy consumption across residential, commercial, and industrial facilities drives the adoption of advanced insulation materials. Governments enforce strict energy codes and green building certifications, such as LEED and BREEAM, which require high-performance insulation in walls, roofs, HVAC ducts, and industrial equipment. Builders and manufacturers prefer materials like fiberglass, polyurethane, and aerogel due to strong thermal resistance and reduced heat transfer. Aging building stock in North America and Europe also fuels retrofit projects, as property owners replace outdated insulation to meet modern standards and lower monthly energy costs. The continued rise in electricity prices strengthens the value proposition, making high-efficiency insulation an attractive long-term investment for developers and facility owners.
- For instance, Johns Manville offers formaldehyde-free fiberglass insulation that is dimensionally stable, does not settle, and maintains thermal performance over time, making it widely used in HVAC systems and commercial buildings.
Growth in Industrial Manufacturing and Process Applications
Industrial segments such as oil and gas, chemicals, power generation, and food processing rely on advanced insulation to manage heat flow, protect machinery, and reduce energy waste. High-temperature materials like mineral wool and aerogel blankets provide stability under extreme conditions and improve worker safety. Many plants upgrade pipelines, boilers, turbines, and storage vessels with new insulation technology to minimize heat loss and emissions. Regulations on industrial efficiency and carbon output accelerate adoption, while emerging markets expand manufacturing capacity. As energy-intensive industries continue to expand in Asia-Pacific and the Middle East, demand for reliable thermal insulation rises, positioning advanced solutions as key to operational efficiency and environmental compliance.
- For instance, Thermaxx Jackets improved energy efficiency at TE Connectivity by insulating steam traps, valves, and boiler piping, demonstrating measurable therm savings and operational cost reductions through bespoke insulation solutions.
Expanding Use of Lightweight Materials in Automotive and Aerospace
Vehicle and aircraft manufacturers seek lightweight insulation to reduce fuel consumption, improve cabin comfort, and meet emission reduction targets. Aerogel composites, polystyrene foams, and fiberglass mats provide effective thermal and acoustic insulation without adding significant mass. Electric vehicle platforms also require insulation for battery systems, thermal management units, and soundproofing. Aerospace companies integrate thin, flexible insulation layers to protect components against temperature variations at altitude. With global sales of EVs and lightweight vehicles growing steadily, suppliers invest in innovative solutions with high thermal resistance, low density, and moisture protection. This trend supports new opportunities for specialized insulation material producers targeting next-generation mobility platforms.
Key Trends & Opportunities
Shift Toward Sustainable and Recyclable Insulation Materials
Sustainability influences purchasing decisions as end-users prefer eco-friendly materials with low embodied carbon and recyclability. Fiberglass producers incorporate recycled glass content, while manufacturers of polystyrene and polyurethane explore bio-based resins and cleaner blowing agents. Green construction policies in Europe and North America reward low-emission insulation products, opening opportunities for suppliers with certified sustainable solutions. The market also sees rising interest in aerogels and vacuum insulated panels due to high performance at lower thickness, which supports space-saving building designs. As climate goals tighten, demand continues shifting toward materials that combine durability, energy savings, and environmental responsibility.
- For instance, Saint-Gobain UK is establishing a new stone wool manufacturing facility in Melton Mowbray, which will utilize all-electric furnaces powered by renewable energy, aiming for a net-zero carbon footprint by 2050.
Rising Investments in Smart and High-Performance Insulation Systems
Smart building trends push adoption of advanced insulation systems that integrate moisture control, thermal monitoring, and fire-resistant composites. Developers use hybrid insulation panels with layered structures to offer better protection in high-rise buildings, hospitals, and data centers. Manufacturers experiment with nanomaterials, reflective coatings, and phase-change insulation for superior energy retention. Vacuum panels and aerogels gain commercial viability as costs gradually decline. These technologies deliver thin-profile insulation with excellent thermal performance, enabling architects to reduce wall thickness while preserving energy efficiency.
- For instance, Wedge Group Limited incorporates phase-change materials in their smart insulation systems to dynamically regulate thermal energy by absorbing and releasing heat, optimizing indoor climate control.
Key Challenges
High Material Costs and Limited Awareness in Developing Regions
Advanced insulation materials often carry higher upfront costs than traditional alternatives, slowing adoption in price-sensitive markets. Many builders in emerging regions continue using low-cost fiberglass or conventional foam products, despite lower long-term savings. Limited awareness of lifecycle cost benefits and energy rebates further reduces uptake. The lack of skilled installation professionals can also result in performance losses, discouraging contractors. To overcome this barrier, suppliers must provide training, widen distribution networks, and offer cost-effective product lines suited for mass construction. Incentives and education programs will play an important role in improving adoption rates.
Performance Degradation and Moisture Sensitivity in Harsh Operating Conditions
Some insulation materials face challenges such as moisture absorption, reduced thermal resistance over time, and mechanical wear in extreme conditions. Polystyrene and polyurethane can degrade under prolonged UV exposure, while mineral wool may lose effectiveness if improperly sealed. Industrial sites with high temperatures, humidity, or chemical exposure require specialized designs and protective cladding, adding installation complexity. Failures in insulation systems can lead to energy loss, corrosion under insulation (CUI), and safety risks. Manufacturers respond by developing composite barriers and hydrophobic coatings, but the need for technical expertise and precise installation remains a challenge for many end-users.
Regional Analysis
North America
North America dominates the Advanced Insulation Material market with a 34% share, supported by strict building energy codes and high adoption in commercial and industrial applications. The U.S. leads demand due to large-scale construction, data centers, and petrochemical plants requiring high-performance fiberglass, mineral wool, and polyurethane foams. Retrofitting of aging residential structures also boosts sales. Government incentives for energy-efficient buildings further encourage replacement of outdated insulation. The growing penetration of EVs and lightweight vehicles supports advanced insulation in automotive applications. Manufacturers expand capacity and launch sustainable product lines to meet rising customer expectations.
Europe
Europe holds a 28% share, driven by strong sustainability targets, green building certifications, and carbon-neutral construction mandates. Countries including Germany, the U.K., and France lead adoption of fiberglass, mineral wool, and vacuum insulation panels for residential and commercial projects. Demand rises in industrial settings as manufacturers upgrade insulation to reduce thermal losses and comply with emission rules. The region’s focus on recyclable materials and low-carbon alternatives accelerates the use of bio-based and recycled content insulation. Continuous innovation in aerogels and thin-profile insulation supports space-efficient architectural designs and high-performance refurbishments across urban centers.
Asia-Pacific
Asia-Pacific commands a 25% share and remains the fastest-growing region due to rapid urbanization, rising power consumption, and large infrastructure projects. China, India, Japan, and South Korea invest heavily in commercial buildings, industrial plants, and HVAC systems that require efficient thermal control. Manufacturers increase production of fiberglass, polyurethane foam panels, and polystyrene insulation to meet high construction volumes. Growth in data centers, cold storage, and electronics manufacturing fuels demand for advanced thermal protection. Favorable government policies promoting energy-efficient buildings and expansion of renewable-powered industries continue to support sustained market expansion.
Middle East & Africa
The Middle East & Africa region holds a 7% share, supported by demand from commercial real estate, oil and gas processing, and district cooling networks. Hot climate conditions make thermal insulation critical for energy-efficient HVAC systems in malls, hotels, hospitals, and high-rise buildings. Industrial consumers use mineral wool and polyurethane insulation for pipelines, boilers, and refineries to reduce energy loss. Construction of smart cities and free-trade zones further accelerates use of high-performance materials. Although adoption remains lower than other regions, government energy codes and rising electricity costs are increasing usage across major urban markets.
Latin America
Latin America accounts for a 6% share, led by Brazil, Argentina, and Chile where construction and industrial end-users adopt advanced insulation to enhance energy efficiency and lower operating costs. Hot and humid conditions increase demand for moisture-resistant polystyrene and polyurethane panels in residential and commercial projects. Industrial sectors, including petrochemicals, food processing, and power generation, integrate mineral wool and high-temperature insulation to reduce thermal losses. Although economic fluctuations have limited large-scale investments, modernization of urban buildings and the growth of domestic manufacturing support steady market penetration of advanced insulation solutions.
Market Segmentations
By Type
- Fiberglass
- Polyurethane
- Polystyrene
- Mineral Wool
By Application
- Building & Construction
- Industrial Applications
- HVAC Systems
- Automotive
By End-User
- Residential Sector
- Commercial Sector
- Industrial Sector
- Energy Sector
By Density
- Low-Density Insulation
- Medium-Density Insulation
- High-Density Insulation
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Advanced Insulation Material market is characterized by strong participation from global chemical producers, insulation specialists, and high-performance material manufacturers. Key players include BASF SE, UBE Industries Ltd., Johns Manville Corporation, Aspen Aerogels Inc., Armacell International S.A., Nitto Denko Corporation, and AIR-CELL. These companies compete on product performance, thermal efficiency, fire resistance, and sustainability. Manufacturers invest in R&D to develop thinner, lightweight, and recyclable insulation that meets new energy-efficiency standards in construction, industrial processes, and HVAC systems. Strategic partnerships with builders, automotive OEMs, and industrial clients enhance adoption across large infrastructure and manufacturing facilities. Many suppliers expand production capacity in Asia-Pacific and Europe to address rising construction and industrial demand. Certifications, green building compliance, and advanced manufacturing technologies such as aerogel production and vacuum insulation panel design help leading companies differentiate their portfolios and strengthen market presence globally.
Key Player Analysis
- Aspen Aerogels, Inc.
- MASTERGLASS
- Armacell International S.A.
- YUBASE
- BASF SE
- Jrgens GmbH
- Nitto Denko Corporation
- AIR-CELL
- Johns Manville Corporation
- UBE Industries, Ltd.
Recent Developments
- In November 2025, Arsenal Capital Partners completed the acquisition of ThermoSafe, a global leader in bio‑based insulation materials and thermal solutions.
- In October 2025, TopBuild Corp announced the acquisition of Specialty Products & Insulation (SPI), a provider of mechanical insulation and spray‑foam insulation solutions, for approximately US$1 billion.
- In 2024, Recticel Group completed the acquisition of REX Panels & Profiles, enhancing its insulation panel business across Europe
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Density and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as governments enforce stricter energy-efficiency and green building standards.
- Adoption will grow in retrofitting projects as older buildings replace outdated insulation.
- Automotive and aerospace sectors will increase use of lightweight and high-temperature materials.
- Aerogel and vacuum insulation panels will gain share due to thin profiles and high performance.
- Manufacturers will invest in recyclable and bio-based insulation to meet sustainability goals.
- Smart insulation systems with moisture and temperature control will see wider commercial use.
- Industrial applications will expand as plants upgrade pipelines, turbines, and process equipment.
- Asia-Pacific will remain the fastest-growing region due to rapid urban development.
- Costs will decline gradually as production capacity increases and technologies scale.
- Partnerships between material suppliers and construction firms will accelerate adoption in large projects.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Advanced Insulation Material market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Advanced Insulation Material market projected to grow between 2025 and 2032?
Which Advanced Insulation Material market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Advanced Insulation Material market?
Who are the leading companies in the Advanced Insulation Material market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Advanced Insulation Material Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Advanced Insulation Material Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.8 Billion → 2032: USD 5.27 Billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Advanced Insulation Material Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Advanced Insulation Material Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Advanced Insulation Material Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Advanced Insulation Material Market Drivers
- 3.3 Advanced Insulation Material Market Restraints & Challenges
- 3.4 Advanced Insulation Material Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Advanced Insulation Material Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Advanced Insulation Material Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Advanced Insulation Material category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Advanced Insulation Material Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Advanced Insulation Material Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Advanced Insulation Material. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Advanced Insulation Material Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Advanced Insulation Material Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Advanced Insulation Material Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Advanced Insulation Material (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Advanced Insulation Material
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Advanced Insulation Material Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Advanced Insulation Material Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Advanced Insulation Material Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Advanced Insulation Material Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Advanced Insulation Material Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Advanced Insulation Material Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Advanced Insulation Material Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Advanced Insulation Material Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
