
Access to cath labs, not incidence, now limits demand
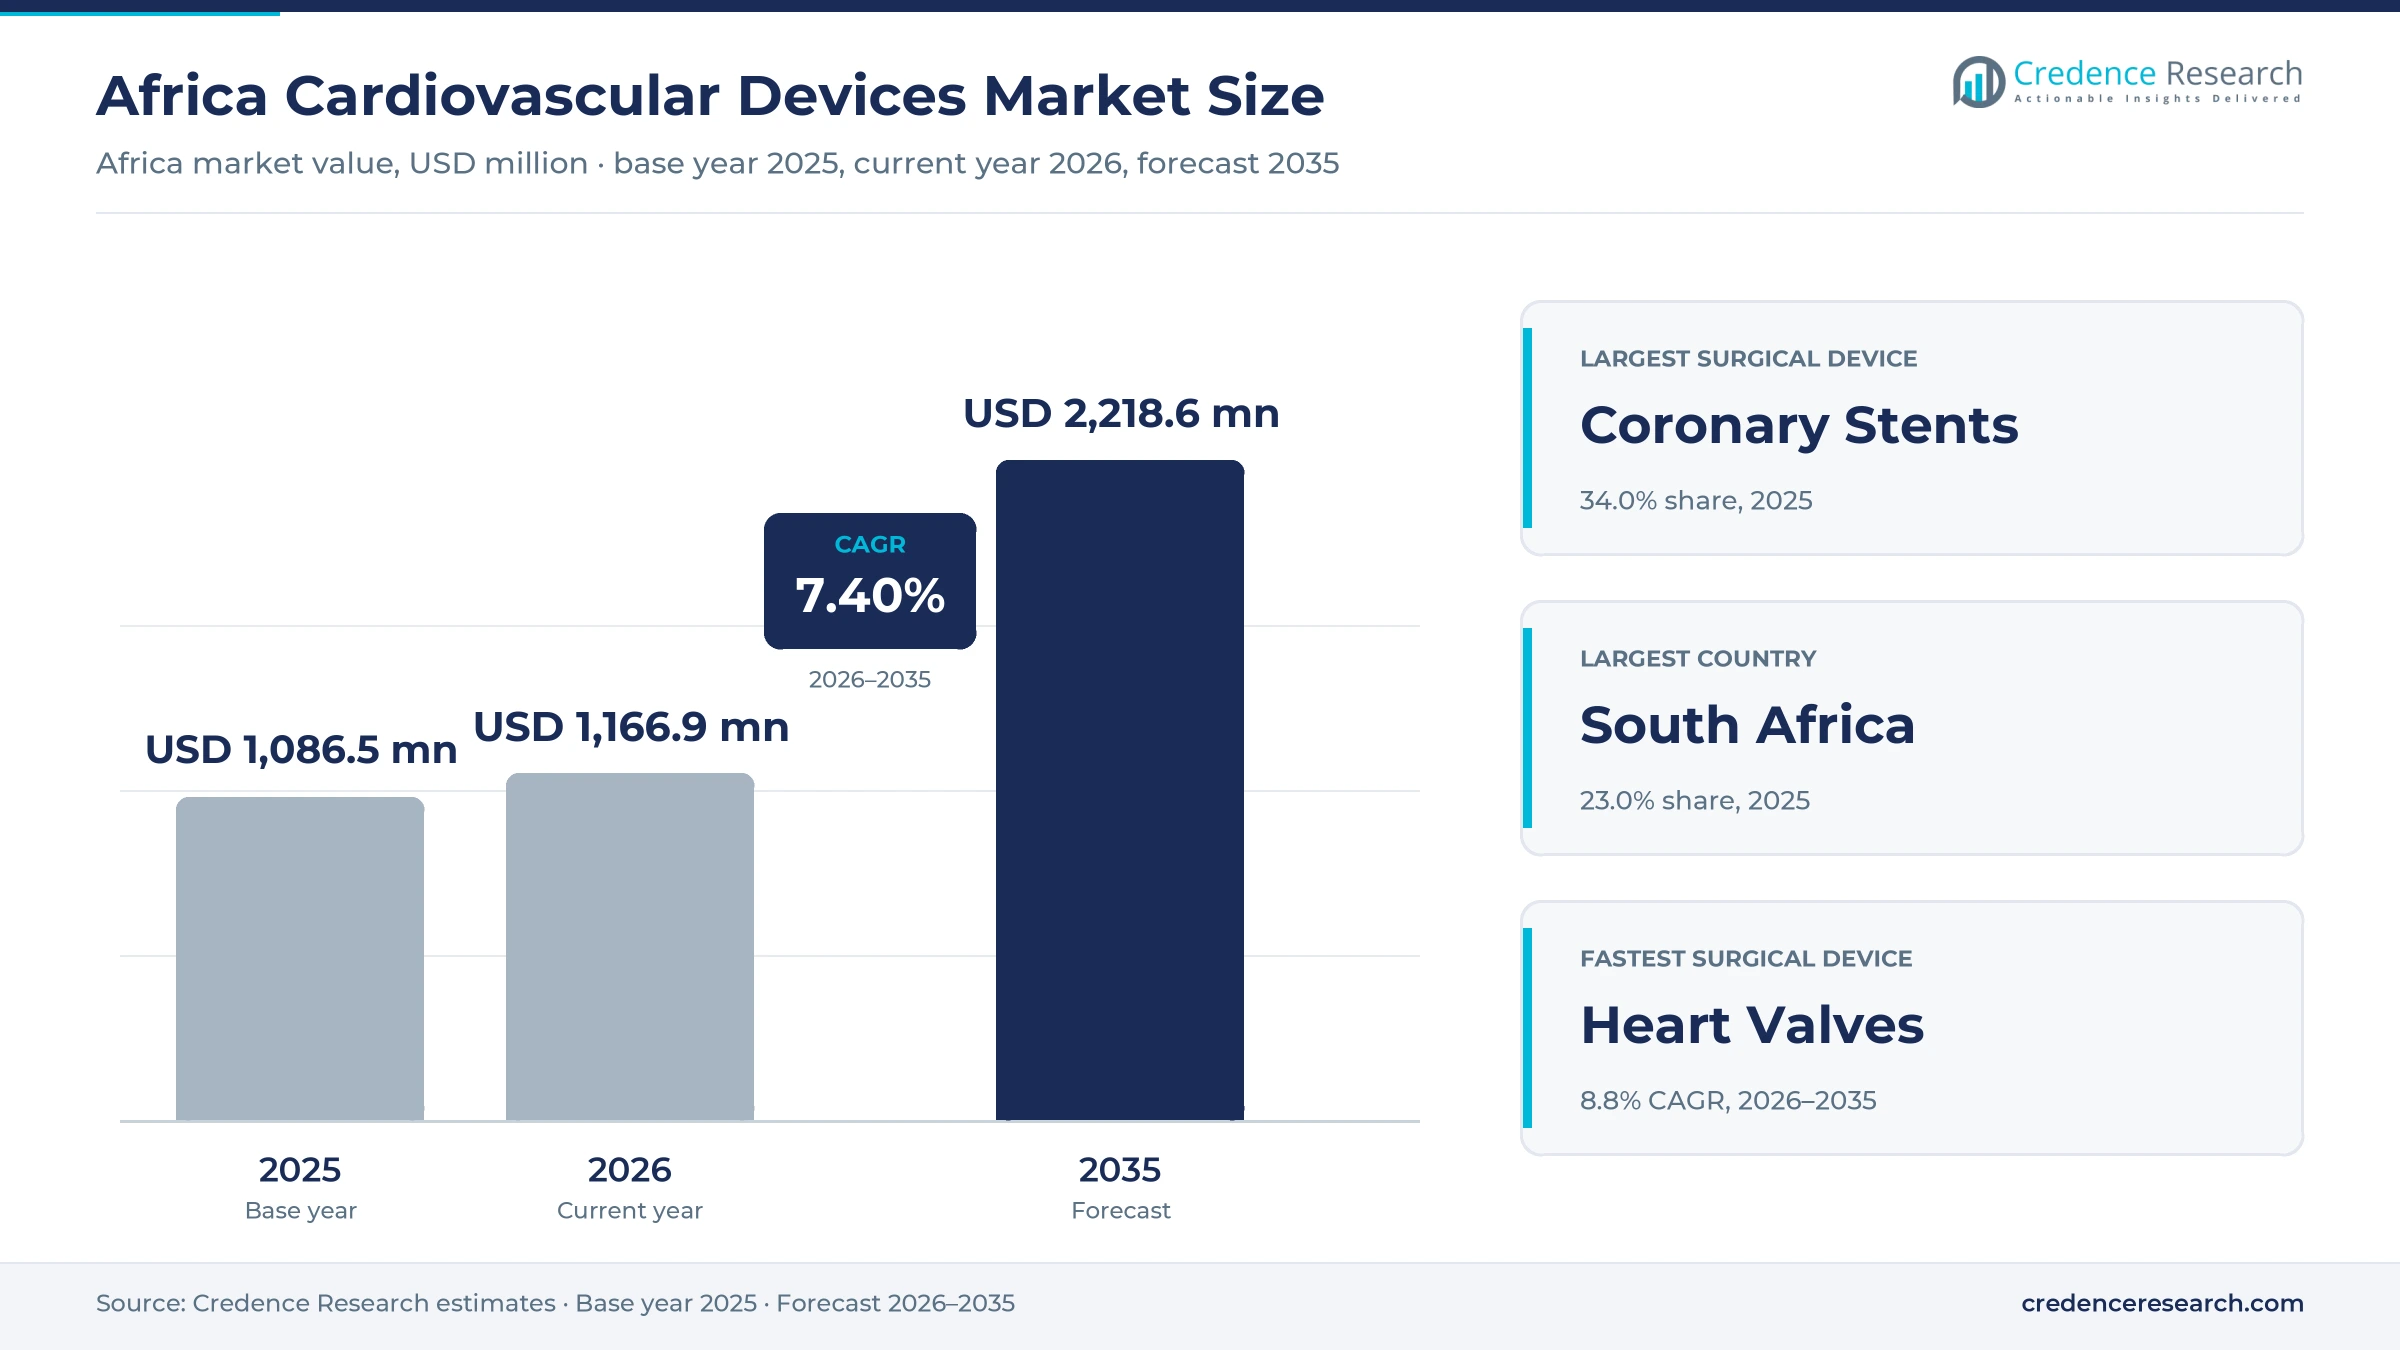
The Africa cardiovascular devices market was valued at USD 1.09 billion in 2025 and is projected to increase from USD 1.17 billion in 2026 to USD 2.22 billion by 2035, registering a CAGR of 7.40% during 2026–2035. Demand comes from public and private hospitals that treat ischemic heart disease, the leading cause of death on the continent, with ECG and imaging equipment, coronary stents, catheters, pacemakers and heart valves, and from cardiology clinics that buy monitoring devices. South Africa held the largest single-country share, 23.0% in 2025, because its private hospital groups and medical schemes fund most of the premium implant procedures performed in Africa. Egypt is the fastest-growing country at 8.2% a year, as the Universal Health Insurance System moves into its second phase of governorates. The main commercial change is the spread of cath labs into public hospitals outside capital cities, from Dar es Salaam to Agadir, which turns patients once referred abroad into local device demand.
Implants, catheters and cardiac diagnostics bought by hospitals
The estimate covers coronary stents, interventional and electrophysiology catheters, pacemakers, implantable cardioverter defibrillators, cardiac resynchronization devices, heart valves and structural heart implants, and diagnostic and monitoring equipment such as ECG systems, Holter monitors, telemetry, implantable cardiac monitors and the cardiac share of MRI. Each device is counted once at the price paid by the hospital, clinic, laboratory or patient.
The estimate excludes cardiovascular drugs, physician fees and consumer wearables sold without a medical purpose. The value chain runs from multinational manufacturers and a small number of local assemblers through South African subsidiaries, regional distributors and importers to public hospitals, central procurement agencies, private hospital groups, medical schemes and national insurers, which pay through tenders, reference prices and fixed procedure packages.
Africa Cardiovascular Devices Market Insights
- The Africa cardiovascular devices market was valued at USD 1.09 billion in 2025 and is projected to reach USD 2.22 billion by 2035, registering a CAGR of 7.40% during 2026–2035.
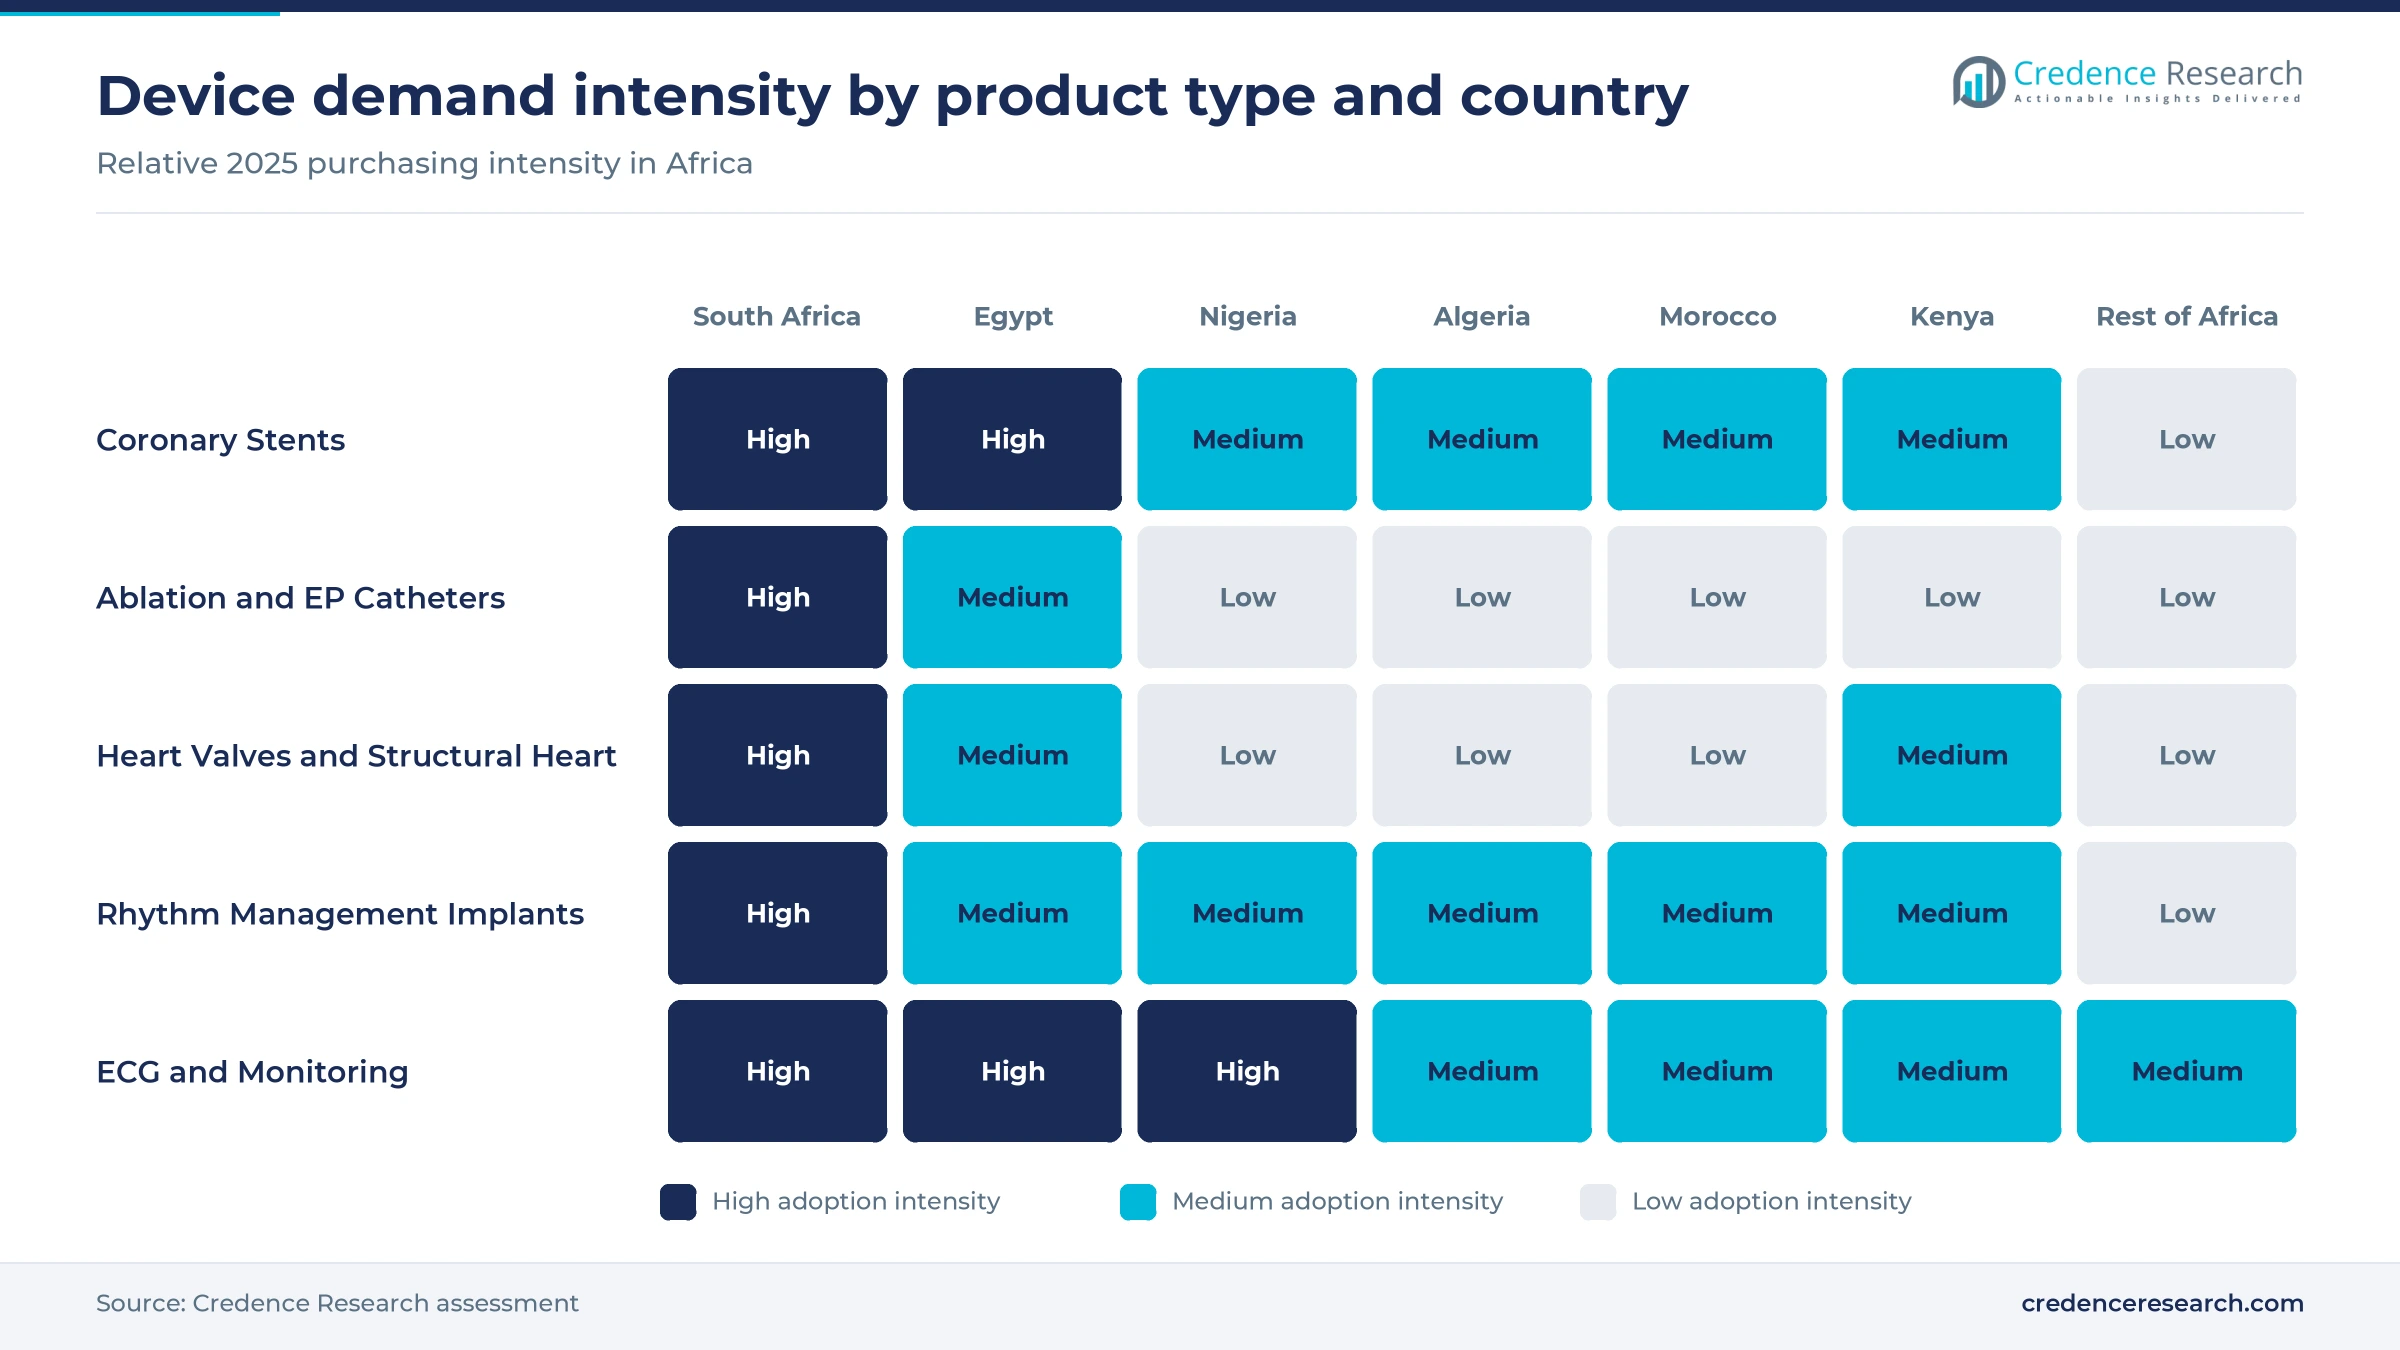
- South Africa held 23.0% of 2025 value, because private hospital groups and medical schemes there fund most premium implant procedures on the continent.
- Diagnostic and monitoring devices led product types with 52.0% of 2025 value, since every hospital buys ECG, monitoring and imaging equipment, while implants need a cath lab.
- Ischemic heart disease caused about 801,000 deaths in Africa in 2023, up 150.7% since 1990, according to GBD 2023 estimates in The Lancet Global Health.
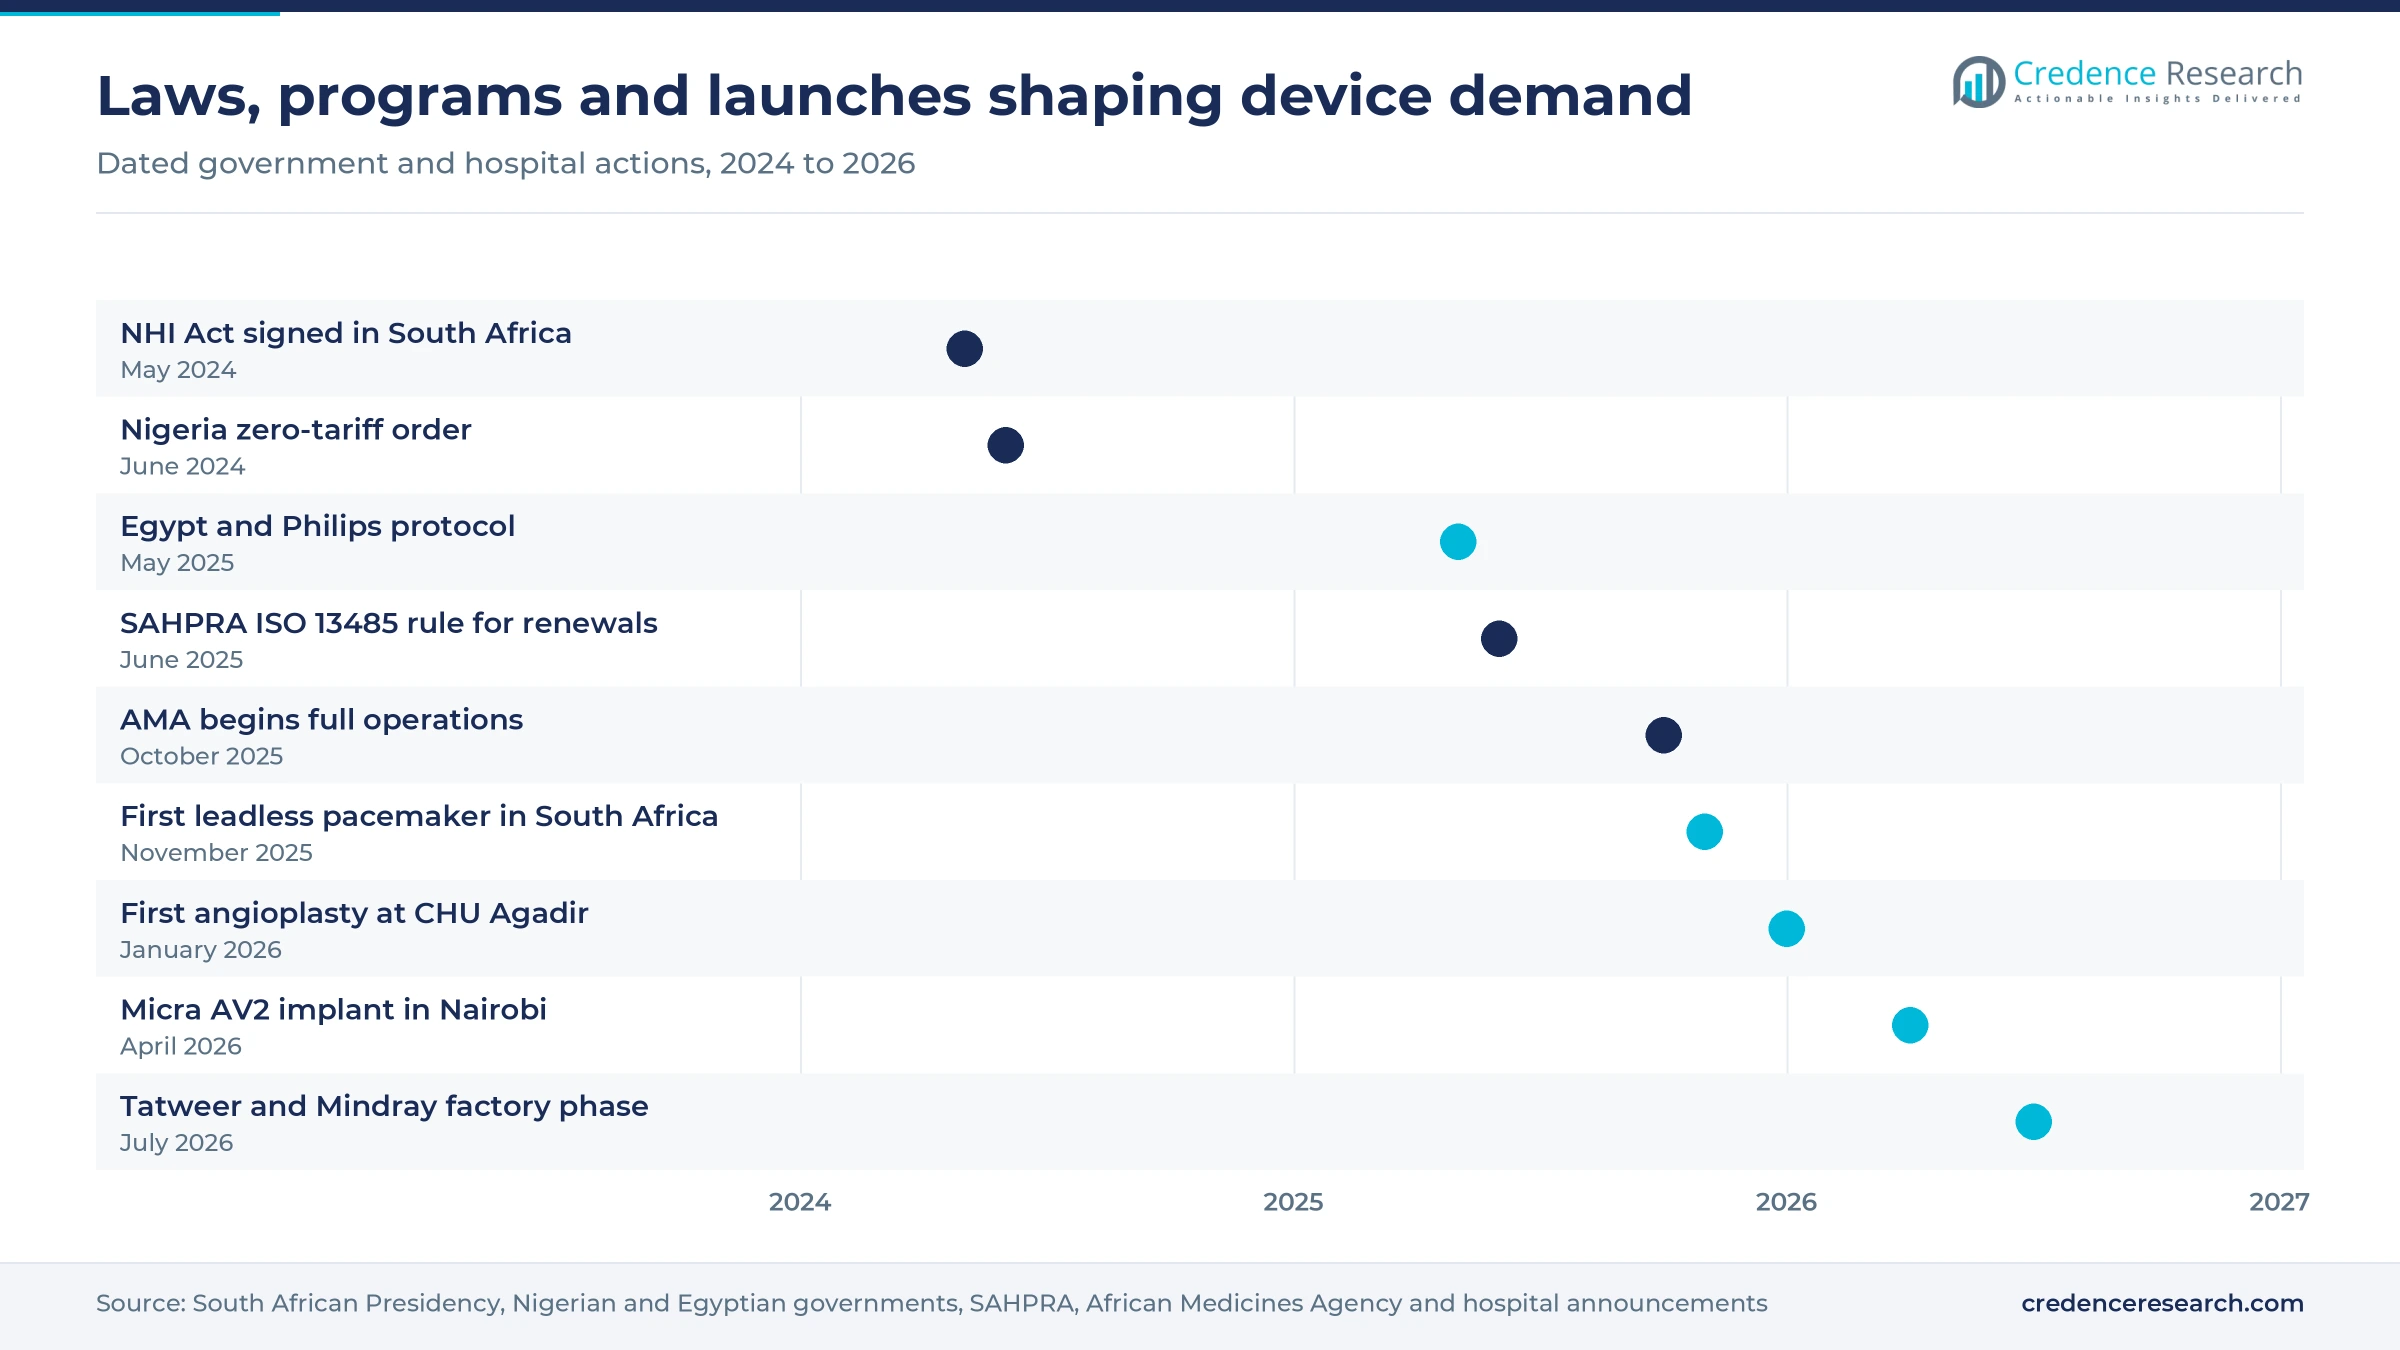
- South Africa recorded its first leadless pacemaker implant in November 2025, and Aga Khan University Hospital in Nairobi reported a Medtronic Micra AV2 implant in April 2026.
Diagnostics lead while heart valves grow fastest
Why do diagnostic devices take the larger share?
Based on product, the market is categorized into diagnostic and monitoring devices and surgical devices. Diagnostic and Monitoring Devices led with 52.0% of 2025 value, because every hospital that sees cardiac patients buys ECG, monitoring and imaging equipment, while implants need a cath lab, and most regional hospitals have ECG carts and monitors but no catheterization laboratory. Surgical Devices grow fastest at 7.8% a year, as new public programs add procedure capacity, with the Jakaya Kikwete Cardiac Institute in Tanzania performing 2,577 minimally invasive procedures in 2025, up from 330 in 2015.
ECG leads as rhythm programs lift telemetry demand
Based on diagnostic and monitoring device type, the market is categorized into ECG, implantable cardiac monitors, Holter monitors, mobile cardiac telemetry, MRI and others. ECG led with 34.0% of 2025 value, because the resting ECG is the first test in every chest pain and hypertension workup, and about 12% of people with hypertension in the African region have it under control, the WHO regional office says. Mobile Cardiac Telemetry grows fastest at 9.0% a year, because new ablation and leadless pacing programs need ambulatory rhythm monitoring before and after each procedure, although no public data on telemetry purchases exist, so this rate is a Credence Research estimate.
Scheme stent lists keep coronary stents in front
Based on surgical device type, the market is categorized into cardiac resynchronization therapy, implantable cardioverter defibrillators, pacemakers, coronary stents, catheters and heart valves and structural heart devices. Coronary Stents led with 34.0% of 2025 value, because stenting is the default treatment for blocked coronary arteries, and the 2026 TFG Medical Aid Scheme stent guide lists six preferred drug-eluting stent suppliers, including Medtronic, BIOTRONIK and B. Braun. Heart Valves and Structural Heart Devices grow fastest at 8.8% a year, as transcatheter valve procedures at 18 South African centers rose from 103 in 2014/15 to 540 in 2022, the SHARE-TAVI registry shows.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Diagnostic and Monitoring Devices | 52.0% | Surgical Devices | 7.8% |
| By Diagnostic and Monitoring Device Type | ECG | 34.0% | Mobile Cardiac Telemetry | 9.0% |
| By Surgical Device Type | Coronary Stents | 34.0% | Heart Valves and Structural Heart Devices | 8.8% |
Scheme reference prices and packages set spending
Prices for cardiovascular devices in Africa are set by a few large payers, medical schemes in South Africa, central procurement in Egypt and new national insurers in Kenya and Morocco, while patients pay directly in much of West Africa. South African schemes publish reference prices and preferred-supplier lists, so a supplier that wins a listing gains volume at a fixed price, and one that does not faces patient co-payments. Package payments, such as Kenya's fixed rate for heart surgery, leave hospitals to fit the device inside the fee. Currency moves change dollar margins quickly, so suppliers defend price through consignment stock, training and bundled service.
| Device or procedure | Typical price or fee | Basis |
|---|---|---|
| Drug-eluting coronary stent, TFG Health Plus reference price | R29,700 per stent | TFG Medical Aid Scheme stent guide, 2026 |
| Bare-metal coronary stent, TFG Health Plus reference price | R18,600 per stent | TFG Medical Aid Scheme stent guide, 2026 |
| Drug-eluting stent from a non-preferred supplier, TFG Health limit | R8,150 per stent | TFG Medical Aid Scheme stent guide, 2026 |
| Heart surgery package, Social Health Authority at Aga Khan University Hospital | Sh700,000 per patient | Business Daily, May 2025 |
| Heart attack admission with several procedures, private care in Nigeria | NGN 10 million to NGN 20 million | Arise News interview, September 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Insurance reform and public cath labs widen treatment
Ischemic heart disease deaths keep rising in number
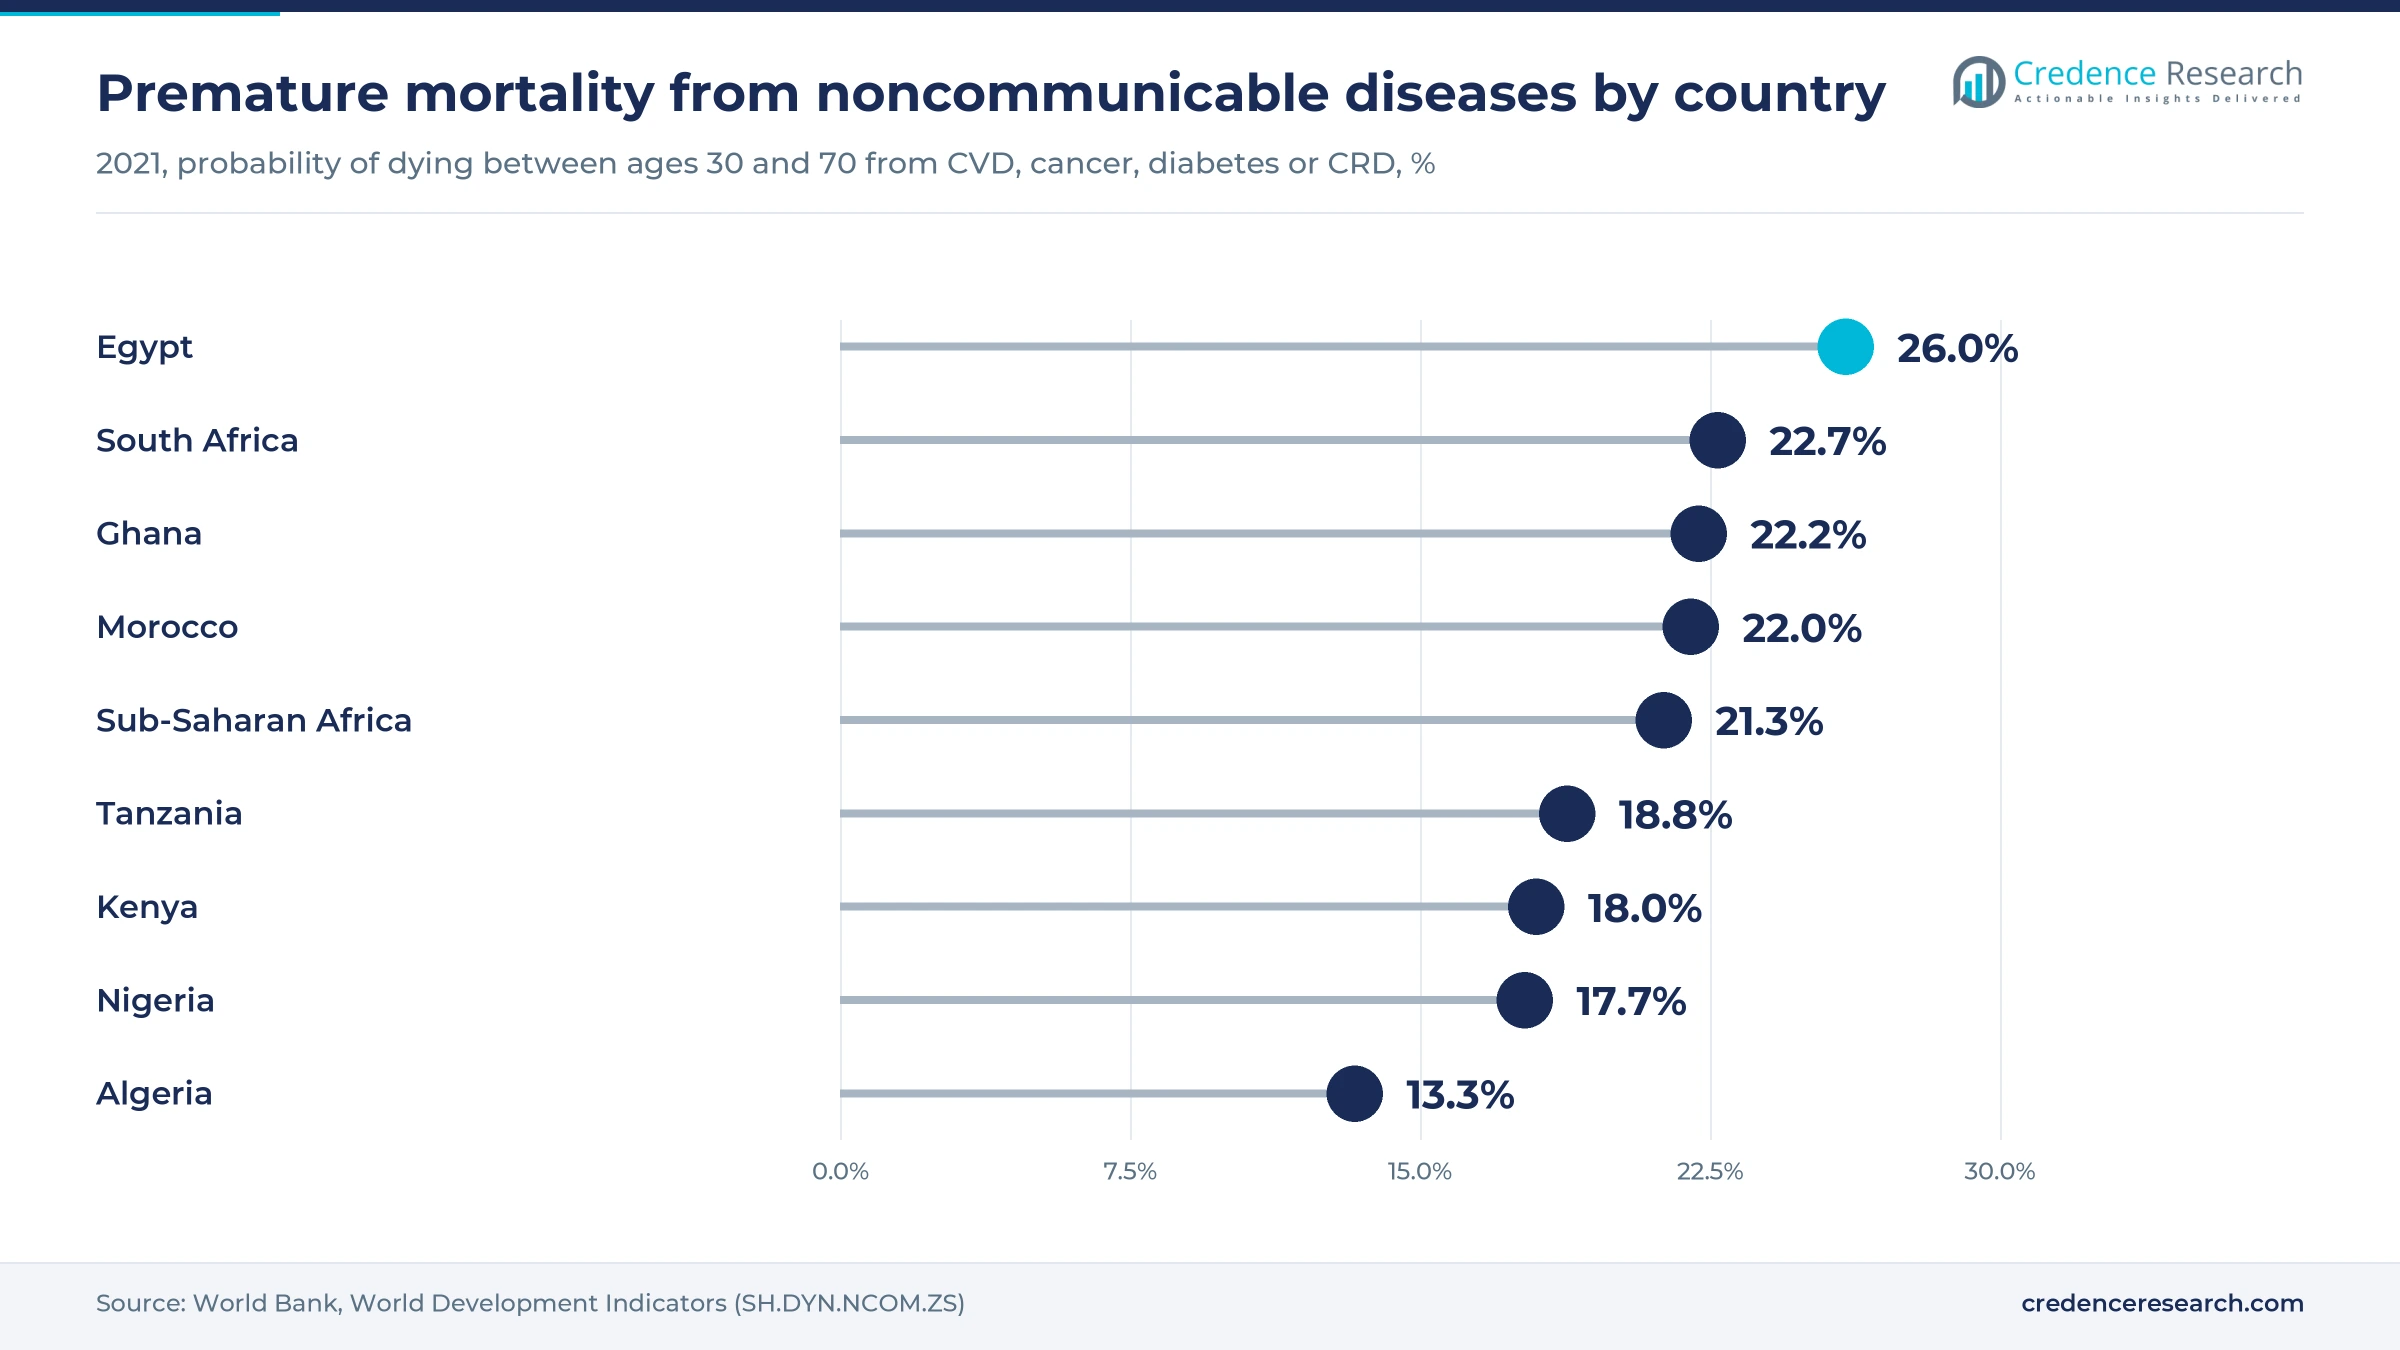
Disease burden sets the base volume for this market, because each coronary or rhythm case needs ECG testing and often a stent, catheter or implant. Ischemic heart disease caused about 801,000 deaths in Africa in 2023, up 150.7% since 1990, and was the leading single cause of death, according to GBD 2023 estimates published in The Lancet Global Health in 2026. The WHO Regional Office for Africa says fewer than a third of people with hypertension in the region receive treatment. Egypt's probability of dying from cardiovascular disease, cancer, diabetes or chronic respiratory disease between ages 30 and 70 was 26% in 2021, World Bank data show. These figures describe a treatment gap rather than saturated demand, so growth depends on access more than on incidence.
Health insurance expansion pays for more procedures
Public insurance schemes are turning cardiac need into paid procedures, because a covered patient no longer has to fund a stent or pacemaker from savings. Egypt's Universal Health Insurance System covered about six million people in six governorates in its first phase at a cost of over EGP 51 billion, and Prime Minister Mostafa Madbouly put the second phase at EGP 115 billion in February 2025, Ahram Online reported. Morocco's compulsory health insurance reached more than 32 million people, about 88% of the population, by October 2025, up from about 42% before the reform, the government portal said. In Kenya, the Social Health Authority pays Sh700,000 per patient for heart surgery at Aga Khan University Hospital under a May 2025 agreement, Business Daily reported.
Public cath labs bring treatment closer to patients
New public catheterization laboratories outside capital cities convert overseas and long-distance referrals into local procedure volume. The Jakaya Kikwete Cardiac Institute in Dar es Salaam has saved the Tanzanian government more than TZS 95 billion in overseas referral costs, Daily News reported in June 2026. The CHU Mohammed VI in Agadir reported its first coronary angioplasty in January 2026, a first for a public hospital in its region, according to the Moroccan government portal. In southern Algeria, the 240-bed Colonel Lotfi hospital in El Oued performed the region's first diagnostic and therapeutic cardiac catheterization, Algérie 360 reported in August 2025. Each new laboratory creates recurring orders for guidewires, balloons, stents and angiography systems.
Private hospital groups set the premium device tier
South Africa's private hospital groups and medical schemes fund most premium implant procedures in Africa, which gives multinational suppliers a stable early market for new devices. The SHARE-TAVI registry recorded 2,532 transcatheter valve procedures at 18 South African centers between September 2014 and December 2023, and private hospitals performed 2,251 of them, SA Heart reported. In January 2026, the Mediclinic Panorama valve team in Cape Town completed the Edwards Benchmark Program, Mediclinic said. The full registry now spans 30 centers and 3,931 patients, which shows how widely the therapy has spread among private hospitals. Suppliers use these centers to train teams and build clinical references before taking a therapy to Nairobi, Lagos or Cairo.
Leadless pacing and local assembly reshape supply
Shift toward leadless pacing and pulsed field ablation
Electrophysiologists at private centers are shifting toward catheter-delivered therapies that shorten procedures and avoid surgical pockets, creating openings for ablation catheters, generators and leadless pacemakers. Netcare Unitas Hospital in Centurion implanted South Africa's first leadless pacemaker, Abbott's AVEIR VR, in late November 2025, Netcare said. Aga Khan University Hospital in Nairobi reported implanting a Medtronic Micra AV2 leadless pacemaker in April 2026. The Mediclinic Panorama in Cape Town has treated atrial fibrillation with pulsed field ablation since February 2023. These therapies carry higher device prices than conventional pacemakers or thermal ablation, so early adopters are hospitals with insured patients, and suppliers that train local teams first gain referral networks before competitors arrive.
Rise of device localization deals in Egypt and Nigeria
Governments are shifting procurement toward locally assembled equipment to cut import bills, creating openings for multinationals that license production to domestic partners. Egypt's Ministry of Health and Population signed a protocol with Philips on May 27, 2025 to study local production of medical devices and components, with the Unified Procurement Authority attending, Ahram Online reported. Tatweer Medical Industries, part of El Ezaby Group, plans more than USD 100 million over three years with Mindray, has invested over USD 12 million so far and lists automated external defibrillators among planned products, ME Observer reported in July 2026. Nigeria's June 2024 executive order set zero tariffs and VAT on specified health manufacturing inputs for two years, BusinessDay reported. Localization reaches imaging and monitoring first, while implants and catheters remain imported.
Opportunity in transcatheter valves for public patients
The largest open segment in structural heart care is the public patient, who rarely receives a transcatheter valve today. Public hospitals in the SHARE-TAVI registry never exceeded 50 procedures in any year between 2014 and 2023, and their share of cases fell from about one-third to about 10% by 2023, while private volumes peaked at 490 in 2022. President Cyril Ramaphosa signed the National Health Insurance Act into law on May 15, 2024, which sets up pooled public purchasing over the coming years. Valve makers with transcatheter heart valve replacement proctoring programs, such as the one completed in Cape Town in January 2026, are best placed to bid for public contracts once pooled funds reach academic hospitals, where waiting patients are already identified.
Opportunity in cath lab programs for East and West Africa
Most countries in East and West Africa still lack the catheterization capacity that a minimum standard would require, which leaves room for suppliers that help hospitals build coronary programs. A minimum standard of one cath lab per million people implies about 40 laboratories for Uganda, which ran one public laboratory, Global Heart reported. Between 2012 and 2019 that laboratory performed 3,542 procedures, including 408 percutaneous coronary interventions. In Nigeria, a heart attack patient needing several procedures can spend NGN 10 million to NGN 20 million in one admission, interventional cardiologist Yemi Johnson told Arise News in September 2026. Suppliers that bundle coronary stents with financing, consignment stock and team training can open these programs and lower the cost per case.
Imports, scheme limits and insurer deficits weigh
Import dependence exposes buyers to currency swings
Most cardiovascular devices sold in Africa are imported, so local currency weakness passes straight into hospital prices. South Africa was projected to import about USD 1.26 billion of the USD 1.43 billion of medical devices it buys in 2025, the U.S. International Trade Administration estimates. In Nigeria, Yemi Johnson said in September 2026 that 99% of the materials his team uses are imported. Hospitals whose patients pay out of pocket are most exposed, and they delay elective implants when currencies fall.
Medical scheme limits shift implant costs to patients
South African medical schemes cap what they pay for implants, which pushes co-payments onto patients and slows uptake of premium devices. Full insurer payment covered 55% of private TAVI cases in 2014/15 but only 24% in 2023, the SHARE-TAVI registry shows. On TFG Medical Aid Scheme's base option, a drug-eluting stent from a non-preferred supplier is paid only up to R8,150 in 2026, the scheme's stent guide states. Suppliers outside preferred lists lose volume unless they match the listed prices.
Insurer deficits delay payments to hospitals in Kenya
New public insurers can expand access faster than their revenue grows, which leaves hospitals waiting for payment and cautious about stocking costly implants. Kenya's Social Health Insurance Fund faced claims of Sh77.9 billion in 2024/25 against revenue of Sh55 billion, and only about 5 million of 32.2 million registered members pay premiums, The Standard reported in August 2026. Private hospitals that rely on Social Health Authority payments for cardiac cases are most exposed, and distributors face longer receivables.
Quality certification rules raise compliance costs
Registration and quality rules still differ country by country, which raises the cost of serving many small markets. SAHPRA requires device manufacturers and distributors renewing an establishment licence to submit an ISO 13485 certificate from June 1, 2025, with further phases running to April 1, 2028, the regulator states. The African Medicines Agency began full operations in Kigali in October 2025, but its announcement did not set out a role in device approvals. Smaller importers with short product lists are most exposed to these certification costs.
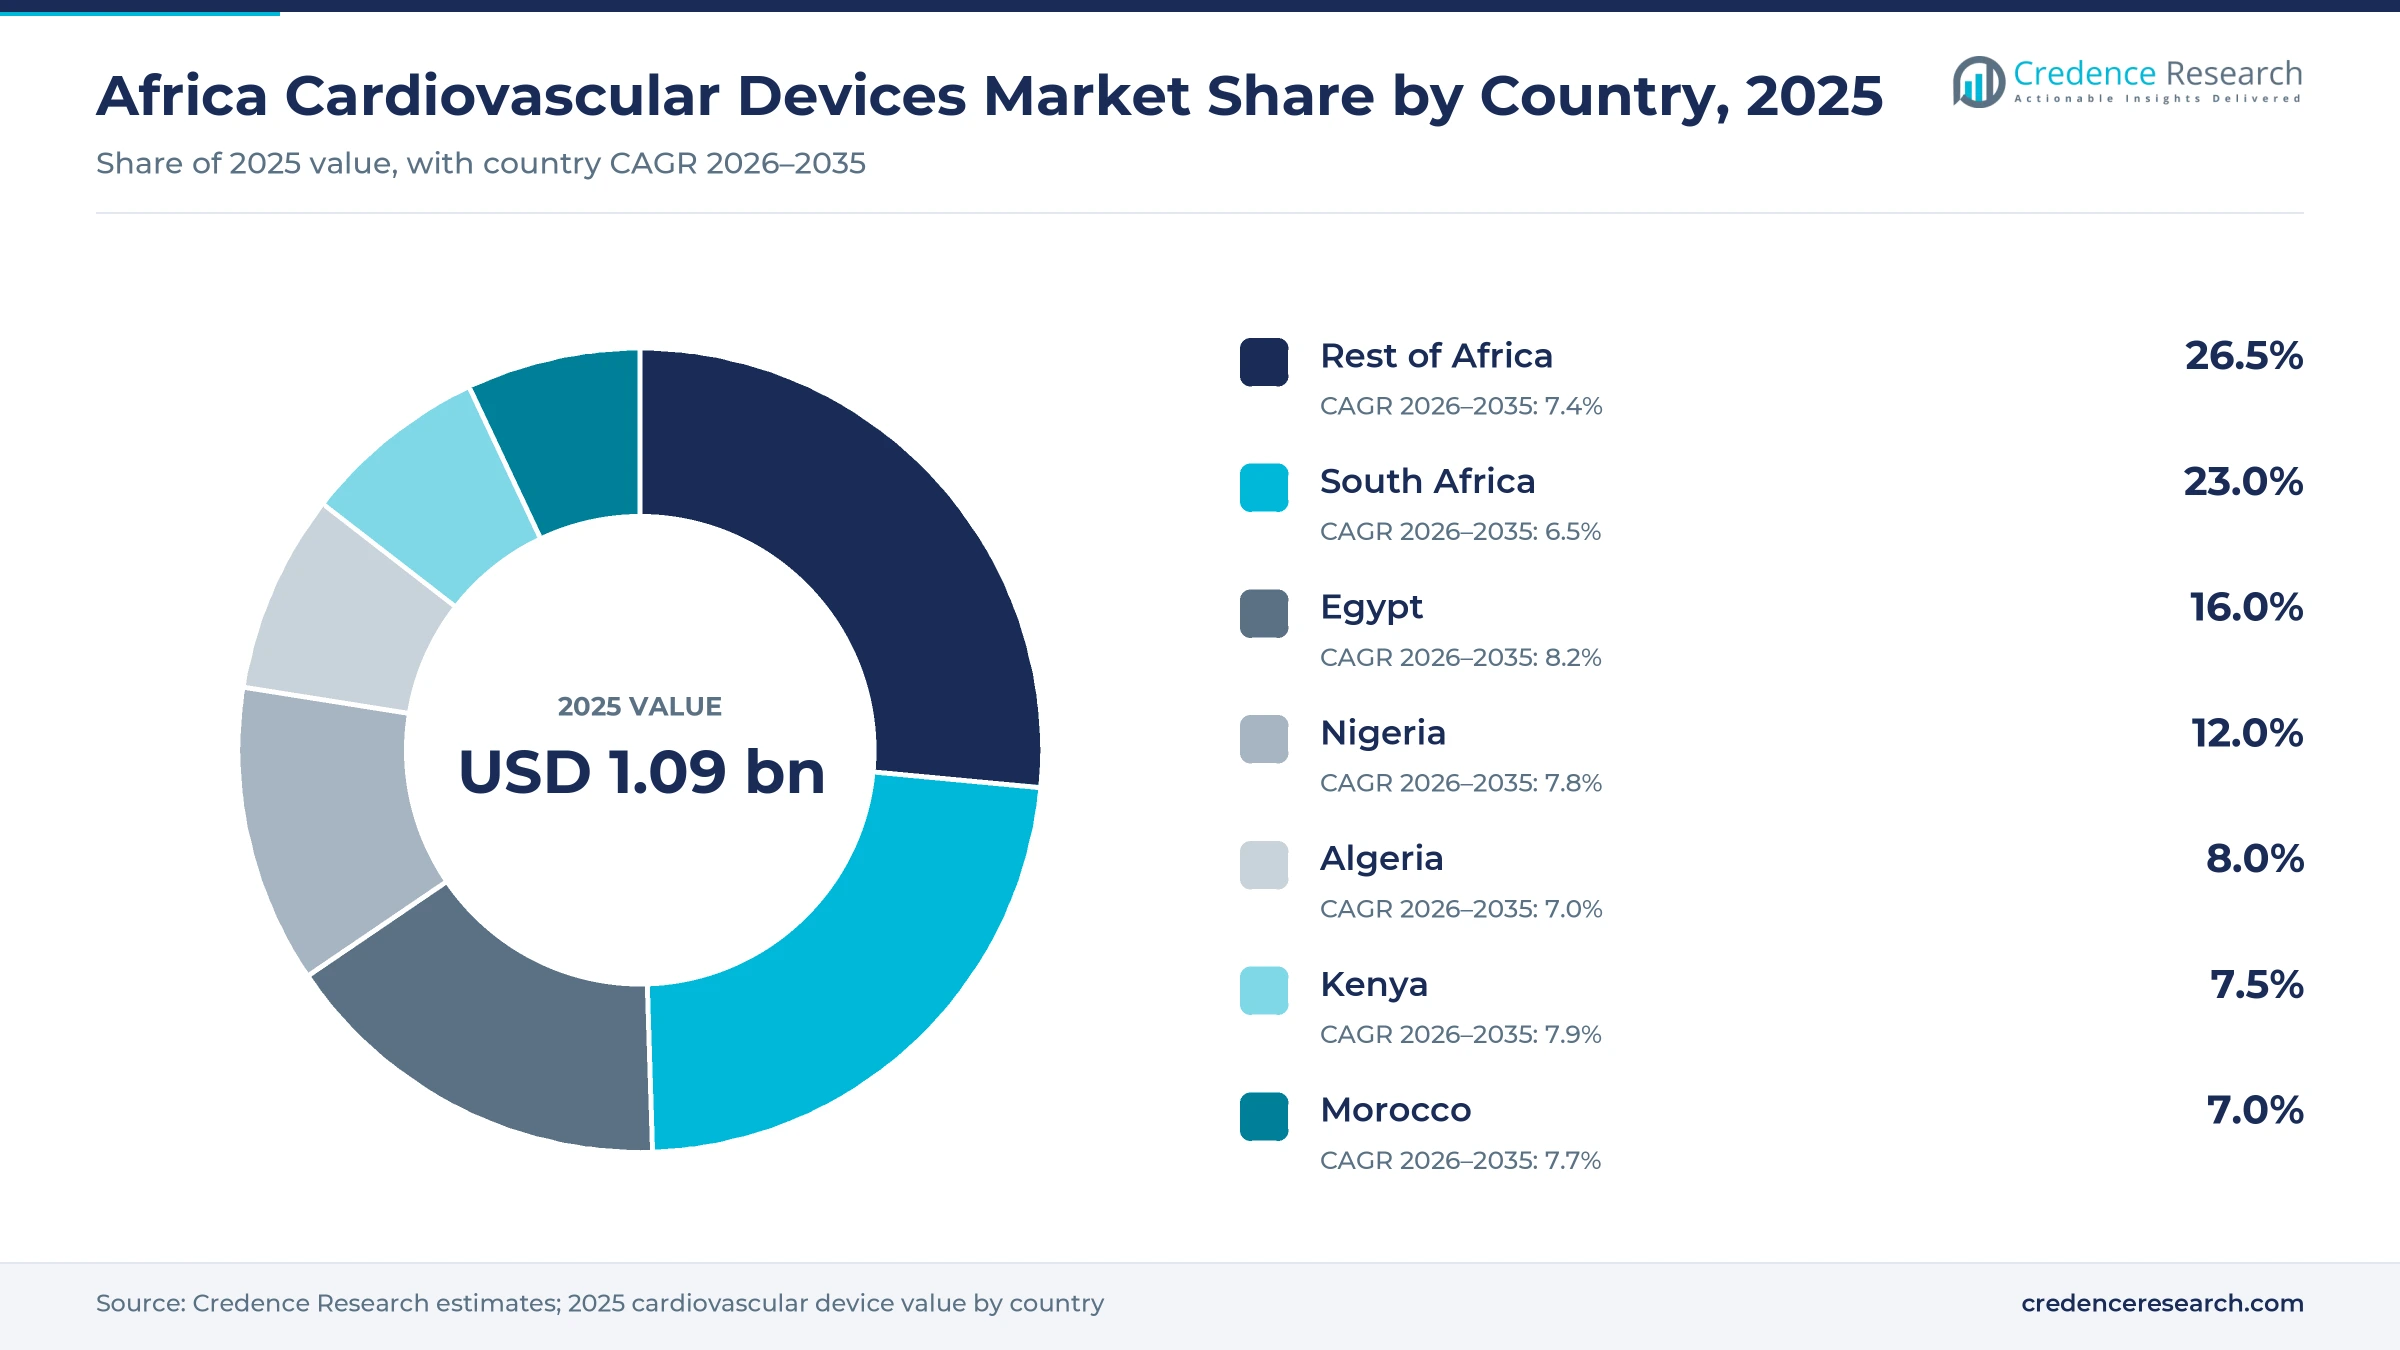
South Africa leads on value while Egypt grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Rest of Africa | 0.29 | 26.5% | 7.4% |
| South Africa | 0.25 | 23.0% | 6.5% |
| Egypt | 0.17 | 16.0% | 8.2% |
| Nigeria | 0.13 | 12.0% | 7.8% |
| Algeria | 0.09 | 8.0% | 7.0% |
| Kenya | 0.08 | 7.5% | 7.9% |
| Morocco | 0.08 | 7.0% | 7.7% |
South Africa leads on private implant spending
South Africa holds the largest single-country share, 23.0% of 2025 value, because private hospital groups such as Netcare and Mediclinic perform most of the continent's valve, ablation and leadless pacing procedures, but it grows more slowly at 6.5% a year. Medical schemes fund these cases through reference prices and preferred-supplier lists, while the insured population is small and co-payments are rising, as the registry data noted above show. The National Health Insurance Act could widen public demand over time, but its funding schedule is not yet clear.
Egypt grows fastest as public insurance spreads
Egypt grows fastest, at 8.2% a year from 16.0% of 2025 value, as its Universal Health Insurance System moves governorate by governorate and brings cardiac procedures into a paid public channel. The second phase covers Damietta, Marsa Matrouh, Kafr El-Sheikh, North Sinai and Minya, Ahram Online reported, which extends paid coverage into the Delta and Upper Egypt. Central buying through the Unified Procurement Authority favors suppliers that join localization projects such as the Philips and Mindray agreements described above.
Nigeria buys through private hospitals in Lagos and Abuja
Private hospitals in Lagos and Abuja carry Nigerian demand, which gives the country 12.0% of 2025 value and growth of 7.8% a year. Suppliers have installed modern angiography rooms there, such as the Philips Azurion system that PPC fitted at Nizamiye Hospital in Abuja, TechEconomy reported in January 2023. High out-of-pocket costs, as cited above, cap procedure volumes for most patients. The zero-tariff order on health manufacturing inputs supports local consumables, but implants and imaging systems still come from abroad.
Algeria adds public cardiology capacity
New public cardiology hospitals drive Algeria, which held 8.0% of 2025 value and grows at 7.0% a year. President Abdelmadjid Tebboune inaugurated the Omar-Boudjellab hospital for cardiology and pediatric cardiac surgery in Mahelma, west of Algiers, on July 5, 2026, APS reported. Its premature NCD mortality of 13.3% in 2021, the lowest among the larger markets here on World Bank data, means growth depends on new public capacity rather than on an untreated burden, which keeps its rate below the continental average.
Morocco converts insurance coverage into procedures
Insurance coverage is turning into procedures in Morocco, which held 7.0% of 2025 value and grows at 7.7% a year. The AMO Tadamon scheme for low-income households covers nearly 11 million people, and the state paid 25.51 billion dirhams in contributions to the CNSS through the third quarter of 2025, the government portal reported. That financing lets public university hospitals add interventional cardiology, as the Agadir angioplasty noted above shows, so suppliers gain most where new university hospitals open cath labs and buy through tenders.
Kenya keeps advanced cardiac cases at home
Advanced cardiac care that keeps patients in the country supports Kenya, which held 7.5% of 2025 value and grows at 7.9% a year. Aga Khan University Hospital in Nairobi has offered transcatheter valve replacement since 2015 and added leadless pacing in 2026. Kenyans spent an estimated Sh14.7 billion on overseas treatment in 2024, the Ministry of Health estimated, Business Daily reported, which is spending that local programs can recapture. The heart surgery package described above adds paid volume, but the insurer deficit slows payments to hospitals.
Tanzania leads new capacity in the rest of Africa
Public cardiac institutes set the pace in the rest of Africa, which held 26.5% of 2025 value and grows at 7.4% a year. Tanzania's Jakaya Kikwete Cardiac Institute reported 723 major heart surgeries in 2025 and expects more than 1,000 in 2026, so suppliers that win its tenders gain steady volume. Ghana's premature NCD mortality of 22.2% in 2021 was close to the South African level of 22.7%, World Bank data show, which points to unmet need in West Africa beyond Nigeria. Uganda's single public laboratory, noted in the opportunities section, shows how far demand can grow once financing allows more laboratories.
Implants, programs and factory plans from 2025 to 2026
| Development | Status and market relevance |
|---|---|
| In May 2025, Egypt's Ministry of Health and Population signed a cooperation protocol with Philips to localize medical device production. | Agreement signed; feasibility studies for domestic production and components |
| In November 2025, Netcare Unitas Hospital implanted South Africa's first leadless pacemaker, Abbott's AVEIR VR. | Completed procedure; opens a premium pacing segment in private hospitals |
| In January 2026, the Mediclinic Panorama TAVI team in Cape Town completed the Edwards Benchmark Program. | Program completed; strengthens the valve referral center in the Western Cape |
| In April 2026, Aga Khan University Hospital in Nairobi reported implanting a Medtronic Micra AV2 leadless pacemaker. | Completed procedure; first leadless pacing reported in Kenya |
| In July 2026, Tatweer Medical Industries reported the first phase of its Badr City factory built with Mindray complete. | First phase completed; automated external defibrillators planned for next year |
Catheter-based therapies replace open procedures
- Pulsed field ablation uses short high-voltage pulses instead of heat or cold to isolate the pulmonary veins, which shortens atrial fibrillation procedures and lowers the risk of damage to nearby tissue.
- Leadless pacing places a small capsule inside the right ventricle through a leg vein, avoiding the chest pocket and transvenous leads that cause many pacemaker infections.
- Drug-eluting stents release a drug that limits tissue regrowth inside the artery, and they remain the main product that medical schemes price through reference lists.
- Transcatheter heart valves replace a narrowed aortic valve through a catheter, which lets older patients avoid open-heart surgery and shortens hospital stays.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Multinationals lead implants as imaging localizes
Competition in the Africa cardiovascular devices market splits by therapy and by payer. Medtronic, Abbott, BIOTRONIK and Boston Scientific supply pacemakers, defibrillators and resynchronization devices, and Abbott and Medtronic introduced leadless pacemakers in South Africa and Kenya in 2025 and 2026. In coronary intervention, Medtronic, BIOTRONIK and B. Braun appear on South African scheme lists of preferred drug-eluting stent suppliers, which decide volume in private hospitals. Boston Scientific and Johnson & Johnson MedTech compete in electrophysiology catheters and mapping. Edwards Lifesciences and Medtronic lead transcatheter valves through proctoring programs at private centers. Siemens Healthineers, GE HealthCare, Royal Philips and Mindray supply angiography, MRI, ECG and patient monitoring, and Philips and Mindray have signed localization agreements in Egypt. Scheme listings, tender pricing, clinical training and distributor coverage outside major cities decide most contracts.
How concentrated is the supply side?
Supply is concentrated in implants and more open in diagnostics. Medtronic, Abbott, Boston Scientific, Edwards Lifesciences, Johnson & Johnson MedTech and BIOTRONIK sell most stents, rhythm devices, ablation catheters and valves through South African subsidiaries and regional distributors, which also handle registration in smaller markets. Entry barriers are SAHPRA and national registrations, listing on scheme preferred-supplier lists and the training that cath lab teams need. Siemens Healthineers, GE HealthCare, Philips and Mindray compete in imaging, ECG and monitoring, where localization agreements in Egypt now shape public tenders. Margins sit mainly in new-generation implants sold to private hospitals.
Implant, imaging and monitoring suppliers by role
| Company | Type | Role in the market |
|---|---|---|
| Medtronic | Full-line supplier | Stents, pacemakers including Micra, defibrillators, TAVI valves and ablation catheters |
| Abbott | Full-line supplier | AVEIR leadless pacemakers, rhythm devices, vascular and structural heart products |
| Boston Scientific Corporation | Full-line supplier | FARAPULSE pulsed field ablation, stents and rhythm management devices |
| Edwards Lifesciences Corporation | Structural heart specialist | Transcatheter and surgical heart valves with proctoring programs |
| Johnson & Johnson MedTech | Electrophysiology specialist | Ablation catheters and cardiac mapping systems |
| BIOTRONIK SE & Co. KG | Specialist | Pacemakers, defibrillators and coronary stents, a preferred stent supplier |
| B. Braun SE | Specialist | Drug-eluting coronary stents and interventional consumables |
| Siemens Healthineers | Imaging supplier | Angiography systems, cardiac MRI and CT for cath labs |
| GE HealthCare | Imaging and monitoring supplier | Cath lab imaging, cardiac MRI, ECG and patient monitoring |
| Royal Philips | Imaging and monitoring supplier | Azurion angiography, cardiac ultrasound and monitoring |
| Shenzhen Mindray Bio-Medical Electronics | Monitoring and imaging supplier | Patient monitors, defibrillators and ultrasound, with Egyptian assembly |
Financing decides growth more than disease burden
Credence Research's view is that spending on Africa cardiovascular devices is limited by financing and cath lab access, not by disease burden. Insurance reform in Egypt, Morocco and Kenya and new public laboratories in Tanzania, Morocco and Algeria are loosening those limits at different speeds. Multinational suppliers keep the advantage in valves, rhythm devices and ablation, where training and clinical references decide contracts. Imaging and monitoring suppliers gain the most where they localize production with public procurement agencies. The main risk is payer cash flow, because insurers that pay late can stall implant orders even when clinical demand is clear.
Country estimates anchor the continental total
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which replaces the earlier edition with a country build-up checked against published country device estimates, national medical device market data, insurance coverage and 2025 exchange rates. Country and segment splits are Credence Research estimates based on population, premature noncommunicable disease mortality and procedure patterns. Sources include ministries, regulators, national insurers, the World Bank, the WHO, peer-reviewed registries, company and hospital announcements and regional news media. No interviews or surveys were conducted by Credence Research for this edition.
Valves and ablation gain share of budgets to 2035
The Africa cardiovascular devices market is expected to grow from USD 1.17 billion in 2026 to USD 2.22 billion by 2035 as insurance coverage and public cath labs reach more patients. Heart valves and structural heart devices grow fastest among surgical devices at 8.8% a year as transcatheter procedures move beyond a few private centers. Mobile cardiac telemetry grows fastest in monitoring at 9.0% a year. Egypt gains share as its insurance system expands, while South Africa keeps the largest purchases. Coronary stents stay the largest surgical item but lose share to valves and ablation.
Insurer finances and cath lab funding decide the range
The spread between the cases depends on whether new public insurers in Egypt, Morocco and Kenya can pay hospitals on time and how many public cath labs open outside capital cities. Faster pooled purchasing in South Africa and wider valve access would lift value, while weaker currencies and insurer deficits would hold orders down. The base case keeps the 7.40% CAGR through 2035, led by valves, catheters and monitoring.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 5.8% | USD 1.94 billion | Currencies weaken, Kenyan insurer deficits persist and Egypt slows its insurance rollout |
| Base | 7.40% | USD 2.22 billion | Insurance coverage and public cath lab openings continue at their 2025 and 2026 pace |
| Upside | 8.8% | USD 2.49 billion | South African pooled funding reaches valve patients and Egypt completes its second insurance phase |
Frequently Asked Questions
How big is the Africa cardiovascular devices market?
Which country leads the market?
How large is interventional cardiology within the market?
How large is the burden of ischemic heart disease in Africa?
Which product type has the largest share?
Which cardiac therapies are gaining ground?
What are the main challenges for suppliers?
Who are the leading suppliers in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Diagnostic and Monitoring Devices
- 1.2.2 Surgical Devices
- 1.3 By Diagnostic and Monitoring Device Type
- 1.3.1 ECG
- 1.3.2 MRI
- 1.3.3 Holter Monitors
- 1.3.4 Mobile Cardiac Telemetry
- 1.3.5 Implantable Cardiac Monitors
- 1.3.6 Others
- 1.4 By Surgical Device Type
- 1.4.1 Coronary Stents
- 1.4.2 Catheters
- 1.4.3 Pacemakers
- 1.4.4 Implantable Cardioverter Defibrillators (ICDs)
- 1.4.5 Cardiac Resynchronization Therapy (CRT)
- 1.4.6 Heart Valves and Structural Heart Devices
- 1.5 By Country
- 1.5.1 South Africa
- 1.5.2 Egypt
- 1.5.3 Nigeria
- 1.5.4 Algeria
- 1.5.5 Morocco
- 1.5.6 Kenya
- 1.5.7 Rest of Africa
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.09 billion → 2035: USD 2.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Africa Cardiovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Africa Cardiovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Africa Cardiovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Africa Cardiovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Africa Cardiovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Africa Cardiovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Africa Cardiovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Africa Cardiovascular Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.09 billion → 2035: USD 2.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Africa Cardiovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diagnostic and Monitoring Devices
- 12.3.7.2 Surgical Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diagnostic and Monitoring Device Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ECG
- 12.4.7.2 MRI
- 12.4.7.3 Holter Monitors
- 12.4.7.4 Mobile Cardiac Telemetry
- 12.4.7.5 Implantable Cardiac Monitors
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Surgical Device Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Coronary Stents
- 12.5.7.2 Catheters
- 12.5.7.3 Pacemakers
- 12.5.7.4 Implantable Cardioverter Defibrillators (ICDs)
- 12.5.7.5 Cardiac Resynchronization Therapy (CRT)
- 12.5.7.6 Heart Valves and Structural Heart Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 South Africa
- 12.6.7.2 Egypt
- 12.6.7.3 Nigeria
- 12.6.7.4 Algeria
- 12.6.7.5 Morocco
- 12.6.7.6 Kenya
- 12.6.7.7 Rest of Africa
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Africa Cardiovascular Devices Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Country-Level Shares, 2025
- 13.2 Country Market Size Comparison, 2025
- 13.3 Country Market Forecasts, 2025-2035
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Africa Cardiovascular Devices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Africa Cardiovascular Devices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Medtronic
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Abbott
- 17.4 Boston Scientific Corporation
- 17.5 Edwards Lifesciences Corporation
- 17.6 Johnson & Johnson MedTech
- 17.7 BIOTRONIK SE & Co. KG
- 17.8 B. Braun SE
- 17.9 Siemens Healthineers
- 17.10 GE HealthCare
- 17.11 Royal Philips
- 17.12 Shenzhen Mindray Bio-Medical Electronics
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

