
Market Overview
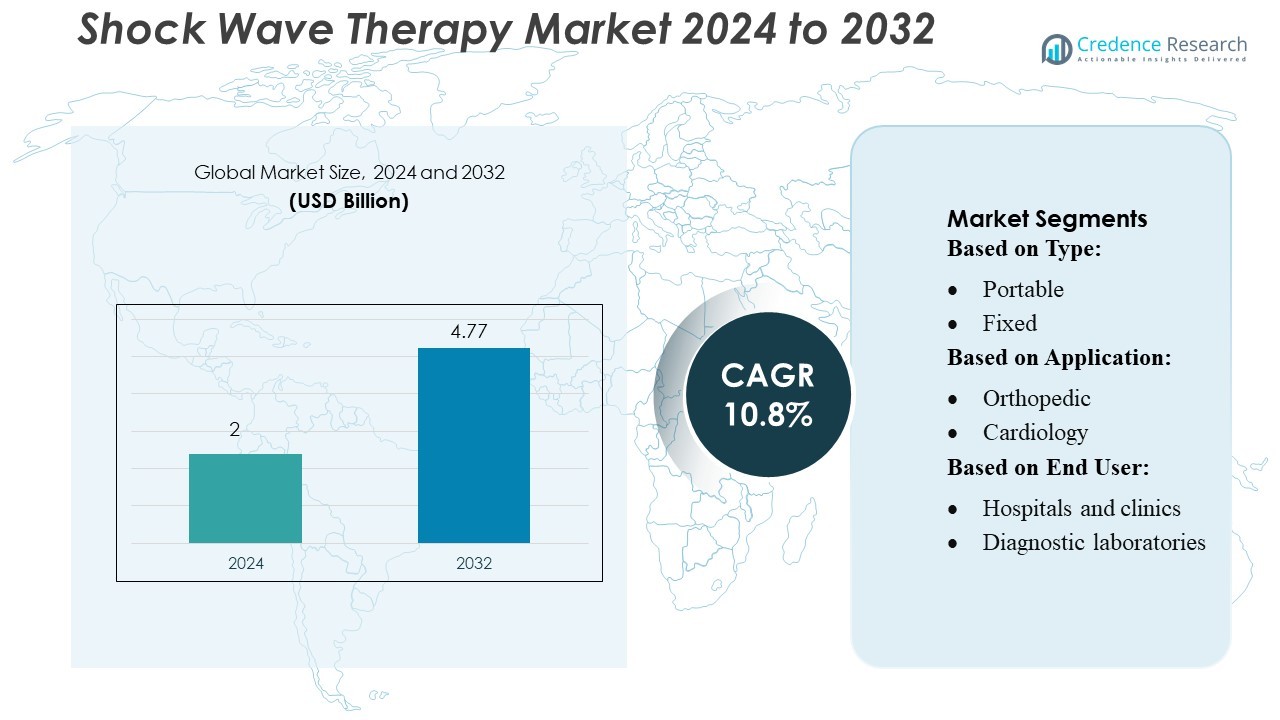
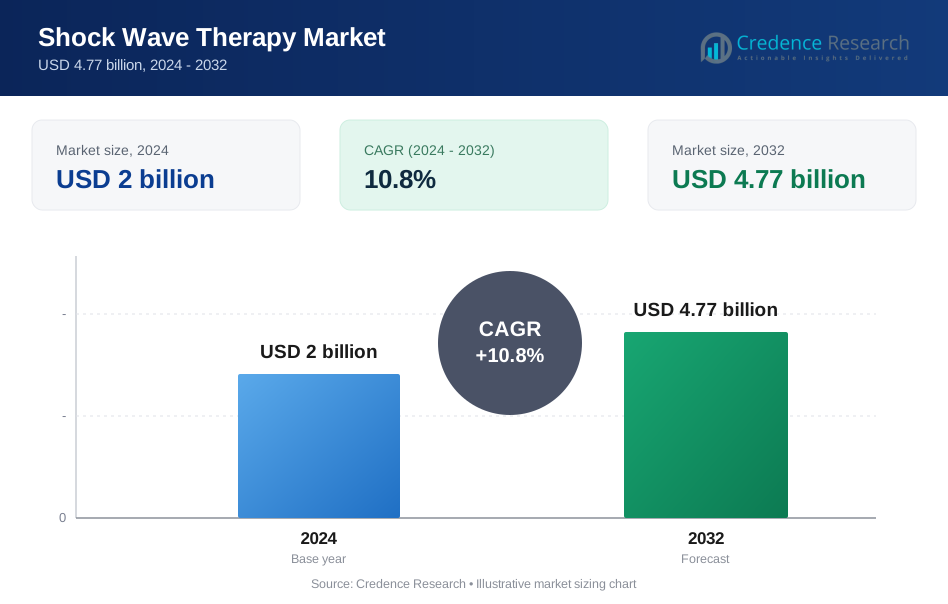
Shock Wave Therapy Market size was valued USD 2 billion in 2024 and is anticipated to reach USD 4.77 billion by 2032, at a CAGR of 10.8 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Shock Wave Therapy Market Size 2024 | USD 2 Billion |
| Shock Wave Therapy Market, CAGR | 10.8 % |
| Shock Wave Therapy Market Size 2032 | USD 4.77 Billion |
The Shock Wave Therapy Market features strong participation from leading medical device manufacturers known for advancing non-invasive treatment technologies across orthopedics, urology, and rehabilitation care. These companies compete by introducing systems with enhanced energy precision, expanded therapy modes, and integrated digital interfaces that improve clinical efficiency. Strategic initiatives-including product upgrades, global distribution expansion, and partnerships with physiotherapy and sports medicine centers-strengthen their market positioning. North America leads the global market with an estimated 35% share, supported by advanced healthcare infrastructure, high adoption of outpatient therapies, and strong utilization of both focused and radial shock wave systems across clinical settings.
Market Insights
- The Shock Wave Therapy Market was valued at USD 2 billion in 2024 and is projected to reach USD 4.77 billion by 2032, registering a CAGR of 10.8%, driven by expanding adoption of non-invasive treatments across multiple medical specialties.
- Rising musculoskeletal disorders, increasing sports injury cases, and growing demand for outpatient rehabilitation drive strong utilization of both focused and radial shock wave systems.
- Key market players enhance competitiveness through technological advancements, including improved energy precision, multimode devices, and digital interfaces that support guided therapy and analytics.
- Limited reimbursement coverage and high upfront device costs remain key restraints, slowing adoption in smaller clinics and cost-sensitive markets.
- North America leads with 35% regional share, while portable shock wave systems dominate the type segment with over 60% share, reinforced by demand from physiotherapy centers and ambulatory surgical facilities.
Market Segmentation Analysis:
By Type
Portable shock wave therapy systems dominate the market with an estimated over 60% share, driven by their ease of deployment, lower capital cost, and expanding use in outpatient rehabilitation and sports medicine centers. Their compact form factor supports point-of-care treatment and accelerates adoption in physiotherapy practices managing high patient throughput. Fixed systems retain demand in large hospitals for high-energy protocols, but growth in decentralized care models and home-based physiotherapy continues to shift preference toward portable units, strengthening their position as the leading segment.
- For instance, CARTISTEM® delivers 7.5 million mesenchymal stem cells per vial, leveraging MEDIPOST’s precise cell-handling capabilities to ensure consistent potency-a level of process control that mirrors the precision and repeatability required in portable shock-wave devices.
By Application
Orthopedic applications hold the largest share, accounting for more than 50% of the shock wave therapy market, supported by strong clinical adoption for chronic tendinopathies, plantar fasciitis, calcific shoulder conditions, and non-union fractures. Demand is propelled by rising sports injuries and the need for non-invasive alternatives to steroid injections and surgery. While urology maintains a stable base in lithotripsy procedures and cardiology sees growing use in refractory angina management, the scale and recurrence of musculoskeletal cases keep orthopedics the primary revenue contributor.
- For instance, Anterogen Co., Ltd. has demonstrated significant technical achievement with its Cupistem® product, which uses 3 × 10⁷ autologous adipose-derived mesenchymal stem cells per mL, and achieved 82% complete healing of Crohn’s fistula at week 8 and 81% sustained response at week 96, according to regulatory filings.
By End User
Hospitals and clinics lead the market with over 55% share, driven by their broad patient pool, advanced therapeutic infrastructure, and higher adoption of both high-energy and radial shock wave systems. These facilities manage complex orthopedic and urological cases, positioning them as primary centers for shock wave therapy delivery. Ambulatory surgical centers show steady growth due to increasing outpatient procedures and demand for cost-efficient care, while diagnostic laboratories hold a smaller share, largely performing assessment and referral functions rather than therapy administration.
Key Growth Drivers
- Rising Incidence of Musculoskeletal Disorders and Sports Injuries
The rapid increase in musculoskeletal conditions-such as plantar fasciitis, tendinopathies, and chronic back pain-continues to drive global demand for shock wave therapy. Growing sports participation and higher injury rates in both professional and recreational athletes accelerate utilization of non-invasive treatment options. Healthcare providers increasingly adopt shock wave therapy as a first-line alternative to corticosteroids and surgical interventions due to faster recovery timelines, minimal downtime, and reduced long-term costs, supporting steady market expansion.
- For instance, AAOS 2025, J&J showcased its VELYS™ robotic-assisted total knee system, which has supported over 100,000 knee replacement surgeries across 31 global markets.
- Expanding Adoption in Outpatient and Ambulatory Care Settings
Ambulatory surgical centers and physiotherapy clinics increasingly integrate shock wave systems to offer cost-effective, walk-in treatment options. The availability of portable, high-performance devices makes it easier for outpatient facilities to deliver therapy without large infrastructure investments. As patient volumes shift from hospital-based care to decentralized settings, demand for mobile and user-friendly shock wave equipment rises. This trend supports broader accessibility, shortens waiting periods, and improves operational efficiency, strengthening market penetration across emerging and developed regions.
- For instance, JW Therapeutics’ relmacabtagene autoleucel (Carteyva®) was supported by a treatment network that enabled over 200 patients to be treated across certified infusion centers demonstrating the scalability of advanced therapies outside large hospitals.
- Growing Clinical Validation and Technological Advancements
Increasing clinical evidence supporting the therapeutic efficacy of focused and radial shock wave systems boosts clinician confidence and reimbursement potential. Manufacturers continue to introduce devices with enhanced energy precision, improved penetration depth, and integrated digital interfaces for better treatment tracking. Advances such as multi-mode systems and AI-supported therapy optimization contribute to improved patient outcomes. These innovations enable broader usage in orthopedics, urology, cardiology, and wound care, ultimately accelerating market growth.
Key Trends & Opportunities
1. Increasing Integration of Digital Monitoring and Smart Therapy Platforms
Manufacturers are incorporating digital tools-such as treatment analytics, guided protocols, and cloud-based patient monitoring-into shock wave systems to enhance clinical efficiency. Smart interfaces allow practitioners to customize therapy parameters more precisely, improving outcomes and reducing variability in treatment results. This trend presents opportunities for companies to differentiate products through software-driven capabilities, expand service offerings, and build subscription-based digital ecosystems. Adoption of AI-driven decision support further positions the technology for long-term integration in modern rehabilitation workflows.
- For instance, S. BIOMEDICS’ TED-A9 program delivers either 3.15 million or 6.3 million dopaminergic progenitor cells per dose, derived from hESCs, and in its Phase 1/2a trial for Parkinson’s disease demonstrated cell survival and engraftment post-transplant.
2. Expanding Applications Beyond Orthopedics
While orthopedics remains the dominant segment, new opportunities emerge in dermatology, wound healing, sexual medicine, and cardiology. Studies demonstrating improved vascularization, pain reduction, and tissue regeneration broaden the therapeutic profile of shock wave systems. The introduction of devices optimized for low-intensity protocols accelerates adoption in erectile dysfunction, chronic wounds, and peripheral vascular disease. These expanding clinical indications allow manufacturers to tap into diverse patient pools and increase treatment frequency, strengthening multi-disciplinary market expansion.
- For instance, bispecific antibody pumitamig (BNT327/BMS986545), developed with BioNTech, demonstrated a 76.3% confirmed objective response rate (cORR) and a median progression-free survival of 6.8 months in a Phase 2 study of extensive-stage small cell lung cancer.
3. Rising Demand for Portable and Home-Use Devices
The shift toward patient-centric care and increased preference for non-invasive home therapies are creating opportunity for compact, portable shock wave devices. Advancements in ergonomics, energy control, and safety features support the development of consumer-grade solutions under professional guidance. As aging populations seek accessible treatment for chronic pain and mobility limitations, home-use platforms offer a scalable growth avenue for device manufacturers. This transition also enables recurring revenue models through consumables, accessories, and digital service integration.
Key Challenges
1. Limited Reimbursement and High Upfront Cost of Equipment
Despite growing clinical acceptance, reimbursement pathways remain inconsistent across regions, often categorizing shock wave therapy as an elective or adjunctive treatment. This poses challenges for providers seeking cost recovery and limits adoption in smaller clinics. High initial investment in advanced focused shock wave systems-combined with ongoing maintenance-can deter budget-constrained facilities. Limited reimbursement discourages patient uptake, prompting manufacturers and healthcare organizations to advocate for stronger clinical evidence to improve coverage policies.
2. Variability in Clinical Outcomes and Operator Dependency
Therapy effectiveness can vary significantly based on practitioner expertise, device type, and treatment protocol, creating uncertainty in clinical outcomes. Inconsistent application parameters-such as energy flux density, frequency, and number of pulses-may lead to suboptimal results and hinder provider confidence. Lack of standardized training programs exacerbates the challenge, especially in emerging markets. Addressing this requires development of unified clinical guidelines, enhanced training frameworks, and smart systems capable of assisting clinicians in delivering consistent, evidence-based therapy.
Regional Analysis
North America
North America accounts for around 35% of the global market, driven by strong adoption of non-invasive therapies across sports medicine, orthopedics, and rehabilitation centers. High prevalence of musculoskeletal disorders, advanced healthcare infrastructure, and favorable reimbursement for select shock wave indications support continued growth. The U.S. leads due to widespread use of focused and radial systems across hospitals, ambulatory surgical centers, and physiotherapy chains. Increasing investments in outpatient care and rising preference for portable, digitally enabled devices further strengthen the region’s dominant position in the global shock wave therapy market.
Europe
Europe holds approximately 30% market share, supported by strong clinical acceptance of shock wave therapy in orthopedic, urological, and rehabilitation settings. Countries such as Germany, Switzerland, and Italy demonstrate high penetration due to well-established physiotherapy practices and early regulatory acceptance of focused shock wave technologies. The region benefits from extensive R&D activities and participation in clinical studies validating new therapeutic applications. Adoption of portable systems continues to grow, driven by rising demand for home-based and outpatient treatments, solidifying Europe as a mature and technologically progressive market.
Asia-Pacific
Asia-Pacific captures about 25% of the global market, emerging as the fastest-growing region due to expanding healthcare infrastructure, rising sports injuries, and increasing awareness of non-invasive pain management therapies. China, Japan, South Korea, and India see rising utilization of shock wave systems across physiotherapy centers and hospitals. The availability of cost-effective domestic devices accelerates adoption, especially in small clinics. Growing medical tourism and investments in advanced rehabilitation technologies further amplify demand. As chronic musculoskeletal conditions increase with aging populations, APAC is expected to gain additional market share.
Latin America
Latin America represents around 6% market share, with growth driven by increasing demand for affordable non-invasive treatments and expanding physiotherapy services. Brazil, Mexico, and Argentina lead adoption, particularly in sports medicine and orthopedic clinics. Market expansion is supported by improving access to portable shock wave systems and rising investments in private healthcare facilities. However, limited reimbursement and uneven distribution of advanced technologies slower adoption in rural areas. Despite these gaps, rising awareness of regenerative therapies and growing medical tourism continue to create opportunities for manufacturers.
Middle East & Africa
The Middle East & Africa region holds approximately 4% market share, supported by gradual expansion of advanced rehabilitation and orthopedic services. Gulf countries such as the UAE and Saudi Arabia lead adoption due to investments in modern healthcare infrastructure and rising demand for sports injury management. Portable systems gain traction in private clinics due to lower operational costs. However, limited clinical training availability and lower purchasing power in parts of Africa restrict wider penetration. Continued government healthcare modernization and increasing private-sector investments are expected to support moderate market growth.
Market Segmentations:
By Type:
- Portable
- Fixed
By Application:
- Orthopedic
- Cardiology
By End User:
- Hospitals and clinics
- Diagnostic laboratories
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the Shock Wave Therapy Market features a diverse mix of global healthcare innovators, with companies such as MEDIPOST, Anterogen Co., Ltd., Johnson & Johnson Services, Inc., JW Therapeutics, S. BIOMEDICS, Bristol-Myers Squibb Company, Novartis AG, Atara Biotherapeutics, Gilead Sciences, Inc., and JCR Pharmaceuticals Co., Ltd. The Shock Wave Therapy Market is characterized by strong technological innovation, expanding clinical applications, and increasing competition among device manufacturers focused on non-invasive therapeutic solutions. Companies emphasize advancements in focused and radial shock wave systems, improved energy precision, and enhanced ergonomics to differentiate their product portfolios. Digital integration-including guided treatment protocols, real-time analytics, and connectivity features-has become a core strategic priority as providers seek more consistent outcomes and streamlined workflows. Market players also expand distribution networks and target outpatient and rehabilitation centers with portable, cost-efficient systems. Furthermore, growing demand in sports medicine, chronic pain management, and urology drives continuous product upgrades, clinical validation efforts, and strategic collaborations with hospitals and physiotherapy chains to strengthen market positioning globally.
Key Player Analysis
- MEDIPOST
- Anterogen Co., Ltd.
- Johnson & Johnson Services, Inc.
- JW Therapeutics
- BIOMEDICS
- Bristol-Myers Squibb Company
- Novartis AG
- Atara Biotherapeutics
- Gilead Sciences, Inc.
- JCR Pharmaceuticals Co., Ltd.
Recent Developments
- In November 2025, Bharat Biotech International Ltd entered the cell and gene therapy sector by launching Nucelion Therapeutics Pvt Ltd, a wholly owned CRDMO dedicated to research, development, and manufacturing in this field.
- In March 2025, Shockwave Medical launched the Javelin Peripheral IVL Catheter in the United States, featuring a 150 cm working length and single distal emitter capable of generating 120 shockwave pulses for treating peripheral artery disease.
- In May 2024, Johnson & Johnson completed its acquisition of Shockwave Medical, integrating the company's intravascular lithotripsy platform into Johnson & Johnson MedTech to enhance cardiovascular intervention capabilities.
- In March 2024, EDAP TMS received FDA Breakthrough Device Designation for its Focal One system in treating Deep Infiltrating Rectal Endometriosis, expanding shock wave therapy applications into gynecological conditions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see expanding adoption of shock wave therapy as a preferred non-invasive alternative for managing chronic musculoskeletal conditions.
- Portable and home-use devices will gain wider acceptance as patient-centric care models continue to grow.
- Digital integration, including AI-guided protocols and remote treatment monitoring, will enhance therapy precision and clinical outcomes.
- Clinical indications will expand further into dermatology, wound care, sexual medicine, and cardiovascular applications.
- Outpatient and ambulatory centers will increasingly drive demand due to lower treatment costs and higher patient throughput.
- Manufacturers will focus on developing multi-mode systems offering both focused and radial energy options in a single unit.
- Training and standardized treatment protocols will improve, reducing variability in therapy outcomes across regions.
- Regulatory approvals will accelerate as stronger clinical evidence supports long-term therapeutic efficacy.
- Emerging markets will contribute significantly to growth due to improving healthcare infrastructure and rising awareness.
- Strategic collaborations between device makers, physiotherapy chains, and sports medicine centers will strengthen market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Shock Wave Therapy Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Shock Wave Therapy Market projected to grow between 2025 and 2032?
Which Shock Wave Therapy Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Shock Wave Therapy Market?
Who are the leading companies in the Shock Wave Therapy Market?
Which region commanded the largest share of the Shock Wave Therapy Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2 billion → 2032: USD 4.77 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Shock Wave Therapy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Shock Wave Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Shock Wave Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Shock Wave Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Shock Wave Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Shock Wave Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Shock Wave Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Shock Wave Therapy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2 billion → 2032: USD 4.77 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Shock Wave Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Shock Wave Therapy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Shock Wave Therapy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Shock Wave Therapy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
