
Market Overview:
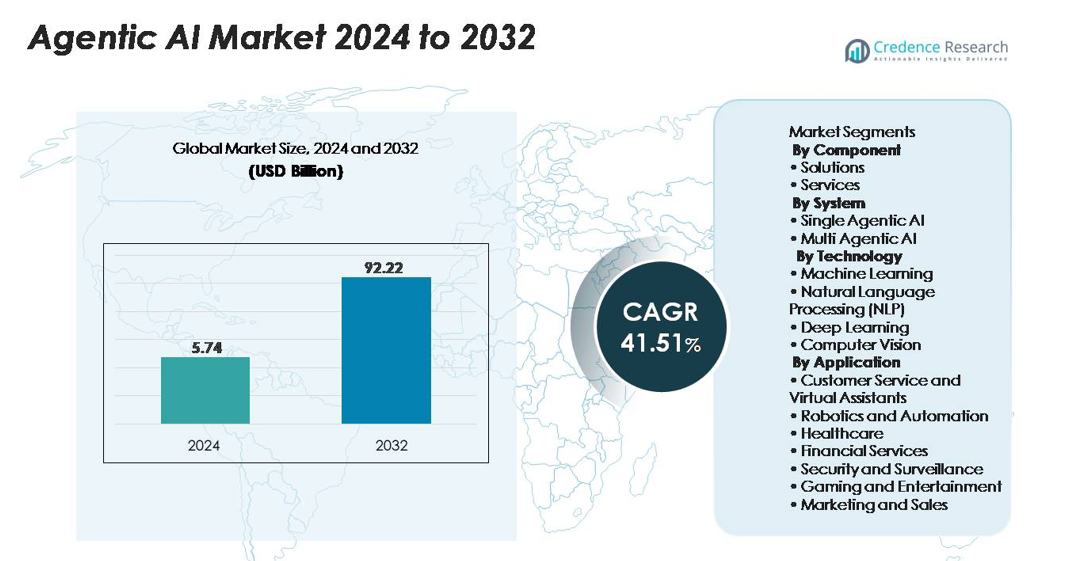
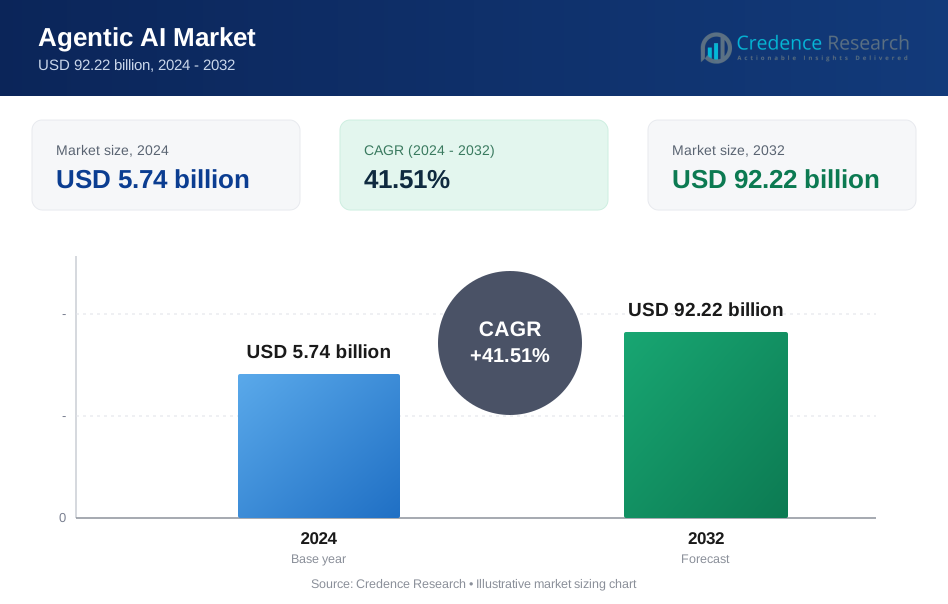
Agentic AI Market was valued at USD 5.74 billion in 2024 and is projected to reach USD 92.22 billion by 2032, growing at a CAGR of 41.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agentic AI Market Size 2024 | SD 5.74 billion |
| Agentic AI Market, CAGR | 41.51% |
| Agentic AI Market Size 2032 | USD 92.22 billion |
Leading companies in the Agentic AI Market include major cloud providers, enterprise software vendors, and AI-focused startups that develop autonomous agents for workflow automation, customer engagement, and decision intelligence. Key players focus on scalable multi-agent architectures, secure data processing, and integration with CRM, ERP, RPA, and analytics platforms. North America leads the global market with 41% share, driven by strong digital infrastructure and early enterprise adoption across finance, healthcare, retail, and logistics. Europe follows with 26% share, supported by strict data governance and investments in explainable AI. Asia-Pacific remains the fastest-growing region with 22% share, backed by large consumer markets, cloud adoption, and government-supported AI programs.
Market Insights
- The Agentic AI Market reached USD 5.74 billion in 2024 and will grow at a CAGR of 41.51% through 2032.
- Solutions dominated with 63% share as enterprises adopted autonomous decision systems that integrate with CRM, ERP, and RPA platforms.
- Demand rises due to automation of customer service, fraud monitoring, workflow orchestration, and predictive analytics, supporting large-scale digital transformation.
- North America led with 41% share, followed by Europe at 26% and Asia-Pacific at 22%, driven by cloud adoption and government-backed AI innovation.
- Competition grows as vendors advance multi-agent systems, self-correcting models, and secure data pipelines, while high deployment cost and integration complexity remain key restraints.
Market Segmentation Analysis:
By Component:
Solutions held the largest share of the Agentic AI Market in 2024, accounting for 63% of overall revenue. Businesses prefer ready-to-deploy platforms that integrate automated reasoning, task planning, and autonomous decision execution. These solutions support complex workflows across customer service, healthcare triage, supply chains, and financial risk investigation. Vendors enhance value with low-code customization, cloud interoperability, and plug-and-play APIs. The Services segment grows steadily as enterprises require consulting, deployment, model optimization, and managed support. Rising demand for scalable automation, reduced human intervention, and improved accuracy keeps the Solutions segment dominant during the forecast period.
- For instance, Microsoft reported that GitHub Copilot's agent mode (or a related internal AI tool) scanned nearly four million lines of production code and generated over 30,000 pull requests during a large-scale internal deployment test.
By System:
Multi Agentic AI dominated with 58% share in 2024 as organizations adopted autonomous agents that collaborate, negotiate, and divide tasks. Multi-agent systems handle parallel planning, fraud detection, logistics orchestration, and real-time decision loops better than single agents. They reduce processing time and improve system resilience by distributing workloads across independent agents. Single Agentic AI finds adoption in consumer chatbots, simple virtual assistants, and workflow automation. However, increasing enterprise demand for complex reasoning, task-splitting, and large-scale optimization keeps multi-agent architectures ahead in the market.
- For instance, Google DeepMind’s AlphaStar used a population of cooperating agents trained with reinforcement learning, executing up to 200 actions per minute in StarCraft II, demonstrating high-speed coordinated strategy execution across multiple agents.
By Technology:
Machine Learning remained the leading technology with 39% share in 2024, driven by enterprise demand for pattern recognition, predictive analytics, and autonomous task execution. NLP gained fast momentum as AI agents processed instructions, documents, emails, and conversational tasks with high accuracy. Deep Learning and Computer Vision enable autonomous robots, surveillance, healthcare imaging, and process automation. Vendors combine hierarchical reinforcement learning and transformer-based architectures to achieve reasoning, self-correction, and multi-step decision workflows. The dominance of Machine Learning continues as enterprises rely on scalable models and real-time data training to improve agent performance across sectors.
Key Growth Drivers
Rising Demand for Autonomous Decision-Making
Enterprises adopt agentic AI to reduce human intervention in repetitive and high-volume tasks. These systems analyze data, plan actions, and execute tasks without manual prompts. Autonomous agents support healthcare triage, legal documentation checks, cybersecurity monitoring, and financial fraud alerts. Businesses replace static chatbots with agents that learn, reason, and self-correct in real time. This shift lowers operational costs and speeds up service delivery. Cloud-based deployment also allows faster scaling. As enterprises seek higher accuracy, faster turnaround, and independent workflow execution, demand for autonomous systems strengthens the growth of the agentic AI market.
- For instance, UiPath’s autonomous RPA bots are designed to execute unattended workflows without human involvement in enterprise environments.
Expansion of AI-Assisted Customer Service and Virtual Assistants
Companies deploy agentic AI to improve customer response time and personalization. Agents extract context from messages, understand intent, and deliver accurate replies without escalation to human teams. The retail, telecom, banking, and travel industries benefit from 24×7 support and language flexibility. Positive customer experience increases brand loyalty and lowers call-center workload. These systems also escalate complex cases to human agents with structured reports. Enterprises invest in agentic AI to enhance customer satisfaction, reduce staffing pressure, and manage rising query volumes, driving strong adoption worldwide.
- For instance, Alibaba’s AI-powered customer service system AliMe processes more than 3 million queries per day, automatically resolving order-status, refund, and delivery questions with NLP engines trained on billions of text samples.
Integration with Analytics, RPA, and Enterprise Software
Businesses integrate agentic AI with robotic process automation, ERP, CRM, and analytics tools. Agents complete multi-step tasks, such as invoice approval, onboarding, compliance checks, and workflow scheduling. This improves transparency, productivity, and decision quality. Manufacturing, logistics, and energy companies use autonomous agents to forecast failures, optimize maintenance, and coordinate resources. This interoperability helps enterprises extract value from existing systems without redesigning frameworks. Growing compatibility with APIs, cloud services, and edge devices strengthens the market and encourages cross-industry adoption.
Key Trends & Opportunities
Growth of Multi-Agent Systems for Complex Operations
Multi-agent models gain attention due to their ability to share tasks, negotiate outcomes, and manage dynamic environments. Industries such as finance, transportation, and defense rely on multiple autonomous agents that monitor data, detect anomalies, and respond instantly. Businesses apply these systems for fleet routing, supply chain orchestration, energy grid optimization, and high-frequency trading. Multi-agent designs also improve resilience, as workflow continues even if one agent fails. As companies expand automation across departments, multi-agent infrastructure becomes a major opportunity for vendors.
- For instance, Siemens uses decentralized agent control in microgrid systems where autonomous agents balance load across turbines and batteries, and documented field trials showed continued operation even after failure of individual control nodes.
Emergence of AI Agents in Healthcare, HR, and Legal Workflows
Hospitals use AI agents for clinical triage, patient tracking, image analysis, and treatment planning. HR teams automate recruitment screening, scheduling, performance tracking, and documentation audits. In legal compliance, agents scan large document sets, summarize risks, and flag violations. These specialized applications reduce human burden and prevent errors. Vendors build domain-specific agents that follow strict regulatory and security standards. Expanding opportunities across non-traditional industries position agentic AI as a core enterprise tool.
- For instance, Google DeepMind’s medical imaging agent achieved documented analysis of more than 15,000 retinal OCT scans, detecting over 50 eye conditions with automated referral decisions validated against specialist review.
Key Challenges
Ethical Risks and Data Privacy Concerns
Agentic AI collects and processes sensitive information, such as personal identity, financial history, medical records, and strategic business data. Unauthorized access or inaccurate decisions can lead to legal consequences. Countries enforce strict rules on explainability, transparency, consent, and model bias. Enterprises must verify that autonomous decisions follow compliance standards. Maintaining trust requires secure data pipelines, encryption, and human supervision. Ethical risks limit rapid adoption, especially in healthcare, banking, and government sectors.
High Deployment Costs and Integration Complexity
Building agentic systems requires advanced computing infrastructure, training data, and model tuning. Many enterprises face challenges integrating autonomous agents with legacy software, on-premise systems, and fragmented datasets. Skilled developers and AI experts are also limited, increasing labor costs. Small organizations hesitate due to long implementation cycles and operational disruption. Vendors address this challenge with cloud-based solutions, low-code platforms, and API-driven deployment, but high upfront investment remains a key barrier for widespread adoption.
Regional Analysis
North America
North America held the largest share of the Agentic AI Market in 2024, accounting for 41% of global revenue. Strong technology infrastructure, early enterprise adoption, and high investments in autonomous decision systems support market dominance. Major sectors such as BFSI, healthcare, retail, and logistics deploy agentic platforms for workflow automation, virtual assistants, fraud monitoring, and predictive analytics. The U.S. drives most demand with large-scale cloud integration and AI research hubs. Vendor partnerships with cloud service providers and software firms stimulate commercialization. Regulatory attention on data transparency and ethical AI also pushes companies to adopt secure and compliant platforms.
Europe
Europe captured 26% share in 2024, supported by enterprise digitization programs and government-backed AI ethics frameworks. Companies deploy agentic AI for manufacturing automation, smart mobility, and cybersecurity. Germany, France, and the U.K. lead adoption due to strong industrial automation and automotive innovation. The region focuses on explainable AI, data privacy, and secure processing under GDPR, pushing vendors to build transparent decision systems. Financial services, public administration, and e-commerce sectors use autonomous agents to enhance customer service, compliance checks, and multi-language communication. Growing investment in multi-agent research strengthens Europe’s position in the global market.
Asia-Pacific
Asia-Pacific held 22% share in 2024 and remains the fastest-growing region due to expanding digital infrastructure, cloud adoption, and AI-driven automation. China, Japan, India, and South Korea invest in agentic systems for robotics, surveillance, fintech, e-commerce, and manufacturing analytics. The consumer sector shows strong adoption in virtual assistants and retail personalization. Government programs supporting AI innovation encourage local tech vendors to develop autonomous software and multi-agent frameworks. Rising use of AI in healthcare diagnostics, banking risk detection, and logistics optimization accelerates market expansion. The region’s large enterprise base strengthens long-term growth potential.
Latin America
Latin America accounted for 6% share in 2024, supported by rising cloud migration and enterprise demand for automation. Brazil and Mexico lead adoption across banking, telecom, and e-commerce. Companies invest in AI agents for customer support, fraud analytics, and process automation to reduce workforce pressure and operational delays. Growth remains gradual due to limited technical expertise and high deployment costs. However, investments from global vendors and regional digital transformation programs encourage broader adoption. The increasing use of Spanish-language and Portuguese-language virtual assistants strengthens market opportunities in the coming years.
Middle East & Africa
The Middle East & Africa captured 5% share in 2024, with adoption led by the UAE, Saudi Arabia, and South Africa. Smart city programs, digital banking, and public sector modernization drive the use of autonomous agents. Organizations deploy AI for customer service automation, document processing, and predictive maintenance in utilities and energy industries. Regional governments push AI policies and training initiatives to build technical capacity. Despite slower adoption in smaller economies, investments in cloud infrastructure and cybersecurity accelerate future demand. Partnerships between international vendors and local enterprises support market expansion across the region.
Market Segmentations:
By Component
- Solutions
- Services
By System
- Single Agentic AI
- Multi Agentic AI
By Technology
- Machine Learning
- Natural Language Processing (NLP)
- Deep Learning
- Computer Vision
By Application
- Customer Service and Virtual Assistants
- Robotics and Automation
- Healthcare
- Financial Services
- Security and Surveillance
- Gaming and Entertainment
- Marketing and Sales
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Agentic AI Market is defined by technology developers, cloud platforms, and enterprise software vendors offering autonomous agents for decision-making and workflow execution. Leading companies focus on multi-agent systems, self-correcting models, and integration with ERP, CRM, and analytics tools. Vendors expand capabilities through partnerships with hyperscale cloud providers and enterprise automation firms. Startups innovate in domain-specific areas such as healthcare triage, legal documentation review, fintech risk assessment, and industrial maintenance. Competition also centers on data privacy, transparent decision logic, and secure deployment. Low-code customization, multilingual support, and API-based scaling create strong differentiation. As enterprises shift from static chatbots to intelligent agents that plan, reason, and act independently, vendors race to deliver reliable autonomy, regulatory compliance, and real-time analytics. Continuous advancements in deep learning, NLP, reinforcement learning, and transformer architectures further intensify market competition.
Key Player Analysis
- Zycus Inc. (U.S.)
- SAP SE (Germany)
- Google LLC (U.S.)
- Anthropic PBC (U.S.)
- Oracle Corporation (U.S.)
- Microsoft (U.S.)
- UiPath (U.S.)
- Nvidia Corporation (U.S.)
- IBM Corporation (U.S.)
- OpenAI Corporation (U.S.)
Recent Developments
- In 2025, Anthropic PBC released its framework for safe and trustworthy agentic systems, focusing on operational transparency, controlled autonomy, and governance standards for high-risk environments.
- In February 2025, Zycus Inc. launched its “Merlin Agentic AI Platform” to enable autonomous workflows in procurement.
Report Coverage
The research report offers an in-depth analysis based on Component, System, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of multi-agent systems will expand as enterprises automate complex workflows.
- Agentic AI will support self-learning and self-correction to reduce human supervision.
- Customer service, healthcare, finance, and logistics will adopt domain-specific autonomous agents.
- Integration with RPA, ERP, CRM, and analytics platforms will improve workflow continuity.
- Cloud and edge deployment will make autonomous agents scalable for global operations.
- Vendors will focus on transparent decision logic to meet data privacy regulations.
- Autonomous cybersecurity agents will detect anomalies and respond in real time.
- Low-code customization will help enterprises build agents without deep technical skills.
- Partnerships between cloud providers and AI startups will accelerate product innovation.
- Enterprises will combine multimodal AI, NLP, and reinforcement learning to enhance reasoning and planning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Agentic AI Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Agentic AI Market projected to grow between 2025 and 2032?
Which Agentic AI Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Agentic AI Market?
Who are the leading companies in the Agentic AI Market?
Which region commanded the largest share of the Agentic AI Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.74 billion → 2032: USD 92.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agentic AI Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agentic AI Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agentic AI Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agentic AI Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agentic AI Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agentic AI Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agentic AI Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agentic AI Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.74 billion → 2032: USD 92.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agentic AI Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agentic AI Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Agentic AI Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Agentic AI Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

