
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Real Estate Software Market Size 2024 | USD 12,340.24 Million |
| Real Estate Software Market, CAGR | 13.10% |
| Real Estate Software Market Size 2032 | USD 37,366.90 Million |
Market Overview
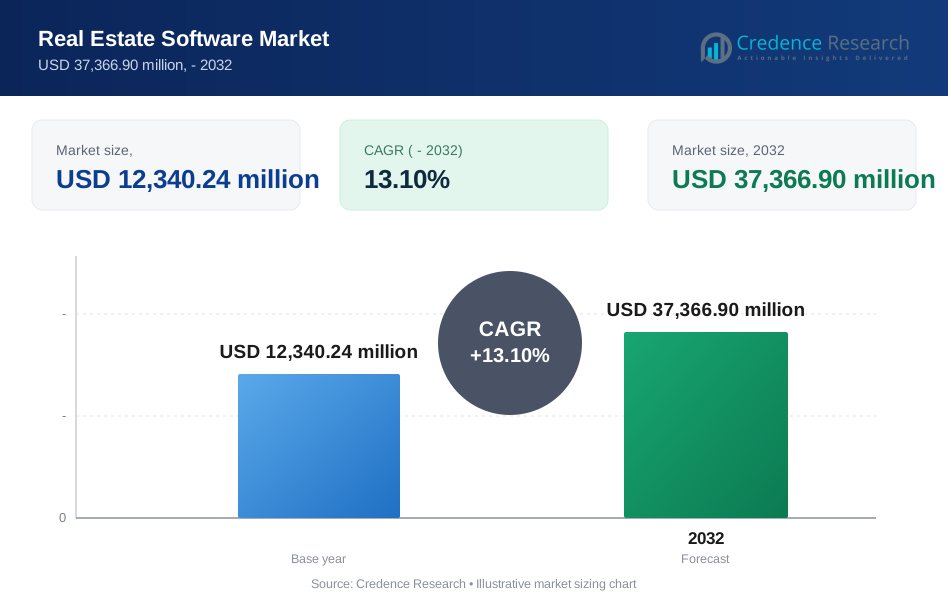
The global Real Estate Software Market is projected to grow from USD 12,340.24 million in 2023 to an estimated USD 37,366.90 million by 2032, with a compound annual growth rate (CAGR) of 13.10% from 2024 to 2032. This growth is driven by the increasing demand for automation and digitization in the real estate industry, enhancing operational efficiencies and improving customer experiences.
Market drivers for the Real Estate Software Market include the rise in property transactions, growing reliance on cloud-based solutions, and an increasing focus on customer experience management. Additionally, trends such as the integration of AI and machine learning for predictive analytics, mobile-enabled solutions, and enhanced data security are shaping the industry's future. Real estate businesses are increasingly leveraging these technologies to streamline operations, optimize resources, and improve service delivery, further fueling market expansion.
Geographically, North America holds the largest share of the global market, owing to the high adoption of advanced technologies and a well-established real estate sector. However, the Asia Pacific region is anticipated to witness the fastest growth, driven by rapid urbanization and digital transformation in emerging markets like China and India. Key players in the global Real Estate Software Market include Oracle Corporation, SAP SE, Microsoft Corporation, IBM Corporation, and Yardi Systems, who continue to innovate and expand their product offerings to cater to the evolving needs of the industry.
Market Insights
- The global real estate software market is projected to grow from USD 12,340.24 million in 2023 to USD 37,366.90 million by 2032, with a CAGR of 13.10% from 2024 to 2032.
- Increasing demand for automation, digitization, and AI integration in real estate operations is driving market growth, enhancing efficiency and customer experience.
- Growing reliance on cloud-based solutions is helping real estate businesses scale and streamline operations, reducing costs and enabling remote access.
- High implementation costs and challenges related to data privacy and security concerns can hinder the adoption of real estate software, especially in emerging markets.
- North America holds the largest market share, while the Asia-Pacific region is expected to grow at the fastest rate, driven by urbanization and digital transformation.
- Integration of AI, machine learning, and IoT is enabling more accurate property valuations, predictive analytics, and smarter property management.
- Mobile-first solutions and an increased focus on personalized customer experiences are shaping the future of real estate software in both residential and commercial sectors.
Market Drivers
Increasing Demand for Automation and Efficiency
The global real estate industry has been experiencing a shift toward automation, as businesses seek to improve operational efficiency and reduce human errors. Real estate software solutions help automate numerous processes, including property management, leasing, sales, customer relationship management (CRM), and transaction tracking. For instance, a large commercial real estate firm implemented RPA to automate its lease administration process, resulting in a significant reduction in errors and a notable increase in productivity. Similarly, a property management company used RPA to automate tenant and vendor communications, which led to a 20% reduction in response time and a 15% reduction in errors, showcasing the tangible benefits of automation in real estate operations. Automation also allows for real-time data updates, faster processing of transactions, and improved accuracy in tracking financials and other key metrics. With the increasing need to manage vast property portfolios and complex transactions, real estate software has become indispensable in maintaining operational efficiency, especially for large firms. Moreover, automation through real estate software reduces operational costs and optimizes resource allocation, which further drives its adoption.
Rising Adoption of Cloud-Based Solutions
Cloud-based solutions are playing a crucial role in transforming the real estate software market. Cloud computing provides scalability, flexibility, and cost-effectiveness, enabling real estate firms to access their software and data from anywhere, at any time. For instance, a real estate company integrated cloud computing solutions to manage its property listings and client interactions, allowing agents to access real-time data from anywhere, which improved their responsiveness and client satisfaction. This shift to cloud-based platforms has enabled real estate businesses to scale operations seamlessly, as evidenced by a company that saw a 40% increase in occupancy rates and a 2% increase in landlord ROI after adopting cloud solutions. Cloud solutions offer secure data storage and backup capabilities, which further encourage businesses to adopt them. Additionally, cloud-based real estate software reduces the need for heavy upfront investments in infrastructure, making it an attractive option for smaller businesses and startups. As cloud technology continues to evolve, its integration with other advanced technologies like artificial intelligence (AI), machine learning (ML), and the Internet of Things (IoT) will further enhance the functionalities of real estate software.
Integration of Advanced Technologies such as AI and Machine Learning
The integration of advanced technologies like artificial intelligence (AI) and machine learning (ML) into real estate software is another significant driver of market growth. AI and ML enable real estate software to offer predictive analytics, enhance property valuation accuracy, and improve lead generation and customer engagement. For instance, Roofstock, a prominent data and analytics platform in the single-family rental sector, integrated AI-powered analytics from HouseCanary to provide detailed neighborhood insights and accelerate the appraisal and valuation process. This integration allowed Roofstock to manage a larger volume of properties efficiently, demonstrating the practical application of AI in enhancing real estate operations. AI-powered tools can analyze vast amounts of data to provide insights into market trends, investment opportunities, and potential risks. This helps businesses make data-driven decisions, improving their chances of success in the competitive real estate market. Furthermore, machine learning algorithms enable software to learn from past data and improve over time, offering more precise recommendations and predictions. These technologies also enhance customer interactions through chatbots, virtual assistants, and personalized recommendations, which improve the customer experience and increase conversion rates.
Focus on Customer Experience and Personalization
In the competitive real estate market, offering a superior customer experience has become a critical differentiator for businesses. Real estate software solutions with integrated customer relationship management (CRM) systems help companies provide a more personalized experience for their clients. For instance, a real estate agency using a CRM system with AI capabilities was able to provide personalized property recommendations to clients based on their search history and preferences, leading to higher client engagement and satisfaction. This personalization not only improved the client experience but also resulted in a 10% increase in client retention rates. These solutions allow businesses to track client preferences, interactions, and feedback, enabling them to tailor their offerings to meet specific customer needs. Real estate software helps agents and property managers provide clients with customized property recommendations, market insights, and timely communication, enhancing client satisfaction and loyalty. With the rise of mobile devices and apps, clients expect on-the-go access to property listings, real-time updates, and seamless interactions with real estate professionals. Software solutions that integrate mobile-friendly interfaces and provide convenient access to information improve the overall customer experience. As real estate companies strive to build lasting relationships with clients, the focus on customer experience and personalization will continue to drive the demand for advanced real estate software solutions that provide these capabilities.
Market Trends
Integration of Artificial Intelligence and Machine Learning
The integration of AI and ML technologies in real estate software is revolutionizing the industry by enabling data-driven decision-making. For instance, AI algorithms are now used to analyze feedback obtained from social media and online evaluations of individual properties, providing real estate companies with insights into buyer preferences and market sentiment. This allows for more accurate property valuations and investment decisions. Predictive analytics tools within these software solutions can forecast future property values based on various factors, enhancing the ability to identify investment opportunities and evaluate market trends. AI-driven chatbots and virtual assistants further improve customer engagement by offering instant, personalized responses to inquiries, thereby boosting user experience and conversion rates.
Cloud-Based Software Solutions and SaaS Models
Cloud-based platforms are becoming the backbone of modern real estate operations due to their scalability, flexibility, and cost-efficiency. For instance, platforms like Ility integrate AI, IoT, and cloud computing to manage multi-property portfolios effectively, offering real-time insights into property conditions and operational efficiencies. This shift to the cloud eliminates the need for costly on-premises infrastructure, reducing upfront costs and ongoing maintenance expenses. SaaS models, in particular, are popular among SMEs as they provide access to high-quality software through subscription-based pricing, making it more accessible for businesses to streamline operations and enhance customer service without significant financial burdens.
Mobile-First Solutions and Enhanced User Experience
The trend towards mobile-first solutions in real estate software is driven by the need for instant access to information on the go. For instance, Airbnb has adopted a mobile-first approach, allowing users to easily book accommodations through touch-friendly navigation and responsive layouts, enhancing the user experience on mobile devices. Real estate agents benefit from mobile access to real-time data, property images, and market analytics, enabling quicker decisions and more effective client interactions during property showings or meetings. Mobile apps also provide property seekers with the ability to search for listings, track properties, and receive instant notifications, improving the overall customer experience.
Focus on Data Security and Privacy
With the increasing volume of sensitive data in real estate transactions, data security and privacy are paramount. For instance, real estate software solutions now incorporate strong encryption methods to safeguard sensitive data from unauthorized access, ensuring compliance with regulations like GDPR and HIPAA. These measures help businesses adhere to privacy laws while maintaining client trust. As cyber threats grow, the demand for software with advanced security features, real-time monitoring, and incident response mechanisms is on the rise, ensuring that real estate companies can protect client data and transaction details effectively.
Market Challenges
Data Security and Privacy Concerns
As the adoption of real estate software increases, one of the primary challenges facing the market is ensuring robust data security and privacy. Real estate software solutions handle sensitive information, such as personal client data, financial records, and property details. This makes them attractive targets for cyberattacks, data breaches, and unauthorized access. Additionally, stringent data privacy regulations, such as the General Data Protection Regulation (GDPR) in Europe and the California Consumer Privacy Act (CCPA) in the U.S., place considerable pressure on companies to ensure compliance. Any failure to meet regulatory standards or protect client data could result in significant financial penalties, reputational damage, and loss of customer trust. As a result, software providers must invest heavily in cybersecurity measures, such as encryption, multi-factor authentication, and real-time monitoring, to safeguard data and maintain compliance. These security challenges create a barrier to entry for new players and complicate the implementation of software solutions, particularly for smaller real estate businesses that may lack the resources to implement the necessary security measures.
High Implementation and Maintenance Costs
Another key challenge in the global real estate software market is the high cost of implementation and ongoing maintenance. While cloud-based solutions offer some cost advantages over traditional on-premise systems, the initial costs of software licensing, customization, and integration can still be substantial. For large real estate organizations with complex needs, implementing a comprehensive software solution often requires significant investments in infrastructure, training, and consultancy services. Moreover, maintaining and upgrading these systems can be an ongoing expense. Smaller real estate businesses, particularly those in emerging markets, may face budget constraints that make it difficult to adopt or fully utilize these software solutions. Additionally, as technology continues to evolve, real estate companies must continually invest in updates, new features, and system improvements to remain competitive. These financial barriers can limit the adoption of advanced software solutions and create challenges for businesses looking to remain efficient in a rapidly changing technological landscape.
Market Opportunities
Growth in Emerging Markets
One of the most significant opportunities in the global real estate software market lies in the expansion of real estate operations in emerging markets. Regions such as Asia-Pacific, Latin America, and the Middle East are experiencing rapid urbanization, a growing middle class, and increased foreign investment in real estate. As these regions develop, there is a rising need for advanced software solutions to streamline property management, sales, and leasing operations. Real estate software providers have the opportunity to tailor their offerings to these growing markets by providing affordable, scalable, and cloud-based solutions that cater to the unique needs of emerging economies. The demand for digital solutions is expected to surge as real estate companies in these regions adopt technology to improve efficiency, enhance customer experiences, and manage larger property portfolios. Furthermore, the increasing penetration of internet services and mobile devices in these markets will foster the adoption of mobile-first platforms, creating new avenues for growth in the sector.
Integration of Internet of Things (IoT) and Smart Property Management
Another key opportunity in the real estate software market is the integration of the Internet of Things (IoT) and smart property management features. IoT-enabled devices, such as smart thermostats, security cameras, and energy management systems, are becoming integral parts of modern buildings. Real estate software that can seamlessly integrate with these IoT devices to offer real-time monitoring, predictive maintenance, and energy efficiency reporting is in high demand. This trend opens up opportunities for software developers to create solutions that provide property managers with the tools to optimize building operations, reduce costs, and improve tenant satisfaction. The increasing focus on sustainability and energy efficiency further accelerates this opportunity, as real estate companies seek innovative ways to manage resources more effectively.
Market Segmentation Analysis
By Component
The market is primarily segmented into Software and Services. The software segment holds the larger share due to the increasing demand for digital solutions that help real estate companies automate operations, manage properties, track transactions, and enhance customer experiences. Within the software segment, the demand for cloud-based solutions is growing, driven by the need for scalability and flexibility. The services segment includes professional services such as consulting, integration, and support, which are crucial for businesses adopting new software systems and ensuring their optimal performance. These services help organizations implement real estate software solutions effectively and maintain their functionality.
By Deployment Type
The market is further divided into On-premise and Cloud deployment types. Cloud-based solutions are gaining dominance, as they offer scalability, lower upfront costs, and remote access, which are vital for real estate businesses that need to operate from multiple locations. On the other hand, on-premise solutions are more commonly adopted by large enterprises that require greater control over their data and infrastructure. The growing trend toward remote work and the increasing need for flexibility are expected to drive the growth of cloud deployment, making it the preferred choice for most companies in the market.
Segments
Based on component
- Software
- Services
- Based on deployment type
- On-premise
- Cloud
Based on software type
- Customer Relationship Management Software
- Enterprise Resource Planning Software
- Property Management Software
- Contract Software
- Others
Based on end user
- Architects & Engineers
- Project Managers
- Real Estate Agents
- Others
Based on application
- Commercial
- Residential
Based on region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%)
North America holds the largest market share in the global real estate software market, accounting for approximately 35% of the total market. The region benefits from a highly developed real estate sector, which extensively adopts advanced technology solutions to enhance operational efficiency and improve customer experiences. The United States, in particular, is a significant contributor to this growth, with widespread adoption of cloud-based software and AI-driven analytics in both residential and commercial real estate. The presence of major software providers and increased demand for real estate digital tools across property management, CRM, and ERP systems further strengthens the market in North America. The region’s mature infrastructure and high disposable income allow real estate businesses to invest in cutting-edge solutions, providing a strong foundation for continued market leadership.
Europe (28%)
Europe holds the second-largest market share, representing approximately 28% of the global market. The European real estate market is experiencing substantial growth in the adoption of real estate software, especially driven by countries such as the United Kingdom, Germany, and France. The shift towards cloud-based software and SaaS models is particularly prominent, with businesses in the region leveraging these solutions for improved property management, enhanced customer engagement, and regulatory compliance. Europe’s focus on sustainability and energy-efficient buildings also influences the demand for real estate software that integrates IoT and smart property management features. Additionally, stringent data protection regulations such as GDPR contribute to the rising demand for secure, compliant software solutions.
Key players
- CoStar Realty Information Inc.
- RealPage Inc.
- SMR Group
- MRI Software LLC
- Oracle Corporation
- Altus Group Ltd.
- Autodesk Inc.
- Accruent
- Microsoft Corporation
- SAP SE
- Yardi Systems Inc.
- Trimble Inc.
- Aareon
- AppFolio Inc.
- Entrata Inc.
Competitive Analysis
The global real estate software market is highly competitive, with several leading players continually innovating and expanding their product offerings to capture a larger market share. Companies like CoStar Realty Information Inc., RealPage Inc., and Yardi Systems Inc. dominate the market due to their extensive product portfolios, which include cloud-based solutions, property management, customer relationship management (CRM), and enterprise resource planning (ERP) software. These companies maintain a competitive edge through continuous technological advancements, such as integrating AI and machine learning capabilities into their software. Major players like Oracle Corporation, Microsoft, and SAP SE bring strength in their global presence, technological infrastructure, and ability to offer integrated solutions that can serve a wide range of industries, not just real estate. Smaller players like AppFolio Inc. and Entrata Inc. focus on niche solutions tailored to specific market needs, providing flexibility and scalability for smaller real estate firms. The competition remains intense as these companies expand into emerging markets and adapt to changing customer demands.
Recent Developments
- In January 2025, CoStar Group expanded its global footprint by partnering with Chandler Garvey, a UK-based commercial property consultancy. This collaboration integrates CoStar's real estate data and analytics platform with LoopNet’s marketplace, enhancing property visibility and market insights. Additionally, CoStar announced its intent to acquire Matterport, Inc., aiming to strengthen its property data capabilities with 3D capture technology. The company also reported significant growth in its residential platform, Homes.com, which reached 130 million monthly unique visitors by Q3 2024.
- In December 2024, RealPage announced the closure of a U.S. Department of Justice investigation into its multifamily rental pricing practices, affirming its compliance with antitrust laws. RealPage also introduced innovative AI-enabled software platforms that enhance operational efficiency for real estate stakeholders. The company continues to defend itself against civil lawsuits while maintaining a strong reputation in the industry, highlighted by accolades such as the 2024 TITAN Innovation Award.
- In January 2024, MRI Software launched the next generation of CTM eContracts simplifying real estate transaction management with enhanced user interfaces and contract explanations. In June 2024, MRI acquired eGent, a Denver-based transaction management software provider, accelerating its contract solutions’ capabilities. The company also introduced MRI Engage CRM in mid-2024 to streamline leasing and retention processes for multifamily organizations.
- In November 2024, Altus Group released its Q3 Pan-European dataset analysis on commercial real estate valuation trends, marking the first positive movement in property values across Europe in two years. This development aligns with broader market stabilization following European Central Bank rate cuts. Altus also reported recurring revenue growth and margin expansion in its analytics segment during Q3 2024.
- In August 2024, Entrata launched an expanded lineup of AI-powered ELI+ product suites at its annual summit, focusing on autonomous property management and efficiency improvements. The company also strengthened its global presence by hiring Rakesh Ramchandani as Managing Director for India in July 2024, committing to significant team expansion in the region.
Market Concentration and Characteristics
The global real estate software market exhibits a moderately concentrated structure, with a mix of dominant global players and emerging niche providers. Large firms like CoStar Realty Information Inc., Oracle Corporation, Microsoft, and Yardi Systems Inc. hold significant market share due to their comprehensive product portfolios, advanced technological capabilities, and established customer bases. These companies leverage economies of scale, robust financial resources, and strong brand recognition to maintain a competitive advantage. On the other hand, smaller players such as AppFolio Inc. and Entrata Inc. carve out niche markets by offering specialized solutions that cater to specific customer segments, such as small property managers or certain real estate sectors. The market is characterized by high innovation, rapid technological advancements (including AI, cloud computing, and IoT integration), and increasing demand for scalable, mobile-first solutions. As a result, competition remains fierce, with companies focusing on enhancing user experience, improving software functionality, and expanding their geographical reach.
Report Coverage
The research report offers an in-depth analysis based on Component, Data Center Size, End user and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The shift towards cloud-based platforms will continue to dominate the market, driven by the need for scalability, cost-efficiency, and remote access to data.
- AI-powered tools will become more prevalent, enhancing property valuation, predictive analytics, and customer service through chatbots and virtual assistants.
- With growing smartphone usage, mobile-first real estate software will gain traction, offering on-the-go access to property listings and management tools for both agents and clients.
- The integration of Internet of Things (IoT) devices with real estate software will facilitate smart property management, improving efficiency in energy consumption and building maintenance.
- Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East, will see significant growth as urbanization and real estate investments increase the demand for digital solutions.
- As cybersecurity threats grow, real estate software solutions will emphasize enhanced data security features, ensuring compliance with privacy regulations such as GDPR and CCPA.
- Real estate software will increasingly offer personalized solutions, allowing businesses to tailor functionality and user interfaces based on specific needs or market segments.
- Blockchain will gain traction for improving transparency and security in real estate transactions, providing secure property ownership records and streamlining contract management.
- Real estate businesses will continue focusing on providing exceptional customer experiences by offering intuitive software solutions that enable seamless communication and transaction management.
- With the increasing demand for comprehensive solutions, market consolidation may occur, as larger players acquire niche companies to expand their capabilities and service offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Real Estate Software Market in 2023 and 2032?
What is the compound annual growth rate (CAGR) of the Global Real Estate Software Market?
What are the key drivers for growth in the Real Estate Software Market?
Which regions are leading the Global Real Estate Software Market?
What are some emerging trends in the Real Estate Software Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Real Estate Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Real Estate Software Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 12,340.24 million → 2032: USD 37,366.90 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Real Estate Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Real Estate Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Real Estate Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Real Estate Software Market Drivers
- 3.3 Real Estate Software Market Restraints & Challenges
- 3.4 Real Estate Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Real Estate Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Real Estate Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Real Estate Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Real Estate Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Real Estate Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Real Estate Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Real Estate Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Real Estate Software Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Real Estate Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Real Estate Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Real Estate Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Real Estate Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Real Estate Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Real Estate Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Real Estate Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Real Estate Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Real Estate Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Real Estate Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Real Estate Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
