
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Edge AI ASIC Chip Market Size 2024 | USD 19,395.59 million |
| Edge AI ASIC Chip Market, CAGR | 15.82% |
| Edge AI ASIC Chip Market Size 2032 | USD 67,967.87 million |
Market Overview:
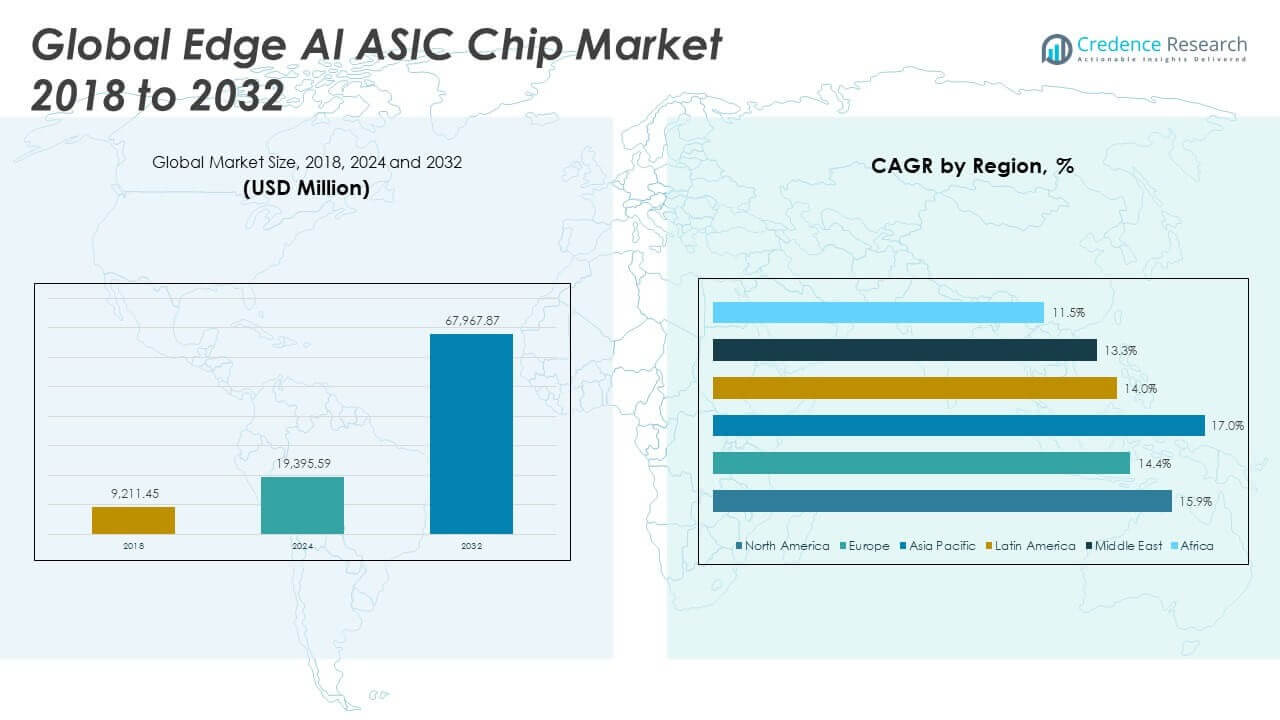
The Global Edge AI ASIC Chip Market size was valued at USD 9,211.45 million in 2018 to USD 19,395.59 million in 2024 and is anticipated to reach USD 67,967.87 million by 2032, at a CAGR of 15.82% during the forecast period.
The growth of the Global Edge AI ASIC Chip Market is primarily driven by the increasing deployment of smart devices and the rising adoption of edge computing across industries. With the proliferation of Internet of Things (IoT) devices, there is a substantial demand for real-time data processing at the edge, minimizing latency and enhancing response time without depending on cloud-based servers. Edge AI ASICs are specifically designed to deliver high-efficiency inference with low power consumption, making them ideal for applications such as smart surveillance, autonomous vehicles, industrial automation, and wearable electronics. Additionally, the ongoing advancements in semiconductor manufacturing technologies such as the transition to smaller process nodes (7nm and below) are enabling higher computational performance with lower thermal output, thereby broadening the scope of AI at the edge. Furthermore, increasing concerns regarding data privacy and stringent regulations like GDPR are accelerating the shift towards on-device processing, as ASICs enable secure and efficient AI functionalities directly on endpoints.
Regionally, the Asia-Pacific region dominates the global Edge AI ASIC Chip Market, supported by a robust electronics manufacturing ecosystem, rapid digital transformation, and government-led initiatives to develop AI infrastructure. Countries such as China, South Korea, Taiwan, and Japan are key contributors, with strong semiconductor production capacities and extensive R&D investments. China, in particular, continues to invest heavily in AI innovation and edge computing applications across its industrial and surveillance sectors. Meanwhile, North America holds a significant share of the market, driven by strong demand from major technology firms, a mature industrial automation landscape, and advanced capabilities in AI chip design and development. The U.S. leads in terms of innovation, with companies such as NVIDIA, Intel, and Qualcomm at the forefront of edge AI ASIC development. Europe is also emerging as a strategic market due to increasing adoption of edge AI in automotive, manufacturing, and smart city projects, especially in countries like Germany and France. Additionally, the Middle East and Africa are experiencing rapid growth, fueled by investments in smart infrastructure, surveillance.
Market Insights:
- The market grew from USD 9,211.45 million in 2018 to USD 19,395.59 million in 2024 and is projected to reach USD 67,967.87 million by 2032, registering a CAGR of 15.82%.
- The rapid adoption of edge computing and proliferation of IoT devices is creating high demand for real-time AI processing, boosting the market for energy-efficient ASICs.
- ASICs outperform general-purpose chips in power-sensitive applications like mobile devices, robotics, and wearables due to their low energy consumption and compact design.
- Increasing data privacy concerns and global regulations such as GDPR are driving demand for on-device AI, positioning edge ASICs as secure inference solutions.
- Advances in semiconductor manufacturing, particularly sub-7nm process nodes, are enabling higher performance and thermal efficiency in edge ASICs.
- High development costs, long prototyping cycles, and the need for specialized design skills are limiting ASIC adoption among smaller enterprises.
- The Asia-Pacific region leads the market due to robust semiconductor production and AI investments, while North America and Europe show strong demand driven by innovation and industrial applications.
Market Drivers:
Rising Demand for Real-Time Processing in Edge Devices Drives ASIC Adoption
The increasing requirement for real-time data processing in edge devices is a key driver for the Global Edge AI ASIC Chip Market. Applications in surveillance cameras, autonomous vehicles, and industrial robots require immediate decision-making without relying on centralized cloud infrastructure. Edge AI ASIC chips provide the dedicated, low-latency performance necessary to handle complex inference tasks locally. These chips are optimized for neural network processing and deliver higher efficiency than general-purpose processors. Enterprises are shifting toward edge computing models to reduce response times and ensure uninterrupted services. It aligns with the global trend toward decentralized computing architectures across sectors such as manufacturing, healthcare, and logistics.
- For example, SiMa.ai’s MLSoC Modalix chip, launched in early 2025, achieves 50 trillion operations per second (TOPS) on a single chip and supports clustering for up to 200 TOPS per PCIe card.
Energy Efficiency and Customization Capabilities Make ASICs Ideal for Edge AI
Custom AI ASIC chips offer substantial energy efficiency, making them ideal for power-sensitive environments such as mobile devices, IoT endpoints, and wearable electronics. The market favors ASICs due to their ability to perform dedicated tasks with minimal energy consumption compared to GPUs and FPGAs. It supports long operational life in battery-powered systems, a critical requirement for edge-based applications. ASICs also allow precise customization for specific AI models, enabling performance tuning without unnecessary overhead. The demand for compact, thermally stable chips that fit into space-constrained hardware further accelerates adoption. The Global Edge AI ASIC Chip Market benefits from this preference for domain-specific architectures.
Regulatory Pressures and Data Privacy Concerns Push AI Processing to the Edge
Growing concerns around data privacy and compliance with regulations such as GDPR and CCPA are driving the shift toward on-device AI inference. Businesses increasingly prefer to keep sensitive user data within local devices, reducing exposure to network vulnerabilities. It reduces dependency on cloud infrastructure, enhances data security, and ensures compliance with regional laws. In healthcare and finance, where confidentiality is paramount, edge ASICs allow organizations to deploy AI functionalities while maintaining strict control over data flow. The Global Edge AI ASIC Chip Market responds to these regulatory demands by enabling localized AI processing. This regulatory environment strengthens the case for edge AI acceleration using ASICs.
Advancements in Semiconductor Technologies Enable More Powerful Edge ASICs
Continued innovations in semiconductor manufacturing, including the transition to sub-7nm process nodes, significantly enhance the performance of AI ASIC chips. These advancements support higher transistor density, lower power consumption, and increased computational throughput, which are critical for AI tasks at the edge. It enables manufacturers to pack powerful AI acceleration into compact, cost-effective chips. The Global Edge AI ASIC Chip Market is expanding as OEMs adopt these next-generation chips in consumer electronics, automotive control units, and industrial automation systems. The reduced heat output and greater processing efficiency of modern ASICs help broaden their deployment. This technological progress directly contributes to the acceleration of edge AI adoption.
- ASICs using sub-7nm process nodes. For example, foundries are now producing chips with transistor densities that support higher computational throughput and lower power consumption key for edge AI workloads.
Market Trends:
Rising Integration of AI ASICs in Smart Consumer Electronics Is Accelerating Innovation
The Global Edge AI ASIC Chip Market is witnessing a notable trend in the integration of AI chips into smart consumer electronics. Devices such as smartphones, smart home assistants, and augmented reality glasses increasingly require localized AI capabilities for enhanced user experiences. Manufacturers now embed ASICs to handle voice recognition, facial authentication, and contextual understanding on the device itself. It enables real-time personalization without relying on cloud-based processing. The push for seamless, intelligent, and privacy-conscious user interactions is driving rapid innovation in consumer-grade ASICs. This trend is redefining how edge AI is incorporated into everyday digital lifestyles.
- For example, the MediaTek Dimensity 9300 integrates a dedicated AI Processing Unit (APU 690) capable of 8 TOPS (trillion operations per second), enabling real-time image enhancement and contextual voice commands without offloading data to the cloud. This chip supports up to 3200 MHz LPDDR5X memory and 8K video decoding, directly addressing the demand for high-performance, privacy-conscious AI in consumer devices.
Collaborative Development Between Chipmakers and Industry-Specific OEMs Is Gaining Momentum
The Global Edge AI ASIC Chip Market is benefiting from growing collaboration between semiconductor companies and original equipment manufacturers (OEMs) across industries. Automotive, industrial automation, and healthcare sectors are working closely with chipmakers to co-develop custom ASICs tailored to specific operational needs. It allows end-users to optimize performance, power budgets, and software compatibility at the silicon level. These joint development agreements reduce time-to-market and lower the risk associated with generic hardware adaptation. The trend is shifting product development from one-size-fits-all to purpose-built AI silicon. This strategic alignment enhances competitiveness and product differentiation.
AI Workload Specialization Is Shaping Multi-Core and Heterogeneous Architectures
There is a rising trend toward multi-core and heterogeneous ASIC designs to address diverse AI workload requirements. Traditional single-function accelerators are no longer sufficient for evolving edge AI demands, prompting designers to build chips that support multiple AI models and data types simultaneously. It enhances the adaptability of edge devices across dynamic use cases, from image classification to time-series analysis. The Global Edge AI ASIC Chip Market reflects this shift through growing investments in domain-specific architecture innovation. Developers are now engineering chips with layered cores for parallel tasks and adaptive inference. This architectural complexity supports higher performance without compromising energy efficiency.
- For example, NVIDIA’s Ampere architectureexemplifies the move to heterogeneous, multi-core ASICs, integrating 54 billion transistors per chip and combining tensor cores, ray-tracing cores, and CUDA cores. This design supports simultaneous execution of multiple AI models, achieving up to 312 TFLOPS (FP16) in the A100 GPU, and is used in edge AI servers for real-time video analytics and industrial automation.
Emergence of AI Development Toolchains Tailored for Edge ASICs Is Streamlining Deployment
The expansion of software ecosystems around edge AI ASICs is shaping a trend toward developer-friendly toolchains. Companies are building integrated development environments (IDEs), compilers, and frameworks specifically optimized for ASIC deployment. It simplifies programming for non-general-purpose hardware and lowers barriers for AI engineers. These platforms provide support for model quantization, compression, and real-time debugging, which are critical for edge environments. The Global Edge AI ASIC Chip Market is evolving to not only provide hardware but also end-to-end enablement for developers. This trend enhances scalability, fosters innovation, and accelerates AI integration across industries.
Market Challenges Analysis:
High Development Costs and Design Complexity Restrain Widespread Adoption
One of the major challenges in the Global Edge AI ASIC Chip Market is the high cost and complexity associated with chip design and manufacturing. ASIC development requires substantial upfront investment in EDA tools, verification systems, and silicon fabrication, which can be prohibitive for small and mid-sized enterprises. It also demands specialized design expertise, particularly for low-power AI inference, which limits entry for new players. The long lead times involved in prototyping and tape-out increase the risk of design flaws, especially in rapidly evolving AI workloads. Companies often struggle to balance performance, power efficiency, and cost in a single chip. These constraints slow down innovation cycles and limit the scalability of ASIC-based edge AI solutions.
Lack of Standardization and Fragmented Ecosystem Impede Interoperability
The fragmented nature of edge AI applications presents another significant challenge to the Global Edge AI ASIC Chip Market. Industries vary widely in performance requirements, security protocols, and data formats, making it difficult to create standard ASIC platforms that meet diverse needs. It becomes challenging to scale or adapt a single chip design across multiple verticals without extensive customization. The absence of widely accepted frameworks for edge AI ASICs also hampers interoperability with existing software and hardware ecosystems. Developers face integration issues and limited tooling support, which delays deployment and increases development overhead. This fragmentation reduces overall adoption and poses a barrier to achieving economies of scale in the market.
Market Opportunities:
Expansion of AI-Powered Edge Devices Across Emerging Sectors Creates New Demand
The increasing deployment of AI-powered edge devices in sectors such as agriculture, energy, and smart cities presents a strong growth opportunity for the Global Edge AI ASIC Chip Market. These industries require real-time insights at the edge to optimize operations, reduce downtime, and enhance safety. It allows ASIC vendors to develop specialized chips tailored to environmental monitoring, predictive maintenance, and intelligent infrastructure. The demand for low-power, high-performance processing in remote and bandwidth-constrained environments aligns with the core strengths of edge AI ASICs. Governments and enterprises are investing in digitization across these domains, creating new revenue streams for chip manufacturers. The broadening application scope will support long-term market expansion.
Rising Adoption of AI in Healthcare and Wearables Boosts Edge ASIC Integration
Healthcare devices and consumer wearables increasingly rely on local AI processing for real-time diagnostics, health monitoring, and user personalization. The Global Edge AI ASIC Chip Market is well-positioned to meet these needs with compact, energy-efficient chips that process data securely on-device. It enables faster response times while maintaining patient privacy and reducing cloud dependency. As remote patient monitoring and personalized wellness solutions grow, manufacturers are integrating ASICs to support advanced features in portable formats. The convergence of AI and healthcare technologies creates a strategic opportunity for edge AI chip vendors to expand their footprint in regulated, high-growth segments.
Market Segmentation Analysis:
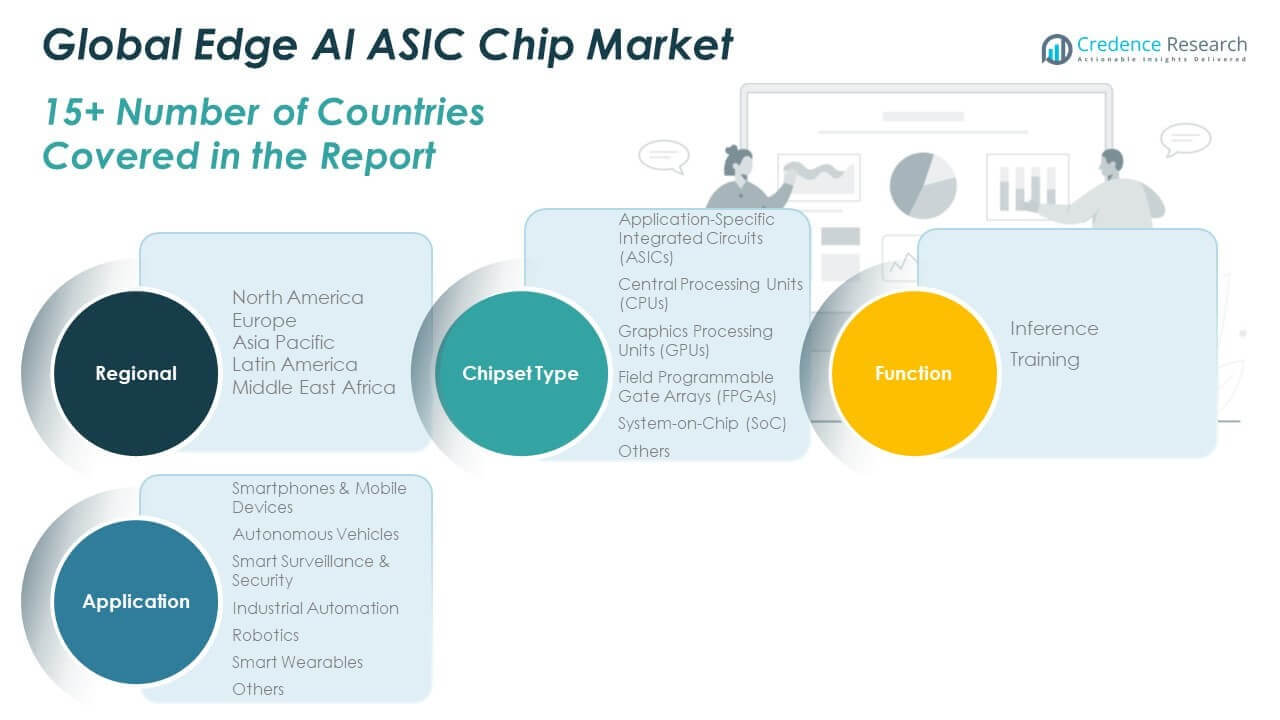
The Global Edge AI ASIC Chip Market is segmented by chipset type, function, and application, reflecting its broad deployment across industries.
By chipset type, Application-Specific Integrated Circuits (ASICs) lead the market due to their efficiency in executing fixed AI tasks at low power and high speed. System-on-Chip (SoC) solutions also hold a significant share, offering integrated functionality for compact devices. CPUs and GPUs remain relevant for flexible processing, while FPGAs provide reconfigurability for specific use cases. The market also includes other specialized processors tailored for niche applications.
By function, inference dominates due to its primary role in running AI models at the edge, where real-time response and low latency are critical. Training holds a smaller share, as most model training occurs in centralized data centers rather than on edge devices.
- For example, Google’s Edge TPU delivers 4 TOPS at just 2 W, enabling battery-powered IoT devices to perform complex AI inference tasks locally.
By application, smartphones and mobile devices contribute a large portion of demand, followed by autonomous vehicles, smart surveillance, and industrial automation. It also sees increasing deployment in robotics and smart wearables, supporting local AI tasks in compact and power-sensitive environments.
- For instance, the MediaTek Dimensity 9300 chip integrates an AI Processing Unit supporting real-time image enhancement and contextual voice commands directly on the device.
Segmentation:
By Chipset Type
- Application-Specific Integrated Circuits (ASICs)
- Central Processing Units (CPUs)
- Graphics Processing Units (GPUs)
- Field Programmable Gate Arrays (FPGAs)
- System-on-Chip (SoC)
- Others
By Function
- Inference
- Training
By Application
- Smartphones & Mobile Devices
- Autonomous Vehicles
- Smart Surveillance & Security
- Industrial Automation
- Robotics
- Smart Wearables
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Edge AI ASIC Chip Market size was valued at USD 3,898.56 million in 2018 to USD 8,120.84 million in 2024 and is anticipated to reach USD 28,539.37 million by 2032, at a CAGR of 15.9% during the forecast period. North America holds a prominent position in the Global Edge AI ASIC Chip Market with a market share of 32.5% in 2024. It benefits from strong technological infrastructure, well-established semiconductor players, and early adoption of AI-enabled systems in sectors such as automotive, aerospace, and industrial automation. The United States leads regional growth, supported by investments in edge computing from companies like Intel, NVIDIA, and Qualcomm. Demand for real-time decision-making in surveillance, robotics, and connected healthcare continues to fuel ASIC integration. Government support for AI and 5G development further enhances market readiness and product scalability.
Europe
The Europe Edge AI ASIC Chip Market size was valued at USD 1,716.46 million in 2018 to USD 3,415.81 million in 2024 and is anticipated to reach USD 10,882.52 million by 2032, at a CAGR of 14.4% during the forecast period. Europe accounted for 13.7% of the Global Edge AI ASIC Chip Market share in 2024. It is driven by the region’s focus on industrial automation, autonomous mobility, and smart city projects. Germany, France, and the Netherlands are key contributors, with companies investing in embedded AI solutions for manufacturing and automotive applications. Regional policies promoting green tech and data sovereignty support localized AI processing. The rise in collaborative research initiatives and public-private partnerships improves innovation and adoption rates. Regulatory alignment across EU member states fosters a unified digital infrastructure for edge AI growth.
Asia Pacific
The Asia Pacific Edge AI ASIC Chip Market size was valued at USD 2,821.84 million in 2018 to USD 6,254.59 million in 2024 and is anticipated to reach USD 23,796.57 million by 2032, at a CAGR of 17.0% during the forecast period. Asia Pacific leads the Global Edge AI ASIC Chip Market with the largest share of 37.8% in 2024. The region benefits from high-volume electronics production, rapid 5G deployment, and aggressive AI investments across China, South Korea, Japan, and India. China remains the top contributor with its state-backed initiatives for AI and semiconductor self-sufficiency. Local companies are rapidly deploying edge-enabled devices in smart surveillance, retail, and consumer electronics. Growing urbanization and demand for intelligent edge systems drive strong market momentum. Asia Pacific also hosts major chip fabrication hubs, which support scalable ASIC deployment.
Latin America
The Latin America Edge AI ASIC Chip Market size was valued at USD 415.65 million in 2018 to USD 863.80 million in 2024 and is anticipated to reach USD 2,662.69 million by 2032, at a CAGR of 14.0% during the forecast period. Latin America holds a 5.2% share in the Global Edge AI ASIC Chip Market in 2024. It shows growing interest in AI-enabled edge solutions, particularly in sectors such as agriculture, logistics, and urban security. Countries like Brazil and Mexico are exploring ASIC deployment for traffic monitoring, resource management, and public safety systems. Investment from multinational technology companies is helping to bridge infrastructure gaps. It supports the integration of localized edge AI systems in cost-sensitive and remote environments. The region is emerging as a secondary growth hub with expanding opportunities in smart technologies.
Middle East
The Middle East Edge AI ASIC Chip Market size was valued at USD 250.86 million in 2018 to USD 481.54 million in 2024 and is anticipated to reach USD 1,415.60 million by 2032, at a CAGR of 13.3% during the forecast period. The region accounted for 1.9% of the Global Edge AI ASIC Chip Market share in 2024. Countries like the UAE and Saudi Arabia are spearheading digital transformation through smart city projects and national AI strategies. The demand for real-time video analytics, energy management, and connected infrastructure is increasing ASIC deployment. Public sector initiatives are supporting adoption through smart policing, transportation, and surveillance networks. It strengthens the regional focus on security and sustainability through edge-based intelligence. Strategic collaborations with global chipmakers are enhancing capabilities and localization efforts.
Africa
The Africa Edge AI ASIC Chip Market size was valued at USD 108.08 million in 2018 to USD 259.01 million in 2024 and is anticipated to reach USD 671.12 million by 2032, at a CAGR of 11.5% during the forecast period. Africa contributed 1.0% to the Global Edge AI ASIC Chip Market in 2024. While adoption is still in early stages, the region holds long-term potential in smart agriculture, renewable energy, and mobile healthcare. Countries such as South Africa, Kenya, and Nigeria are piloting edge-based applications to address infrastructure and service delivery challenges. It helps overcome connectivity limitations and improves service efficiency in remote areas. Efforts from development agencies and startups are accelerating AI integration in affordable hardware. Growth is supported by increasing mobile penetration and government interest in digital innovation.
Key Player Analysis:
- NVIDIA
- Qualcomm
- Intel
- Apple
- MediaTek
- Hailo
- Kneron
- Google (Edge TPU)
- Samsung
- Arm
Competitive Analysis:
The Global Edge AI ASIC Chip Market is highly competitive, with leading semiconductor companies investing in purpose-built architectures to serve edge AI applications. Key players such as NVIDIA, Intel, Qualcomm, MediaTek, and Samsung Electronics focus on performance optimization, low-power design, and integration of AI accelerators into compact chipsets. It enables efficient execution of neural networks in latency-sensitive environments. Companies are differentiating through advanced fabrication nodes, customized AI toolchains, and application-specific designs. Strategic partnerships with device manufacturers and software vendors strengthen market positioning and accelerate product deployment. Startups specializing in edge AI ASICs, such as Hailo and Kneron, are gaining traction through innovative, lightweight inference solutions. The market favors vendors that combine silicon efficiency with flexible software support. Competitive intensity continues to rise as global demand for edge intelligence scales across industries including automotive, consumer electronics, and industrial automation.
Recent Developments:
- In Jan 2025, Samsung Electronics launched its Galaxy S25, S25+, S25 Ultra, and S25 Edge smartphones, all of which integrate advanced Edge AI ASIC chips. These devices highlight the growing trend of embedding AI capabilities directly into consumer electronics for enhanced on-device intelligence and performance.
- In February 2025, NXP Semiconductors entered a definitive agreement to acquire Kinara, boosting its Edge AI ASIC capabilities. The all-cash deal, valued at USD 307 million, aims to integrate Kinara’s discrete NPUs (Ara‑1, Ara‑2) and AI software directly into NXP’s industrial and automotive edge platforms.
- In March 2025, Blaize, a company specializing in edge AI hardware, partnered with KAIST (Korea Advanced Institute of Science and Technology) to advance low-power vision accelerators for autonomous vehicles. This partnership focuses on developing efficient AI chips for real-time processing in automotive applications.
- In October 2023, Renesas Electronics, a leading Japanese semiconductor manufacturer, formed a partnership with EdgeCortix, a Japan-based startup specializing in energy-efficient AI processing solutions. This collaboration aims to accelerate the development of edge AI solutions by unifying developer experiences across Renesas' diverse offerings and supporting heterogeneous architectures.
Market Concentration & Characteristics:
The Global Edge AI ASIC Chip Market exhibits moderate to high concentration, with a few dominant players controlling a significant share of the revenue. It is characterized by high entry barriers due to capital-intensive fabrication processes, specialized design expertise, and long development cycles. The market emphasizes low power consumption, high-speed inference, and tailored architecture to meet edge computing demands. Product differentiation is largely based on node size, thermal efficiency, and software compatibility. It continues to evolve with strong emphasis on innovation, with players investing in AI-focused R&D and advanced packaging technologies. The market also features a growing number of niche startups offering lightweight ASICs optimized for specific edge applications. Competition is intensifying as customer demand shifts toward compact, scalable, and application-specific solutions.
Report Coverage:
The research report offers an in-depth analysis based on chipset type, function, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Edge AI ASIC adoption will accelerate in automotive systems, enabling real-time decision-making for autonomous and advanced driver-assistance features.
- Demand will rise in healthcare for secure, on-device diagnostics and monitoring, supporting remote patient care and wearable innovations.
- AI-driven industrial automation will expand, with ASICs powering robotics, predictive maintenance, and smart manufacturing processes.
- Ongoing 5G deployment will enhance connectivity, allowing broader deployment of edge ASICs in telecom infrastructure.
- Energy-efficient ASICs will play a critical role in reducing power consumption across battery-operated edge devices.
- Emerging smart city projects will increase demand for ASIC-enabled surveillance, traffic control, and environmental monitoring.
- Continued investment in smaller process nodes will improve chip density and performance, enabling more powerful edge inference.
- AI ASIC integration in consumer electronics will grow, driven by demand for privacy-focused, responsive devices.
- Collaboration between chipmakers and application-specific OEMs will boost the development of tailored edge AI solutions.
- Government initiatives and national AI strategies will support R&D and regional production, strengthening global supply chains.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Edge AI ASIC Chip Market?
What are the key segments within the Global Edge AI ASIC Chip Market?
What are some challenges faced by the Global Edge AI ASIC Chip Market?
Who are the major players in the Global Edge AI ASIC Chip Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Edge AI ASIC Chip Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Edge AI ASIC Chip Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 19,395.59 million → 2032: USD 67,967.87 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Edge AI ASIC Chip Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Edge AI ASIC Chip Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Edge AI ASIC Chip Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Edge AI ASIC Chip Market Drivers
- 3.3 Edge AI ASIC Chip Market Restraints & Challenges
- 3.4 Edge AI ASIC Chip Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Edge AI ASIC Chip Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Edge AI ASIC Chip Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Edge AI ASIC Chip category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Edge AI ASIC Chip Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Edge AI ASIC Chip Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Edge AI ASIC Chip. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Edge AI ASIC Chip Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Edge AI ASIC Chip Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Edge AI ASIC Chip Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Edge AI ASIC Chip (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Edge AI ASIC Chip
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Edge AI ASIC Chip Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Edge AI ASIC Chip Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Edge AI ASIC Chip Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Edge AI ASIC Chip Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Edge AI ASIC Chip Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Edge AI ASIC Chip Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Edge AI ASIC Chip Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Edge AI ASIC Chip Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
