
Market Overview:
The In Space Manufacturing Market size was valued at USD 968 million in 2024 and is anticipated to reach USD 5137.6 million by 2032, at a CAGR of 23.2% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| In-Space Manufacturing Market Size 2024 | USD 968 million |
| In-Space Manufacturing Market, CAGR | 23.2% |
| In-Space Manufacturing Market Size 2032 | USD 5137.6 million |
The in-space manufacturing market is gaining momentum as investments from governments and private enterprises in space exploration continue to rise. Expanding satellite deployments and breakthroughs in microgravity manufacturing are fueling demand. Companies are leveraging additive manufacturing, crystal growth, and advanced material production in orbit for applications in semiconductors, pharmaceuticals, and specialty alloys. Lower launch costs and the development of return-capable capsules further enhance feasibility and strengthen adoption.
North America dominates the market, supported by national space programs, strong commercial ventures, and advanced infrastructure. Asia-Pacific is recording the fastest growth, with countries like China and India accelerating efforts in space manufacturing. This expansion is driven by policy initiatives and rising involvement from private enterprises, highlighting the region’s growing role in global market development. Growing international collaborations and partnerships are also fostering technology transfer and accelerating commercialization opportunities.
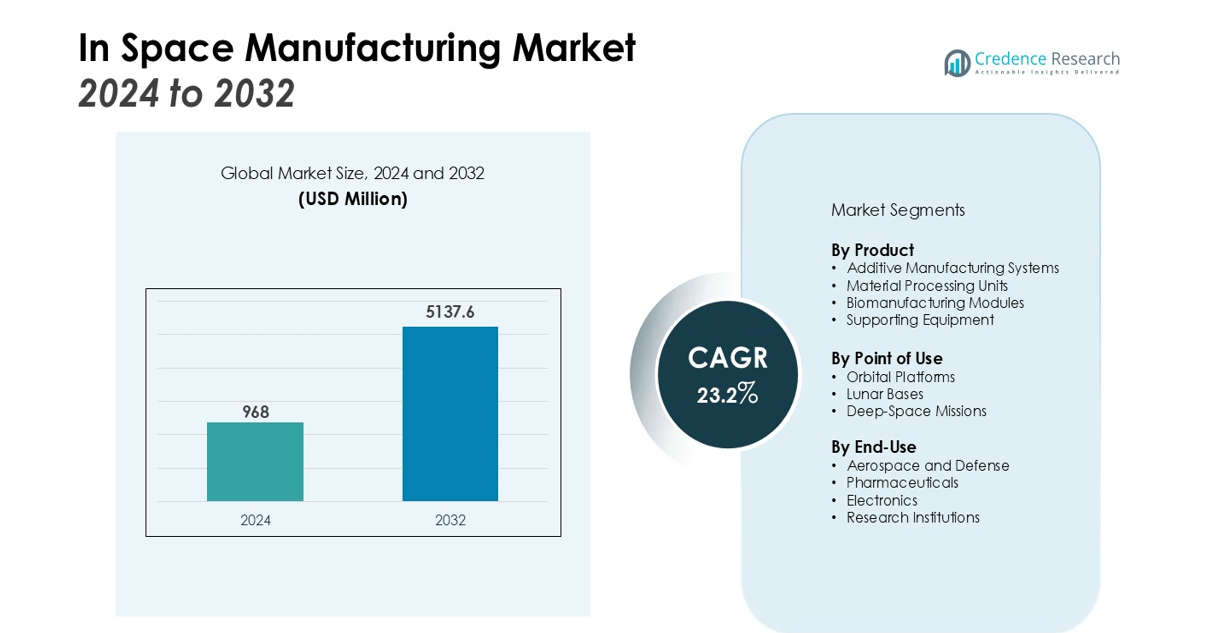
Market Insights:
- The In Space Manufacturing Market was valued at USD 968 million and is projected to reach USD 5137.6 million by 2032, growing at a CAGR of 23.2%.
- Rising investments from government agencies and private enterprises are driving innovation and accelerating adoption of in-orbit manufacturing technologies.
- Expanding satellite deployments and demand for advanced materials such as alloys, crystals, and composites strengthen growth opportunities.
- Technological progress in microgravity manufacturing, including additive manufacturing and bio-production, is improving efficiency and creating high-value industrial applications.
- High initial costs, operational risks, and regulatory uncertainty remain key barriers that limit broader participation and slow adoption.
- North America leads with 46% share, supported by strong infrastructure, established space programs, and commercial ventures.
- Asia-Pacific holds 29% share, registering the fastest growth, while Europe with 19% share focuses on collaboration and sustainability to strengthen its role in global development.
Key Player Analysis:
- Lockheed Martin Corporation
- Airbus SE
- Northcorp Grumma
- Allevi Inc
- Northcorp Grumman Corporation
- Astrobotic Technology, Inc.
- Le Verre Fluore Fiber Solutions
- Axiom Space, Inc.
- Echodyne Corporation
- Sierra Nevada Corporation
- Global Graphene Group, Inc. (G3)
Competitive Analysis:
The In Space Manufacturing Market is shaped by a competitive landscape that includes established aerospace companies, specialized space technology providers, and emerging startups. Leading players focus on research and development to expand capabilities in additive manufacturing, material processing, and biomanufacturing under microgravity conditions. It encourages partnerships with space agencies, private investors, and research institutions to accelerate deployment of advanced manufacturing systems. Companies are also investing in reusable launch systems and return-capable capsules to improve commercial viability and reduce costs. Strategic collaborations and joint ventures remain central to gaining a competitive edge, ensuring shared expertise and faster market entry. The emphasis on sustainable manufacturing practices and advanced infrastructure highlights the growing maturity of the competitive environment, while regional leaders continue to strengthen their dominance through policy support, innovation, and technology transfer. This evolving competitive dynamic is expected to define long-term growth in space-based industrial production.
Recent Developments:
- In August 2025, Astrobotic Technology, Inc. signed a Term Sheet with Norway's Andøya Space to create a launch and landinging site for its Xodiac reusable rocket, planning for its first European launch campaign in 2026.
- In July 2025, Axiom Space, Inc. formed a partnership with Oakley to design and develop a cutting-edge visor system for future astronauts.
- In September 2025, Echodyne Corporation was selected to provide its MESA® radars for the Australian Defence Force counter-drone initiative, known as "Project Land 156".
Report Coverage:
The research report offers an in-depth analysis based on Product, Point of Use, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The In Space Manufacturing Market will expand as governments and private enterprises increase funding for orbital production.
- Companies will adopt advanced additive manufacturing systems to produce complex parts directly in orbit.
- Microgravity will enable the development of pharmaceuticals and crystals with higher precision and improved quality.
- It will support the aerospace and defense sector with lightweight structures that enhance mission efficiency.
- Return-capable capsules and reusable launch systems will improve cost efficiency and strengthen commercial adoption.
- Regional collaboration will grow, with North America leading innovation and Asia-Pacific accelerating capacity expansion.
- Europe will continue to focus on sustainable projects and collaborative ventures to enhance competitiveness.
- It will attract strong interest from electronics manufacturers producing fiber optics and semiconductors in orbit.
- International partnerships will increase, promoting knowledge transfer and driving faster commercialization of new technologies.
- The long-term outlook highlights self-sustaining ecosystems in space, supporting exploration, research, and industrial-scale production.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government and Private Investment Surge
Significant funding from national space agencies and private enterprises is accelerating the development and deployment of in-space manufacturing technologies, enabling rapid innovation and commercialization.
Advancements in Microgravity Manufacturing
Breakthroughs in additive manufacturing, crystal growth, and biomanufacturing under microgravity conditions are unlocking new industrial applications and improving the quality and efficiency of products made in orbit.
Expanding Satellite and Space Infrastructure
The proliferation of satellite constellations and the development of reusable launch systems and return-capable capsules are increasing the feasibility and cost-effectiveness of manufacturing in space.
Demand for Advanced Materials and Pharmaceuticals
In-space manufacturing enables the production of high-value materials such as specialty alloys, fiber optics, and pharmaceuticals with superior properties that cannot be replicated on Earth, driving demand from sectors like electronics and healthcare.
International Collaboration and Technology Transfer
Growing partnerships between countries, agencies, and private firms are fostering knowledge exchange, accelerating technology transfer, and opening new markets for in-space manufacturing solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for In Space Manufacturing, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the In Space Manufacturing market projected to grow between 2024 and 2032?
Which In Space Manufacturing market segment held the largest share in 2024?
Who are the leading companies in the In Space Manufacturing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Aerospace & Defense
- 1.2.2 Pharmaceuticals & Biotechnology
- 1.2.3 Electronics & Semiconductors
- 1.2.4 Research & Academia
- 1.2.5 Specialty Materials
- 1.3 By Product
- 1.3.1 Additive Manufacturing Systems
- 1.3.2 Crystal Growth Modules
- 1.3.3 Biomanufacturing Platforms
- 1.3.4 Material Processing Units
- 1.3.5 Return-Capable Capsules
- 1.4 By Application
- 1.4.1 Satellite Component Production
- 1.4.2 Fiber Optics Manufacturing
- 1.4.3 Pharmaceutical Development
- 1.4.4 Advanced Alloy Production
- 1.4.5 Microgravity Research
- 1.5 By Point of Use
- 1.5.1 Low Earth Orbit (LEO)
- 1.5.2 Geostationary Orbit (GEO)
- 1.5.3 Deep Space
- 1.5.4 Cislunar Space
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 968 million → 2032: USD 5137.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In-Space Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In-Space Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In-Space Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In-Space Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In-Space Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In-Space Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In-Space Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In-Space Manufacturing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 968 million → 2032: USD 5137.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In-Space Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aerospace & Defense
- 12.3.7.2 Pharmaceuticals & Biotechnology
- 12.3.7.3 Electronics & Semiconductors
- 12.3.7.4 Research & Academia
- 12.3.7.5 Specialty Materials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Additive Manufacturing Systems
- 12.4.7.2 Crystal Growth Modules
- 12.4.7.3 Biomanufacturing Platforms
- 12.4.7.4 Material Processing Units
- 12.4.7.5 Return-Capable Capsules
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Satellite Component Production
- 12.5.7.2 Fiber Optics Manufacturing
- 12.5.7.3 Pharmaceutical Development
- 12.5.7.4 Advanced Alloy Production
- 12.5.7.5 Microgravity Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Point of Use - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Low Earth Orbit (LEO)
- 12.6.7.2 Geostationary Orbit (GEO)
- 12.6.7.3 Deep Space
- 12.6.7.4 Cislunar Space
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global In-Space Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global In-Space Manufacturing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global In-Space Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global In-Space Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lockheed Martin Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Airbus SE
- 18.4 Northrop Grumman Corporation
- 18.5 Axiom Space, Inc.
- 18.6 Astrobotic Technology, Inc.
- 18.7 Sierra Nevada Corporation
- 18.8 Le Verre Fluore Fiber Solutions
- 18.9 Echodyne Corporation
- 18.10 Blue Origin
- 18.11 Made In Space, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

