
Market Overview:
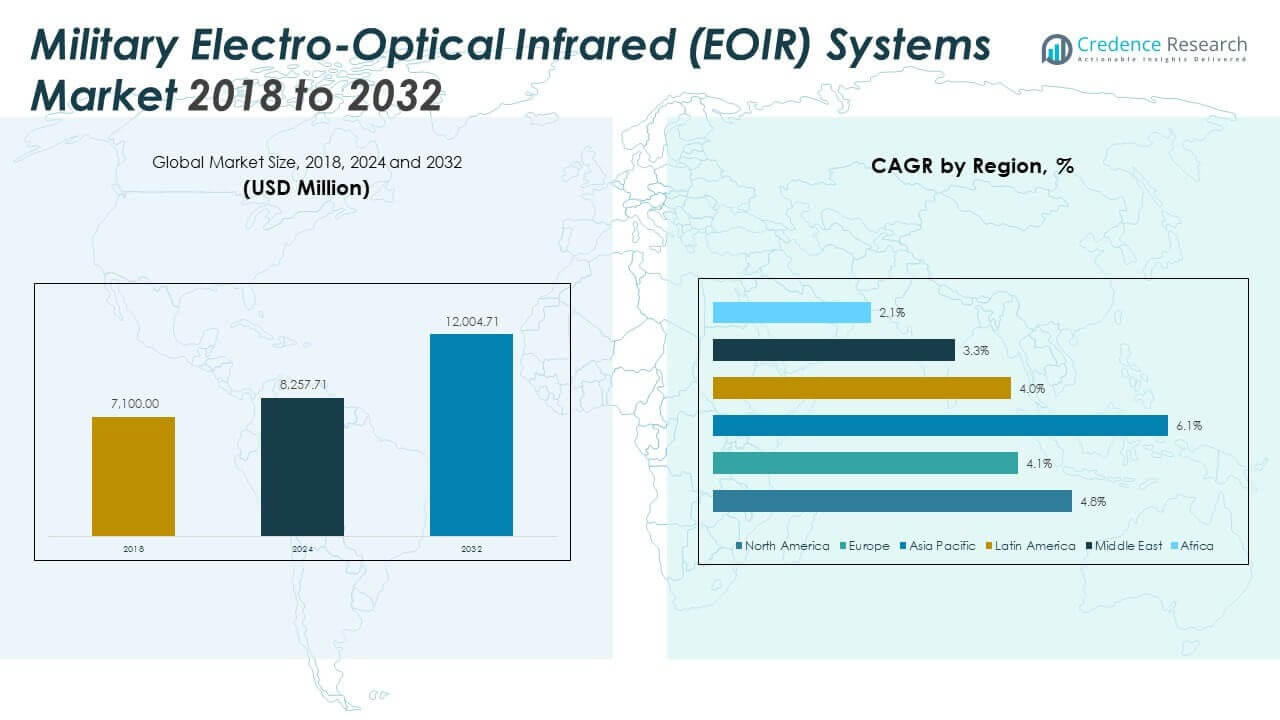
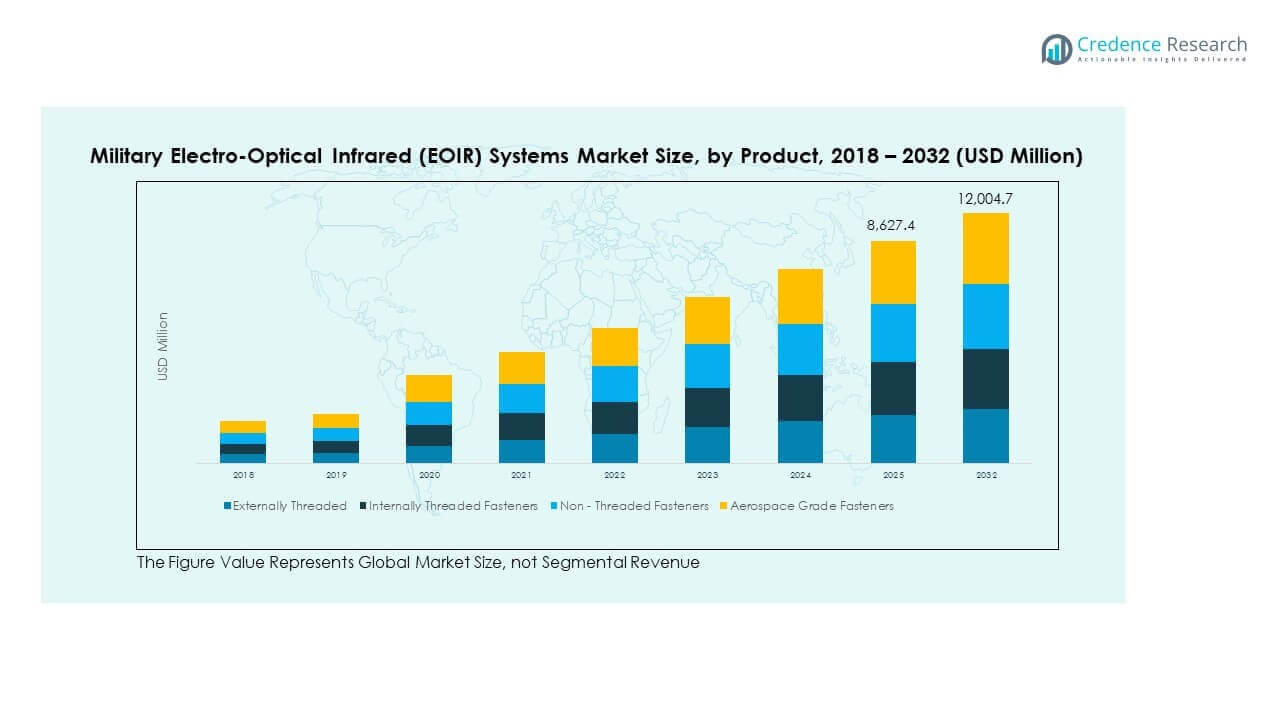
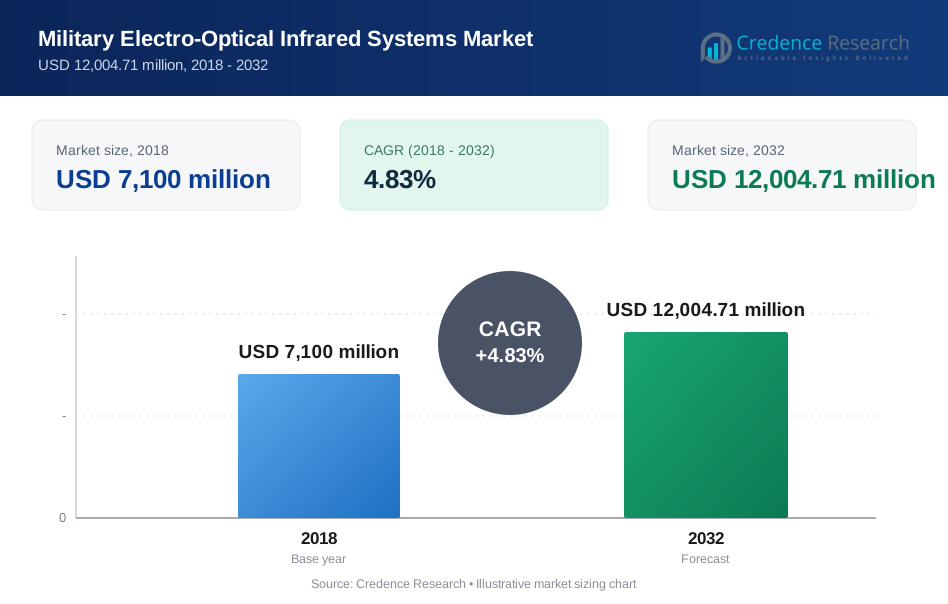
The Global Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 7,100.00 million in 2018 to USD 8,257.71 million in 2024 and is anticipated to reach USD 12,004.71 million by 2032, at a CAGR of 4.83% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Military Electro-Optical Infrared (EOIR) Systems Market Size 2024 | USD 8,257.71 million |
| Military Electro-Optical Infrared (EOIR) Systems Market, CAGR | 4.83% |
| Military Electro-Optical Infrared (EOIR) Systems Market Size 2032 | USD 12,004.71 million |
The market is driven by increasing demand for advanced surveillance and targeting systems to enhance battlefield awareness. Rising adoption of unmanned platforms and integration of EOIR systems with artificial intelligence strengthen operational effectiveness. Military modernization programs across developed and developing nations also support procurement. Geopolitical tensions and cross-border conflicts are further accelerating investments in EOIR technologies, enabling forces to secure accurate reconnaissance, night vision, and precision strike capabilities. The growing need for all-weather performance drives continuous innovation and deployment of these systems.
Regionally, North America leads due to strong defense budgets and continuous investments in next-generation EOIR technologies. Europe follows with focus on border security and NATO-led modernization initiatives. Asia-Pacific is emerging as the fastest-growing market, fueled by military expansion in China, India, and South Korea. The Middle East also shows significant adoption owing to regional conflicts and defense procurement. Latin America and Africa are gradually increasing their presence, supported by modernization and strategic defense collaborations. This geographic spread highlights both mature and emerging opportunities for market players.
Market Insights:
- The Global Military Electro-Optical Infrared (EOIR) Systems Market was valued at USD 7,100 million in 2018, USD 8,257.71 million in 2024, and is projected to reach USD 12,004.71 million by 2032, growing at a CAGR of 4.83%.
- North America holds the largest share at 36.4%, supported by high defense budgets, strong R&D programs, and consistent modernization of surveillance platforms.
- Europe accounts for 25.4% of the market, driven by NATO-led defense initiatives, border security priorities, and investments in aerospace and naval EOIR systems.
- Asia Pacific holds 28.0% and is the fastest-growing region, fueled by territorial disputes, rising defense budgets in China and India, and greater UAV adoption.
- EO/IR payloads command the largest segment share at over 60%, while handheld systems represent around 40%, reflecting stronger demand for integrated multi-platform solutions over portable units.
Market Drivers:
Growing Demand For Advanced Battlefield Awareness:
The Global Military Electro-Optical Infrared (EOIR) Systems Market benefits from the rising need for real-time surveillance and reconnaissance. Modern militaries prioritize enhanced situational awareness to respond faster to threats. EOIR systems provide accurate target detection and identification during day and night operations. It supports mission effectiveness in complex environments by integrating thermal imaging and infrared sensors. Demand is amplified by border security challenges and asymmetric warfare conditions. Investments in advanced targeting pods and airborne sensors further drive procurement. Defense agencies value reliability and adaptability for varied mission types. This creates sustained momentum for EOIR system adoption worldwide.
- For instance, Lockheed Martin progressed the U.S. Space Force’s first Next-Generation Overhead Persistent Infrared satellite to system-level testing in late 2024, integrating advanced sensors with a satellite platform orbiting approximately 22,000 miles above Earth, offering around-the-clock missile detection and tracking capabilities enhancing global surveillance effectiveness.
Integration Of Artificial Intelligence And Unmanned Platforms:
The integration of EOIR technologies with artificial intelligence and unmanned aerial systems strengthens operational capabilities. AI-based analytics enhance image processing speed and accuracy in mission-critical scenarios. Unmanned platforms equipped with EOIR payloads provide extended surveillance coverage. It reduces human risks by enabling long-duration missions in hostile zones. Defense forces are adopting drone-based EOIR systems for border patrol and intelligence gathering. AI-enabled automation improves detection of concealed or moving targets. These advancements reduce decision-making delays during combat. The convergence of EOIR, AI, and unmanned systems accelerates market growth globally.
- For instance, Northrop Grumman’s Beacon program announced in mid-2025 partners with six defense tech companies to develop autonomous flight software using Northrop’s flight hardware platform, building on a foundation of autonomous flight hours to accelerate autonomous EOIR capabilities deployment on unmanned aircraft.
Military Modernization And Strategic Procurement Programs:
Global defense modernization programs are critical drivers of EOIR system adoption. Nations across North America, Europe, and Asia-Pacific allocate higher budgets for upgrading surveillance technologies. The Global Military Electro-Optical Infrared (EOIR) Systems Market leverages consistent procurement programs from established defense powers. Governments prioritize EOIR systems for integration with new aircraft, armored vehicles, and naval fleets. It ensures forces maintain technological superiority against evolving threats. NATO and allied forces emphasize EOIR integration in multi-domain operations. Strategic defense partnerships create opportunities for technology transfer and joint development. These modernization programs guarantee steady long-term demand.
Geopolitical Tensions And Evolving Security Threats:
Rising geopolitical tensions and regional conflicts drive accelerated EOIR system deployment. Governments seek to counter cross-border infiltrations, terrorism, and hybrid warfare tactics. The Global Military Electro-Optical Infrared (EOIR) Systems Market benefits from increased spending on ISR (Intelligence, Surveillance, and Reconnaissance). EOIR sensors enable all-weather monitoring, supporting rapid threat detection. It strengthens national security frameworks through 24/7 operational readiness. Maritime disputes, especially in Asia-Pacific, increase demand for naval EOIR systems. Land-based surveillance networks also adopt EOIR integration to monitor sensitive borders. These dynamics reinforce continuous procurement across multiple regions.
Market Trends:
Shift Toward Multi-Spectral And Hyperspectral Imaging Solutions:
The Global Military Electro-Optical Infrared (EOIR) Systems Market is witnessing a growing adoption of multi-spectral and hyperspectral imaging. Defense organizations recognize the importance of broader wavelength detection for precise target identification. EOIR solutions now combine visible, infrared, and short-wave infrared imaging into a single platform. It enhances battlefield clarity by detecting camouflaged or hidden targets. Hyperspectral systems improve material discrimination, aiding counter-IED operations. Adoption is expanding in reconnaissance aircraft and satellite-based applications. These systems provide richer data for improved mission planning. The shift reflects a transition toward next-generation EOIR capabilities.
- For instance, advanced hyperspectral EOIR payloads used in reconnaissance aircraft enable discriminating materials and chemical compounds beyond conventional imaging, improving detection capabilities of concealed threats.
Rising Adoption Of Miniaturized And Lightweight Systems:
The demand for miniaturized EOIR payloads is increasing, especially for UAVs and portable systems. Defense forces prioritize compact yet powerful solutions for tactical flexibility. The Global Military Electro-Optical Infrared (EOIR) Systems Market incorporates advancements in lightweight optics and sensors. Miniaturized systems provide soldiers with portable tools for ground reconnaissance. It enables faster deployment in urban and mountainous terrains. UAV operators rely on lightweight EOIR payloads for longer flight endurance. Miniaturization also reduces energy consumption, enhancing operational efficiency. This trend aligns with the shift toward agile and mobile defense operations.
- For instance, L3Harris began manufacturing compact EO/IR sensor systems in Katowice, Poland, in 2025, supporting extended UAV missions with reduced sensor weight and power requirements.
Expansion Of Network-Centric And Integrated Systems:
Defense agencies are shifting toward network-centric warfare, where EOIR systems act as crucial enablers. Real-time data integration across platforms strengthens decision-making speed. The Global Military Electro-Optical Infrared (EOIR) Systems Market experiences growth through integration into command and control networks. EOIR sensors are now linked with satellite communication and battlefield management systems. It supports seamless information sharing among ground, air, and naval units. Integrated systems create synchronized situational awareness for joint operations. Governments are investing in EOIR upgrades that support secure data transfer. This trend positions EOIR as a backbone of multi-domain defense strategies.
Focus On Space-Based EOIR Surveillance Platforms:
An emerging trend highlights the expansion of space-based EOIR assets for global monitoring. Satellite-mounted EOIR sensors enhance strategic reconnaissance and early warning capabilities. The Global Military Electro-Optical Infrared (EOIR) Systems Market gains traction from investments in defense space programs. Nations use orbital platforms for missile detection and monitoring of adversary movements. It provides persistent surveillance coverage with minimal vulnerability. Collaboration between defense and space agencies fosters rapid deployment. Space-based EOIR supports both homeland security and expeditionary missions. This trend reflects the strategic evolution of EOIR toward higher altitudes and global reach.
Market Challenges Analysis:
High Development Costs And Complex Integration Issues:
The Global Military Electro-Optical Infrared (EOIR) Systems Market faces challenges from high research and development costs. Advanced sensors require specialized materials and precision engineering, raising production expenses. It creates barriers for smaller manufacturers competing against established defense giants. Integration with multiple platforms, including aircraft and naval vessels, adds further complexity. Compatibility issues between legacy systems and new EOIR technologies delay deployment. Governments often demand rigorous testing, extending procurement cycles. Budget constraints in certain regions restrict large-scale acquisitions. These cost and integration hurdles slow widespread adoption despite strong demand.
Supply Chain Vulnerabilities And Export Restrictions:
The supply chain for EOIR components is vulnerable to geopolitical factors and resource scarcity. The Global Military Electro-Optical Infrared (EOIR) Systems Market encounters risks due to export controls and technology restrictions. It affects international collaborations and slows cross-border procurement. Limited suppliers for advanced optics increase dependency and reduce resilience. Disruptions in rare material supply chains hamper timely production. Geopolitical tensions intensify restrictions on sensitive EOIR technologies. Emerging economies struggle to secure critical components for indigenous development. These supply and regulation challenges create uncertainties for industry stakeholders.
Market Opportunities:
Expansion Of Defense Collaborations And Joint Development Projects:
Opportunities in the Global Military Electro-Optical Infrared (EOIR) Systems Market arise from multinational defense collaborations. Governments increasingly fund joint ventures for EOIR innovation and shared technology access. It enables cost-sharing, accelerates development timelines, and strengthens defense ties. Collaborative projects enhance interoperability of systems across allied forces. Partnerships also provide smaller companies with entry into advanced programs. Joint testing facilities further streamline development cycles. This cooperative approach creates a strong opportunity landscape.
Adoption Of EOIR Systems In Emerging Defense Markets:
Growing defense budgets in Asia-Pacific, Middle East, and parts of Africa create fresh opportunities. The Global Military Electro-Optical Infrared (EOIR) Systems Market benefits from expanding procurement in these emerging regions. It addresses security concerns linked to border monitoring and counter-terrorism. Rapid military modernization in developing economies increases adoption of EOIR-equipped platforms. Suppliers are entering long-term contracts with regional governments. Rising demand for UAV-based EOIR surveillance further widens opportunities. This geographic expansion ensures sustained growth potential across new markets.
Market Segmentation Analysis:
By Product Type
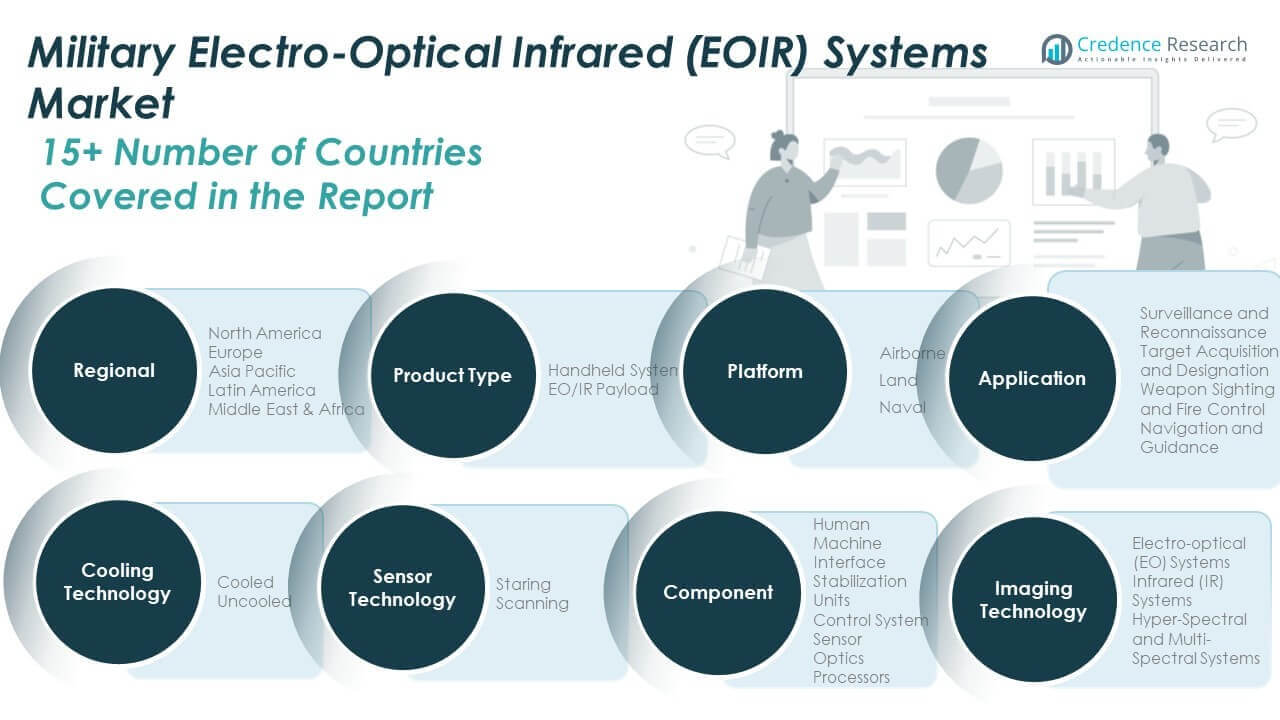
Handheld systems deliver portability and flexibility for ground forces, supporting border patrol and tactical operations. EO/IR payloads dominate due to integration across drones, aircraft, and naval fleets, enabling wide-area surveillance and precision targeting. The Global Military Electro-Optical Infrared (EOIR) Systems Market gains steady momentum from payload adoption in multi-domain missions.
- For instance, Leonardo DRS supplies advanced EO/IR thermal weapon sights to U.S. forces, offering enhanced targeting clarity and durability in hand-held formats.
By Platform
Airborne platforms remain the primary application, supported by UAV deployment and reconnaissance aircraft programs. Land-based systems serve armored vehicles and border defense, offering situational awareness in contested zones. Naval platforms adopt EOIR for maritime patrol, anti-piracy, and coastal security missions, strengthening operational reach.
- For instance, BAE Systems equips the UK Royal Navy with EOIR surveillance systems integrated into maritime patrol aircraft improving threat detection over vast sea areas.
By Imaging Technology
Electro-optical systems remain widely used for daytime clarity and high-resolution imaging. Infrared systems address low-visibility conditions and enhance night operations. Hyper-spectral and multi-spectral technologies are expanding with advanced detection and material discrimination capabilities. It drives adoption in intelligence and counter-IED missions.
By Application
Surveillance and reconnaissance account for the largest demand, followed by target acquisition and designation. Weapon sighting and fire control systems enhance battlefield accuracy. Navigation and guidance solutions integrate EOIR into precision strike and situational awareness frameworks.
By Cooling Technology
Cooled systems provide superior sensitivity for long-range detection. Uncooled systems are cost-effective and suitable for portable and tactical applications.
By Sensor Technology
Staring sensors dominate for real-time imaging, while scanning systems support wide-area coverage.
By Component
Key components include human-machine interfaces, stabilization units, control systems, sensors, optics, and processors. Each element contributes to performance, reliability, and mission adaptability.
Segmentation:
By Product Type- Handheld System
- EO/IR Payload
- Airborne
- Land
- Naval
- Electro-optical (EO) Systems
- Infrared (IR) Systems
- Hyper-Spectral and Multi-Spectral Systems
- Surveillance and Reconnaissance
- Target Acquisition and Designation
- Weapon Sighting and Fire Control
- Navigation and Guidance
- Cooled
- Uncooled
- Staring
- Scanning
- Human Machine Interface
- Stabilization Units
- Control System
- Sensor
- Optics
- Processors
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 2,617.77 million in 2018 to USD 3,008.24 million in 2024 and is anticipated to reach USD 4,367.34 million by 2032, at a CAGR of 4.8% during the forecast period. North America accounts for the largest market share at nearly 36.4%. The region benefits from high defense budgets, advanced R&D programs, and early adoption of next-generation EOIR technologies. The United States dominates with continuous investments in UAVs, aircraft systems, and border security programs. Canada and Mexico also increase procurement to strengthen homeland security. The Global Military Electro-Optical Infrared (EOIR) Systems Market leverages this regional demand through large-scale modernization projects. It gains momentum from government contracts with leading defense contractors. Regional focus on integrated ISR platforms further accelerates adoption.
Europe
The Europe Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 1,881.50 million in 2018 to USD 2,103.84 million in 2024 and is anticipated to reach USD 2,890.17 million by 2032, at a CAGR of 4.1% during the forecast period. Europe holds around 25.4% of the global market share. Demand is driven by NATO initiatives, border protection, and counter-terrorism activities. The UK, France, and Germany remain key markets with advanced aerospace and defense industries. Southern and Eastern Europe increase investments due to rising security threats. The Global Military Electro-Optical Infrared (EOIR) Systems Market benefits from collaborative programs among European defense firms. It also grows from cross-border technology transfer and procurement. Maritime surveillance and land-based applications drive wider adoption.
Asia Pacific
The Asia Pacific Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 1,725.30 million in 2018 to USD 2,096.19 million in 2024 and is anticipated to reach USD 3,364.93 million by 2032, at a CAGR of 6.1% during the forecast period. Asia Pacific contributes about 28.0% to the global share, making it the fastest-growing region. China and India lead with large-scale defense modernization and UAV integration. Japan and South Korea emphasize EOIR for missile defense and maritime security. Australia strengthens adoption for naval and border surveillance missions. The Global Military Electro-Optical Infrared (EOIR) Systems Market expands here due to regional conflicts and territorial disputes. It is further supported by indigenous manufacturing programs. Rising defense budgets sustain growth momentum across emerging economies.
Latin America
The Latin America Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 515.46 million in 2018 to USD 594.47 million in 2024 and is anticipated to reach USD 809.96 million by 2032, at a CAGR of 4.0% during the forecast period. Latin America represents around 6.7% of the global share. Brazil dominates with focus on surveillance of its extensive borders and maritime zones. Argentina and Mexico also contribute with growing security investments. The Global Military Electro-Optical Infrared (EOIR) Systems Market in this region benefits from defense upgrades linked to organized crime and smuggling challenges. It gains attention in aerial surveillance, counter-narcotics, and homeland security missions. Adoption remains steady despite budgetary limitations.
Middle East
The Middle East Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 230.75 million in 2018 to USD 248.50 million in 2024 and is anticipated to reach USD 319.39 million by 2032, at a CAGR of 3.3% during the forecast period. The region holds about 2.6% of the global market. Demand is led by Gulf Cooperation Council countries, Israel, and Turkey. Ongoing regional conflicts, border tensions, and counter-terrorism operations drive adoption. The Global Military Electro-Optical Infrared (EOIR) Systems Market benefits from investments in UAV surveillance and advanced targeting systems. It also grows through strategic defense partnerships with Western suppliers. Rising maritime security concerns strengthen naval EOIR procurement.
Africa
The Africa Military Electro-Optical Infrared (EOIR) Systems Market size was valued at USD 129.22 million in 2018 to USD 206.48 million in 2024 and is anticipated to reach USD 252.93 million by 2032, at a CAGR of 2.1% during the forecast period. Africa accounts for nearly 0.9% of the global share, making it the smallest market. South Africa leads with focus on defense modernization and indigenous industry development. Egypt also invests in EOIR for border and maritime surveillance. The Global Military Electro-Optical Infrared (EOIR) Systems Market in this region expands gradually, driven by regional security concerns. It faces budget constraints and heavy reliance on imports. Despite challenges, rising procurement in UAVs and ground-based systems signals slow but steady growth.
Key Player Analysis:
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Raytheon Technologies Corporation
- Thales Group
- Leonardo S.p.A.
- L3Harris Technologies, Inc.
- FLIR Systems, Inc.
- BAE Systems Plc
- Rheinmetall AG
- Saab AB
Competitive Analysis:
The Global Military Electro-Optical Infrared (EOIR) Systems Market is highly competitive, with leading companies focusing on innovation, integration, and global expansion. Established players such as Lockheed Martin, Northrop Grumman, Raytheon Technologies, Thales Group, and Leonardo dominate through advanced portfolios and strong government contracts. It reflects a market where technological superiority, platform adaptability, and multi-domain integration remain decisive factors. Companies invest heavily in research to strengthen infrared imaging, hyperspectral sensing, and AI-driven analytics. Regional defense contractors also enter with specialized solutions, intensifying rivalry. Partnerships, mergers, and acquisitions continue shaping market dynamics while enabling suppliers to expand their global footprint and address evolving defense requirements.
Recent Developments:
- L3Harris Technologies began manufacturing EO/IR sensor systems in a new facility in Katowice, Poland, in August 2025. This site supports European operators with intelligence, surveillance, reconnaissance, and targeting sensors designed for crewed and autonomous military platforms, enhancing rapid delivery to meet evolving security needs.
- In July 2025, Northrop Grumman announced a partnership with six defense tech companies under its Beacon program, designed to develop autonomous flight capabilities using Northrop’s flight hardware and software platforms. This collaboration aims to speed up autonomous technology deployment for military applications. Earlier, in February 2025, Northrop Grumman signed an MoU with Hanwha for collaboration on the Republic of Korea’s mine countermeasures program.
- Thales Group has been active in IoT security advancements, joining the IoT M2M Council in March 2025 to promote secure IoT connectivity with its eSIM technology, enhancing device security critical for modern military systems. Furthermore, Thales and Sopra Steria announced a strategic partnership in February 2025 to digitally transform European Air Traffic Management with the OpenSky Platform.
Report Coverage:
The research report offers an in-depth analysis based on product type, platform, imaging technology, application, cooling technology, sensor technology, and component. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising defense modernization will sustain demand for advanced EOIR platforms.
- Integration with UAVs and autonomous systems will expand operational use.
- Hyperspectral and multi-spectral imaging will enhance target detection.
- Miniaturization will increase adoption across portable and tactical units.
- AI and machine learning will strengthen data processing and threat recognition.
- Space-based EOIR surveillance will gain traction among major powers.
- Regional procurement will rise in Asia Pacific due to territorial disputes.
- Partnerships and joint ventures will accelerate technology transfer.
- EOIR applications in maritime security will see greater adoption.
- Governments will focus on indigenous production to reduce import dependency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Advanced Battlefield Awareness
Modern militaries require real-time surveillance and reconnaissance to enhance situational awareness and respond rapidly to threats. EOIR systems provide accurate target detection and identification in all lighting conditions, supporting mission effectiveness in complex environments.
Integration of Artificial Intelligence and Unmanned Platforms
The combination of EOIR technologies with AI and unmanned aerial systems enables faster image processing, extended surveillance coverage, and reduced human risk. This integration allows for long-duration missions and improved detection of concealed or moving targets, accelerating market adoption.
Military Modernization and Strategic Procurement Programs
Global defense modernization initiatives drive consistent procurement of EOIR systems for integration with new aircraft, armored vehicles, and naval fleets. These programs ensure technological superiority and interoperability, guaranteeing steady long-term demand.
Geopolitical Tensions and Evolving Security Threats
Rising cross-border conflicts, terrorism, and hybrid warfare tactics are prompting governments to invest in EOIR systems for enhanced intelligence, surveillance, and reconnaissance. This supports 24/7 operational readiness and rapid threat detection across multiple regions.
Shift Toward Multi-Spectral and Hyperspectral Imaging
Defense organizations are increasingly adopting multi-spectral and hyperspectral EOIR solutions for broader wavelength detection and precise target identification. These advanced imaging technologies improve material discrimination and battlefield clarity, driving next-generation system deployment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Military Electro-Optical Infrared (EOIR) Systems Market?
At what Compound Annual Growth Rate is the Global Military Electro-Optical Infrared (EOIR) Systems Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Military Electro-Optical Infrared (EOIR) Systems Market?
What are some challenges faced by the Military Electro-Optical Infrared (EOIR) Systems Market?
Who are the major players in the Military Electro-Optical Infrared (EOIR) Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Airborne
- 1.2.2 Land
- 1.2.3 Naval
- 1.3 By Application
- 1.3.1 Surveillance and Reconnaissance
- 1.3.2 Target Acquisition and Designation
- 1.3.3 Weapon Sighting and Fire Control
- 1.3.4 Navigation and Guidance
- 1.4 By Product Type
- 1.4.1 Handheld System
- 1.4.2 EO/IR Payload
- 1.5 By Imaging Technology
- 1.5.1 Electro-optical (EO) Systems
- 1.5.2 Infrared (IR) Systems
- 1.5.3 Hyper-Spectral and Multi-Spectral Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 7,100 million → 2032: USD 12,004.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military Electro-Optical Infrared Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military Electro-Optical Infrared Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military Electro-Optical Infrared Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military Electro-Optical Infrared Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military Electro-Optical Infrared Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military Electro-Optical Infrared Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military Electro-Optical Infrared Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military Electro-Optical Infrared Systems Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 7,100 million → 2032: USD 12,004.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military Electro-Optical Infrared Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Airborne
- 12.3.7.2 Land
- 12.3.7.3 Naval
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Surveillance and Reconnaissance
- 12.4.7.2 Target Acquisition and Designation
- 12.4.7.3 Weapon Sighting and Fire Control
- 12.4.7.4 Navigation and Guidance
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Handheld System
- 12.5.7.2 EO/IR Payload
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Imaging Technology - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Electro-optical (EO) Systems
- 12.6.7.2 Infrared (IR) Systems
- 12.6.7.3 Hyper-Spectral and Multi-Spectral Systems
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military Electro-Optical Infrared Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military Electro-Optical Infrared Systems Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military Electro-Optical Infrared Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military Electro-Optical Infrared Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lockheed Martin Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Northrop Grumman Corporation
- 18.4 Raytheon Technologies Corporation
- 18.5 Thales Group
- 18.6 Leonardo S.p.A.
- 18.7 L3Harris Technologies, Inc.
- 18.8 FLIR Systems, Inc.
- 18.9 BAE Systems Plc
- 18.10 Rheinmetall AG
- 18.11 Saab AB
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

