
Market Overview
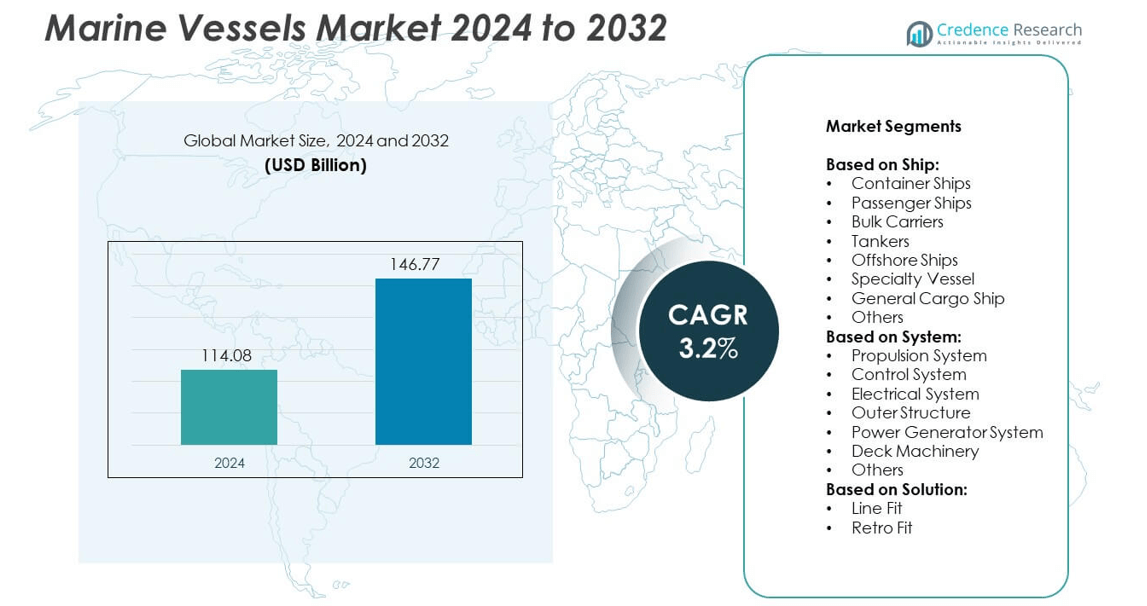
The Marine Vessels Market size was valued at USD 114.08 Billion in 2024 and is anticipated to reach USD 146.77 Billion by 2032, growing at a CAGR of 3.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Vessels Market Size 2024 | USD 114.08 Billion |
| Marine Vessels Market, CAGR | 3.2% |
| Marine Vessels Market Size 2032 | USD 146.77 Billion |
The Marine Vessels market grows through rising global trade, offshore energy projects, and increasing passenger transport demand. Adoption of LNG, hybrid, and hydrogen propulsion systems supports compliance with strict environmental regulations. Digitalization and smart ship technologies improve fuel efficiency, navigation, and predictive maintenance capabilities. Offshore wind projects drive specialized vessel demand, while cruise and ferry segments expand with tourism recovery. It reflects a clear shift toward sustainable ship design, operational efficiency, and advanced technologies shaping the industry’s long-term direction.
North America and Europe lead through advanced shipbuilding, naval modernization, and strong focus on sustainable propulsion technologies. Asia-Pacific dominates global production with large-scale facilities in China, South Korea, and Japan, while Southeast Asia strengthens demand for passenger and cargo vessels. Latin America shows growth through offshore exploration, and the Middle East & Africa expand fleets to support energy exports. Key players shaping the industry include Hyundai Heavy Industries, Fincantieri, Damen Shipyards Group, and Mitsubishi Heavy Industries.
Market Insights
- The Marine Vessels market was valued at USD 114.08 Billion in 2024 and is projected to reach USD 146.77 Billion by 2032, growing at a CAGR of 3.2%.
- Growth is driven by increasing global trade, rising demand for cruise and passenger ships, and expansion of offshore energy projects.
- Market trends include adoption of LNG, hybrid, and hydrogen propulsion systems, smart ship technologies, and digitalization for predictive maintenance.
- Competitive analysis shows key players such as Austal, Babcock International Group, Hyundai Heavy Industries, Fincantieri, Damen Shipyards Group, and Mitsubishi Heavy Industries focusing on innovation, eco-friendly vessels, and modern shipyard expansion.
- Restraints include high capital expenditure for shipbuilding, volatile fuel prices, strict regulatory compliance costs, and economic uncertainties affecting shipping demand.
- Regional analysis indicates Asia-Pacific leads production with China, South Korea, and Japan as major hubs, while North America and Europe focus on advanced ship design and naval modernization.
- Opportunities exist in retrofitting existing fleets with eco-friendly technologies, offshore wind support vessels, and growth in cruise, ferry, and specialized cargo ships globally.
Market Drivers
Rising Global Trade and Seaborne Transportation
The Marine Vessels market benefits from rising global trade volumes and demand for seaborne transport. Containerized shipping continues to dominate cross-border commerce due to its cost efficiency and scalability. It supports the movement of raw materials, manufactured goods, and energy resources across major regions. Ports expand capacity to manage larger vessels, fueling demand for advanced fleets. The growth of e-commerce increases reliance on reliable shipping networks. Shipbuilders and operators invest in modern designs to handle rising cargo demand. This driver remains central to the industry’s steady expansion.
- For instance, In 2023, the Mediterranean Shipping Company (MSC) remained the world's largest container fleet, surpassing 5 million TEU in May and introducing some of the world's largest container ships, including the MSC Irinaclass, with capacities up to 24,346 TEU. The company's fleet continued to expand, exceeding 6 million TEU by mid-2024 and officially reaching 900 vessels with a total capacity of 6.47 million TEU by April 2025. The new ultra-large vessels delivered in 2023 briefly held the title of the world's largest container vessels by capacity.
Advancement in Propulsion and Energy Efficiency
The Marine Vessels market grows through innovation in propulsion systems and fuel efficiency technologies. Shipowners adopt dual-fuel engines and LNG propulsion to reduce emissions. It aligns with global regulations on sulfur oxide and carbon output. Advanced hull designs and hybrid power integration improve operational performance. Digital tools enhance fuel monitoring and optimize voyage planning. The drive for lower operating costs accelerates adoption of energy-efficient solutions. These factors reinforce competitiveness in a highly regulated market.
- For instance, Wärtsilä's portfolio of dual-fuel engines can run on LNG, marine diesel, or other conventional or alternative fuels like biofuel. By November 2012, the company had already delivered over 2,000 gas-fueled engines to the marine industry
Strengthening Regulatory Compliance and Safety Standards
The Marine Vessels market evolves with stricter international regulations on environmental and safety performance. The International Maritime Organization enforces rules on emissions, ballast water, and fuel usage. It compels operators to upgrade or retrofit existing fleets. New shipbuilding projects focus on sustainable materials and advanced onboard safety systems. Enforcement of safety standards ensures reduced risk in passenger and cargo operations. Governments and port authorities support compliance through incentive programs. This environment drives continuous technological and operational improvements.
Expansion of Offshore and Passenger Segments
The Marine Vessels market gains momentum from offshore exploration and passenger transport growth. Offshore vessels remain vital for oil, gas, and wind energy projects. It drives demand for specialized ships with high endurance and advanced equipment. Passenger ships and cruise liners recover strongly with rising tourism activities. Emerging economies invest in coastal and inland water transport infrastructure. Ferry networks expand to support urban mobility and island connectivity. Both offshore and passenger categories contribute significantly to long-term industry demand.
Market Trends
Adoption of Green Propulsion Technologies T
he Marine Vessels market reflects a strong shift toward green propulsion and alternative fuels. LNG, hydrogen, and biofuels gain traction as viable options for reducing emissions. It aligns with global decarbonization targets and regulatory frameworks. Hybrid and fully electric propulsion systems are under development for short-sea shipping and ferries. Shipbuilders focus on integrating low-carbon engines into new fleets. Operators prioritize vessels that can meet future environmental standards. This trend highlights sustainability as a key driver of ship design.
- For instance, Hyundai Heavy Industries (HHI), which is part of the HD Hyundai group, develops and manufactures ballast water treatment systems (BWTS) such as the HiBallast (electrolysis-based) and EcoBallast (UV-based) models to help ships comply with environmental standards. In 2011, HHI announced that it had received orders for BWTS installations on 30 ships. By 2023, HD Hyundai had cumulatively delivered over 2,300 ships to 335 clients across 51 countries since its inception. The company continues to offer its BWTS for both newbuilds and retrofits to meet international maritime regulations.
Integration of Smart and Digital Solutions
The Marine Vessels market advances with digitalization and smart shipping technologies. Fleet operators invest in IoT platforms, AI analytics, and predictive maintenance systems. It enhances fuel efficiency, safety, and voyage planning accuracy. Remote monitoring and automation reduce crew workload and operational risks. Cybersecurity measures gain importance to protect vessel data and navigation systems. Digital twins and simulation tools improve ship design and performance evaluation. This trend supports higher efficiency and competitiveness in global shipping operations.
- For instance, In 2023, Carnival Corporation operated a fleet of 93 cruise ships and carried approximately 12.5 million guests globally. The company's 2023 Sustainability Report confirms it "delivered unforgettable happiness to 12.5 million guests". Also during 2023, the company underwent a corporate restructuring in June while operating its combined fleet of 93 ships.
Growth of Autonomous and Unmanned Vessels
The Marine Vessels market experiences rising investment in autonomous ship technologies. Companies explore fully unmanned cargo ships for specific trade routes. It improves operational safety and reduces crew-related costs. Sensor-based navigation and advanced control systems enable safer long-distance voyages. Pilot projects test autonomous vessels across Europe, Asia, and North America. Regulators evaluate frameworks to integrate unmanned ships into existing maritime law. This trend points toward a gradual but impactful industry transformation.
Expansion in Offshore Renewable Support Vessels
The Marine Vessels market grows with offshore renewable energy developments, especially wind power. Demand rises for service operation vessels and cable-laying ships. It supports large-scale offshore wind projects in Europe, China, and the United States. Shipbuilders design specialized vessels equipped with dynamic positioning and heavy-lift capacity. The offshore renewable sector strengthens ties between shipbuilding and energy industries. Governments encourage investment in green maritime infrastructure. This trend underlines the strategic role of vessels in clean energy transition.
Market Challenges Analysis
High Operating Costs and Fuel Price Volatility
The Marine Vessels market faces challenges from high operating expenses and volatile fuel prices. Shipowners manage costs linked to crew, port charges, and insurance while addressing maintenance needs. It becomes more complex with global fluctuations in bunker fuel prices. The transition to cleaner fuels such as LNG and hydrogen demands major capital investment. Smaller operators struggle to compete with large fleets that benefit from economies of scale. Rising costs place pressure on freight rates and profitability. This challenge forces companies to seek efficiency through technology and optimized operations.
Regulatory Pressure and Environmental Compliance
The Marine Vessels market encounters strong pressure from evolving environmental regulations. The International Maritime Organization enforces stricter emission rules, driving costly fleet upgrades and retrofits. It creates uncertainty for operators unsure of future fuel adoption pathways. Non-compliance risks heavy fines, restricted port access, and reputational damage. Developing countries find compliance especially difficult due to limited access to advanced shipbuilding technologies. Continuous investment in research, design, and retrofitting remains necessary to meet international standards. This regulatory challenge reshapes long-term strategies across the global maritime industry.
Market Opportunities
Rising Demand for Energy-Efficient and Eco-Friendly Vessels
The Marine Vessels market creates opportunities through the rising demand for energy-efficient ships. Shipowners prioritize vessels with hybrid propulsion, LNG systems, and optimized hull designs. It positions companies to align with global carbon reduction mandates. Eco-friendly designs gain preference in procurement decisions from governments and commercial operators. Shipyards capable of delivering low-emission fleets secure long-term contracts. Growing interest in green shipping corridors further boosts demand for sustainable vessels. This opportunity favors firms investing in innovation and compliance-ready solutions.
Expansion in Offshore Energy and Passenger Transport
The Marine Vessels market benefits from opportunities in offshore exploration and renewable energy. Service vessels, cable layers, and heavy-lift ships are critical for offshore wind development. It strengthens collaboration between the maritime and energy industries. Cruise liners and passenger ferries also experience renewed demand with increasing tourism. Governments in emerging economies invest in ferry systems to improve coastal transport. Advanced passenger vessels with safety and digital features meet evolving traveler expectations. This opportunity expands growth across both energy and passenger transport segments.
Market Segmentation Analysis:
By Ship:
Ship type, covering container ships, passenger ships, bulk carriers, tankers, offshore ships, specialty vessels, general cargo ships, and others. Container ships remain dominant due to their critical role in global trade and e-commerce logistics. It supports large cargo volumes with efficiency, making them essential for cross-border commerce. Passenger ships, including ferries and cruise liners, show steady recovery with growing tourism and rising demand for urban water transport. Bulk carriers and tankers serve resource and energy supply chains, while offshore ships expand in support of oil, gas, and renewable projects. Specialty vessels and general cargo ships fulfill niche demands across defense, research, and regional trade, broadening the segment scope.
- For instance, In 2020, NYK Line introduced Japan’s first LNG-fueled car carrier, the Sakura Leader, with a capacity of approximately 7,000 vehicles. The vessel was named in September and officially delivered to NYK in October of the same year. Built by Shin Kurushima Dockyard, the Sakura Leader was the first large LNG-fueled PCTC constructed in Japan.
By System:
The Marine Vessels market includes propulsion, control, electrical, outer structure, power generator, deck machinery, and others. Propulsion systems lead the segment with strong adoption of LNG, hybrid, and dual-fuel engines to meet emission rules. It ensures compliance while lowering operating costs for shipowners. Control systems and electrical systems advance with automation, digital monitoring, and IoT-enabled solutions that improve navigation and efficiency. Outer structures emphasize lightweight, durable materials to boost fuel economy and performance. Power generators adapt to hybrid and renewable integration, while deck machinery evolves for safer and faster operations. Each system plays a critical role in modernizing fleets and ensuring compliance with global standards.
- For instance, Maersk deployed its Remote Container Management (RCM) system across over 380,000 of its refrigerated containers by December 2019, covering 99% of its reefer fleet.
By Solution:
The Marine Vessels market is classified into line fit and retrofit. Line fit dominates as shipbuilders integrate advanced propulsion, automation, and energy-saving systems into new vessels. It reflects the demand for future-ready fleets designed for efficiency and compliance. Retrofit solutions gain importance as existing ships adapt to new environmental and safety regulations. Operators invest in upgrades to extend vessel lifecycles and meet stricter emission norms. This balance between line fit and retrofit ensures both new construction and existing fleet modernization remain essential growth avenues. Together, these segments shape the industry’s long-term transformation.
Segments:
Based on Ship:
- Container Ships
- Passenger Ships
- Bulk Carriers
- Tankers
- Offshore Ships
- Specialty Vessel
- General Cargo Ship
- Others
Based on System:
- Propulsion System
- Control System
- Electrical System
- Outer Structure
- Power Generator System
- Deck Machinery
- Others
Based on Solution:
- Line Fit
- Retro Fit
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a market share of 27% in the Marine Vessels market. The region benefits from strong demand in commercial shipping, defense modernization, and offshore energy support. It invests heavily in modern shipbuilding facilities and advanced propulsion systems to meet international environmental compliance. The United States drives regional growth with its naval expansion and continuous focus on LNG-powered vessels. Canada strengthens the segment through investments in Arctic-capable vessels, icebreakers, and port infrastructure upgrades. It also benefits from rising demand for cruise ships along the East and West Coasts, with Alaska routes gaining popularity. North America demonstrates steady growth through integration of smart ship technologies and government-backed modernization programs, keeping the fleet competitive on a global scale.
Europe
Europe accounts for 31% of the Marine Vessels market, reflecting its strong role in commercial and passenger shipping. The region leads in green shipbuilding, with widespread adoption of LNG, hybrid, and hydrogen-fueled vessels. It benefits from a strong network of ports and shipyards in countries like Germany, Norway, Denmark, and Italy. The cruise sector plays a major role, as European operators invest in next-generation cruise liners with digital and sustainable systems. Offshore wind expansion also supports demand for specialized vessels, including service operation ships and cable layers. It aligns with strict European Union maritime emission targets, pushing faster adoption of green technologies. Europe’s focus on digital monitoring, automation, and compliance ensures its fleets remain technologically advanced and environmentally sustainable.
Asia-Pacific
Asia-Pacific holds the largest market share of 34% in the Marine Vessels market. The region dominates shipbuilding, with China, South Korea, and Japan accounting for a majority of global vessel construction. China expands rapidly with new shipyards and large-scale container ship production, while South Korea specializes in LNG carriers and advanced tankers. Japan emphasizes innovation in fuel-efficient and autonomous ships. It benefits from strong export activities, manufacturing hubs, and increasing seaborne trade routes. Growing demand for passenger ferries and inland water transport in Southeast Asia further supports the segment. The region invests significantly in next-generation propulsion and automation systems, consolidating its leadership in both volume and technology adoption across global shipping markets.
Latin America
Latin America secures a market share of 5% in the Marine Vessels market. The region focuses on commercial shipping, offshore oil exploration, and port modernization projects. Brazil plays a leading role with investments in offshore vessels to support pre-salt oilfield activities. Mexico advances with upgrades in its naval and commercial fleets. It also witnesses growth in regional passenger transport systems, supported by government initiatives to improve connectivity. The region adopts modernization programs, though at a slower pace compared to Asia-Pacific and Europe. Limited shipbuilding capacity challenges expansion, yet offshore exploration and rising trade volumes continue to create steady demand. Latin America’s reliance on imports and energy shipping highlights its growing importance in the industry.
Middle East & Africa
The Middle East & Africa holds a market share of 3% in the Marine Vessels market. The region demonstrates steady demand driven by energy exports, offshore exploration, and naval expansion. Gulf nations like Saudi Arabia and the UAE invest in port infrastructure and modern fleets to support growing oil and gas shipments. Africa strengthens its shipping sector through government-backed projects to modernize ports and improve regional connectivity. It faces challenges of limited shipbuilding capacity, relying heavily on imports of advanced vessels. Offshore oil exploration and emerging renewable energy projects increase the need for specialized vessels. It highlights opportunities for international shipbuilders to expand their footprint through partnerships and investments in the region.
Key Player Analysis
- Meyer Werft
- Austal
- Navantia
- Damen Shipyards Group
- HII
- Mitsubishi Heavy Industries
- General Dynamics NASSCO
- Lurssen
- Garden Reach Shipbuilders and Engineers
- Cochin Shipyard
- SHI-MCI
- Babcock International Group
- Fincantieri
- China Shipbuilding Industry Corporation
- Hyundai Heavy Industries
- Meyer Turku
- Japan Marine United Corporation
Competitive Analysis
The Marine Vessels market features strong competition among leading players such as Austal, Babcock International Group, China Shipbuilding Industry Corporation, Cochin Shipyard, Damen Shipyards Group, Fincantieri, Garden Reach Shipbuilders and Engineers, General Dynamics NASSCO, HII, Hyundai Heavy Industries, Japan Marine United Corporation, Lurssen, Meyer Turku, Meyer Werft, Mitsubishi Heavy Industries, Navantia, and SHI-MCI. Competition is shaped by advanced shipbuilding capabilities, innovation in propulsion systems, and compliance with international emission standards. Companies emphasize LNG, hybrid, and hydrogen-fueled vessel development to strengthen their market positioning. It creates opportunities to secure contracts with both commercial and naval sectors. The focus on digitalization, smart ship solutions, and predictive maintenance platforms enhances operational reliability and efficiency. Shipyards invest in modern facilities and R&D to remain competitive in specialized segments such as offshore support, cruise liners, and naval vessels. The market shows increasing preference for eco-friendly ships and advanced designs, which drives heavy investment in research and retrofitting. Established companies with global shipyard networks and diversified portfolios maintain a strong advantage, while regional players strengthen presence through government-backed programs. The competitive landscape highlights a balance between large-scale global players and regional builders focused on specialized needs. This dynamic fosters continuous innovation and capacity expansion across the industry.
Recent Developments
- In August 2025, Austal was approved as Australia’s Strategic Shipbuilder under a Strategic Shipbuilding Agreement with the Commonwealth of Australia, a major milestone supporting long-term orderbooks for facilities in Western Australia. Austal is now the prime contractor for the Landing Craft Medium and Landing Craft Heavy programs under this agreement.
- In April 2025, Fincantieri launched Fincantieri Ingenium with Accenture to accelerate digital transformation in cruise, defense, and port infrastructure sectors
- In June 2024, RightShip joined forces with Green Marine, an environmental certification program for the North American and European maritime industries.
Report Coverage
The research report offers an in-depth analysis based on Ship, System, Solution and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for efficient container shipping.
- Adoption of LNG, hydrogen, and hybrid propulsion systems will accelerate across fleets.
- Cruise and passenger ship orders will grow with recovery in global tourism.
- Offshore wind projects will create steady demand for service operation vessels.
- Automation and smart ship technologies will improve operational efficiency and safety.
- Retrofits will remain essential to meet emission and safety compliance standards.
- Asia-Pacific will strengthen dominance in global shipbuilding and technology integration.
- Naval modernization programs will support investments in advanced military vessels.
- Digital platforms for predictive maintenance and monitoring will gain wider adoption.
- Sustainable ship design and eco-friendly operations will remain a central industry priority.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Trade and Seaborne Transportation
Increasing global trade volumes and the dominance of containerized shipping are fueling demand for new and advanced marine vessels. Ports are expanding capacity and shipowners are investing in modern fleets to efficiently handle larger cargo volumes and support the growth of e-commerce.
Advancement in Propulsion and Energy Efficiency
Innovation in propulsion systems, such as LNG, hybrid, and hydrogen engines, is enabling shipowners to comply with stricter emission regulations while reducing operating costs. Adoption of energy-efficient technologies and digital tools for fuel monitoring is driving fleet modernization.
Strengthening Regulatory Compliance and Safety Standards
Stricter international regulations on emissions, ballast water, and safety are compelling operators to upgrade or retrofit vessels. This regulatory environment is driving continuous investment in sustainable ship design and advanced onboard safety systems.
Expansion of Offshore and Passenger Segments
Growth in offshore energy projects and the recovery of global tourism are increasing demand for specialized offshore vessels and passenger ships. Investments in coastal and inland water transport infrastructure are further supporting market expansion.
Adoption of Smart and Digital Ship Technologies
The integration of IoT, AI analytics, and predictive maintenance systems is enhancing operational efficiency, safety, and navigation. Digitalization supports fleet competitiveness and enables compliance with evolving industry standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Marine Vessels market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Marine Vessels Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Marine Vessels market?
Who are the leading companies in the Marine Vessels Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Ship
- 1.2.1 Container Ships
- 1.2.2 Passenger Ships
- 1.2.3 Bulk Carriers
- 1.2.4 Tankers
- 1.2.5 Offshore Ships
- 1.2.6 Specialty Vessel
- 1.2.7 General Cargo Ship
- 1.2.8 Others
- 1.3 By System
- 1.3.1 Propulsion System
- 1.3.2 Control System
- 1.3.3 Electrical System
- 1.3.4 Outer Structure
- 1.3.5 Power Generator System
- 1.3.6 Deck Machinery
- 1.3.7 Others
- 1.4 By Solution
- 1.4.1 Line Fit
- 1.4.2 Retro Fit
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 114.08 Billion → 2032: USD 146.77 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Marine Vessels Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Marine Vessels Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Marine Vessels Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Marine Vessels Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Marine Vessels Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Marine Vessels Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Marine Vessels Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Marine Vessels Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 114.08 Billion → 2032: USD 146.77 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Marine Vessels Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Ship - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Container Ships
- 12.3.7.2 Passenger Ships
- 12.3.7.3 Bulk Carriers
- 12.3.7.4 Tankers
- 12.3.7.5 Offshore Ships
- 12.3.7.6 Specialty Vessel
- 12.3.7.7 General Cargo Ship
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By System - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Propulsion System
- 12.4.7.2 Control System
- 12.4.7.3 Electrical System
- 12.4.7.4 Outer Structure
- 12.4.7.5 Power Generator System
- 12.4.7.6 Deck Machinery
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Solution - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Line Fit
- 12.5.7.2 Retro Fit
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Marine Vessels Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Marine Vessels Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Marine Vessels Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Hyundai Heavy Industries
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Fincantieri
- 17.4 Damen Shipyards Group
- 17.5 Mitsubishi Heavy Industries
- 17.6 Austal
- 17.7 Babcock International Group
- 17.8 China Shipbuilding Industry Corporation
- 17.9 General Dynamics NASSCO
- 17.10 Meyer Werft
- 17.11 Navantia
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

