
Market overview
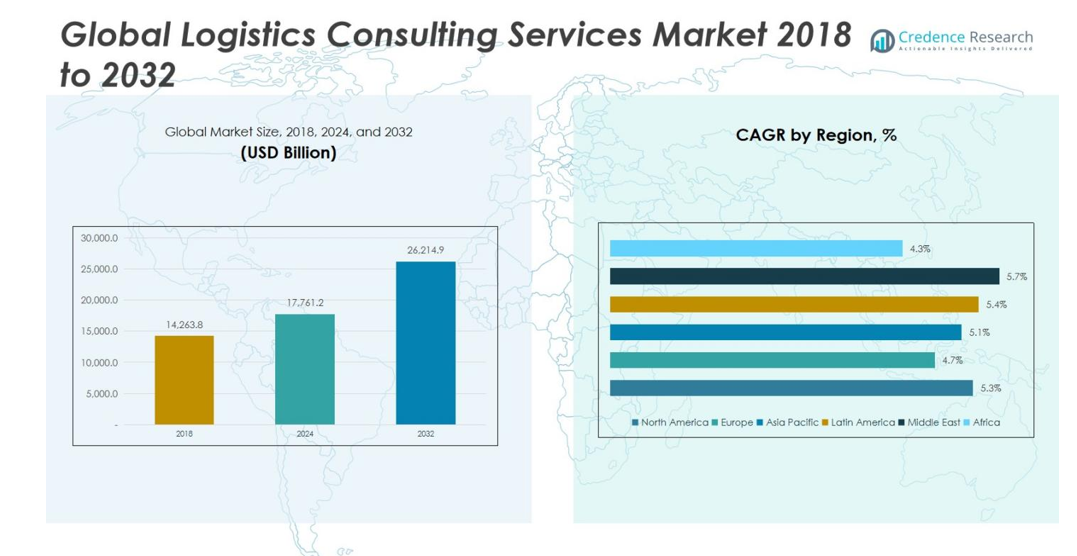
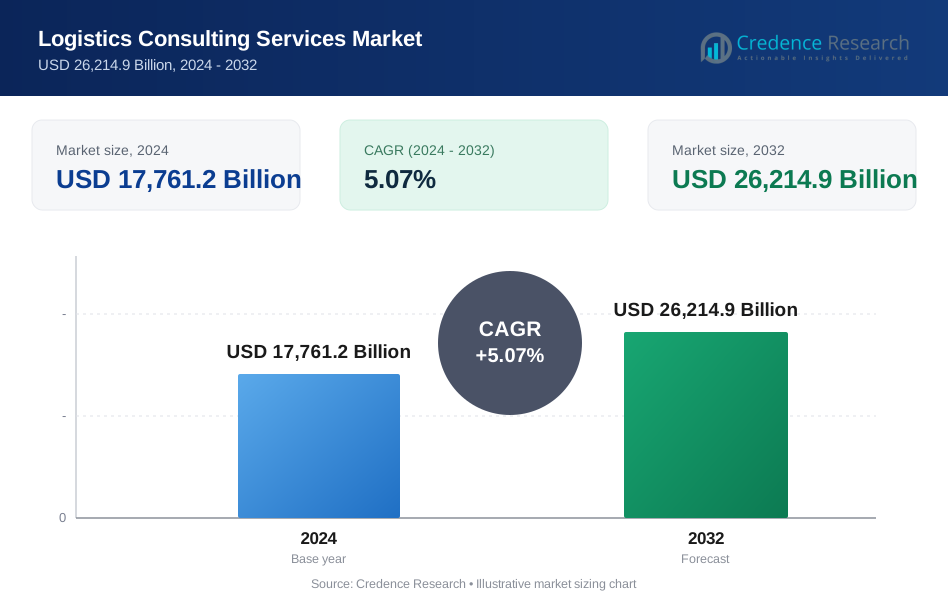
The Global Logistics Consulting Services Market was valued at USD 14,263.8 Billion in 2018, projected to reach USD 17,761.2 Billion by 2024, and is anticipated to grow to USD 26,214.9 Billion by 2032, at a CAGR of 5.07% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Logistics Consulting Services Market Size 2024 | USD 17,761.2 Billion |
| Logistics Consulting Services Market, CAGR | 5.07% |
| Logistics Consulting Services Market Size 2032 | USD 26,214.9 Billion |
The Global Logistics Consulting Services Market is dominated by leading players such as Bain & Company, KPMG International, Clarkston Co., Logistics Bureau, and The Supply Chain Consulting Group. These companies offer a broad range of consulting services, including supply chain strategy development, transportation optimization, and logistics network design. In 2024, North America holds the largest market share at approximately 18%, benefiting from its advanced infrastructure and demand for supply chain optimization across industries. Europe follows closely with a 17% share, driven by increasing investments in sustainability and digital transformation. The Asia Pacific region is the fastest-growing, capturing around 28% of the market, with robust growth fueled by e-commerce, manufacturing, and infrastructure development, particularly in China and India. These regions remain key hubs, with consulting firms expanding their footprints to meet the rising demand for logistics optimization and technology-driven solutions.
Market Insights
- The Global Logistics Consulting Services Market recorded a value of USD 17,761.2 Billion in 2024 and is projected to grow to USD 26,214.9 Billion by 2032, exhibiting a CAGR of 5.07 %.
- Growth is fueled by increasing demand for supply‑chain strategy development now capturing 30 % of the services‑type segment share and the surge in e‑commerce and digital transformation across industries.
- Key trends include the rising deployment of IoT, AI and blockchain in logistics, and the expansion of remote and virtual consulting services (which together now account for around 40 % of delivery‑mode revenue).
- Market restraint arises from the complexity of global supply chains and heightened data‑security/privacy concerns, which slow adoption of advanced consulting engagements.
- Regionally, North America leads with an estimated 18 % market share, Europe follows with 17 %, and Asia‑Pacific commands the largest growth trajectory with approximately 28 % share, driven by rapid infrastructure and e‑commerce evolution.
Market Segmentation Analysis:
By Services Type
Supply Chain Strategy Development holds a dominant position within the services type segment, accounting for 30% of the market share. This growth is primarily driven by the increasing complexity of global supply chains and the rising need for businesses to enhance operational resilience and cost-efficiency. Companies are increasingly seeking expert advice on aligning their supply chains with evolving market dynamics, such as nearshoring, sustainability practices, and digital transformation. Consultants offer services ranging from strategic roadmaps to scenario modelling, helping firms enhance supply chain agility and performance.
- For instance, Procter & Gamble employs a collaborative supply chain strategy by sharing demand forecasts and product development insights with suppliers, which streamlines processes and reduces lead times.
By Consulting Delivery Mode
On-site consulting services dominate the delivery mode segment with 60% market share. This preference stems from the need for hands-on engagement and in-person workshops, where consultants work closely with client teams to implement best practices, optimize logistics operations, and design custom solutions tailored to business requirements. The high share of on-site services highlights the importance of direct, real-time collaboration for complex transformation projects and network redesigns, which benefit from immediate, localized expertise and support.
- For instance, Deloitte frequently emphasizes on-site workshops to help clients implement process optimization and supply chain redesign, enabling real-time problem solving and customized solutions.
By Enterprise Size
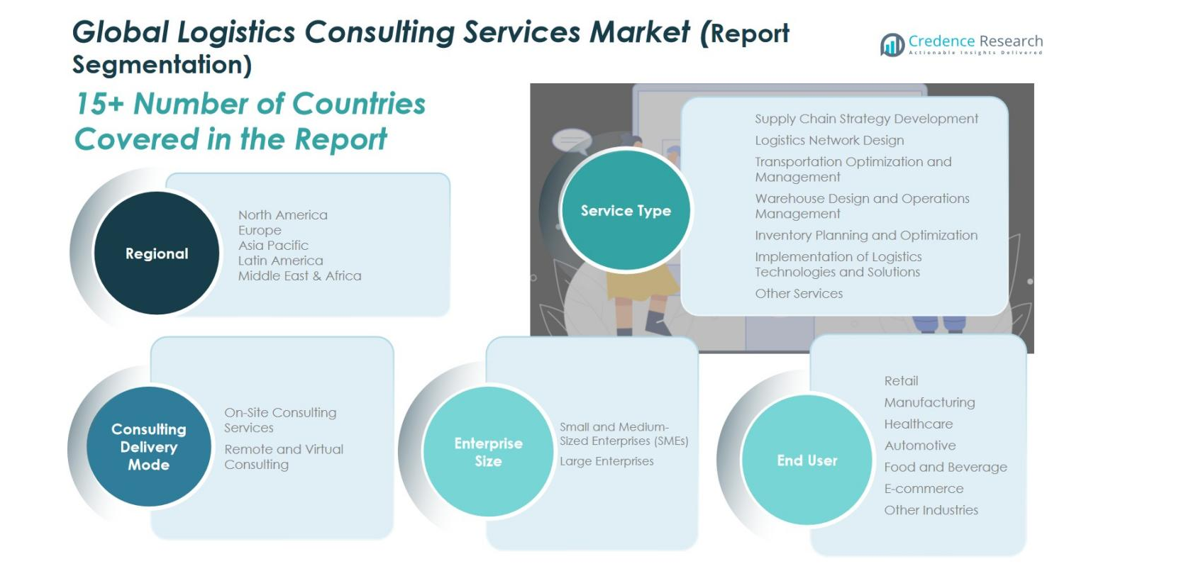
Large Enterprises lead the enterprise size segment, capturing 70% of the market share. These organizations tend to have more complex logistics needs due to their global reach, multi-channel distribution networks, and substantial operational scale. Large firms invest heavily in logistics consulting to optimize their supply chains, enhance transportation efficiency, and implement advanced technologies. This segment is driven by a push for digital transformation, risk mitigation strategies, and network optimization to stay competitive in the rapidly evolving global market.
Key Growth Drivers
Increasing Demand for Supply Chain Optimization
The growing complexity of global supply chains is driving businesses to seek professional logistics consulting services. Companies are under increasing pressure to streamline their supply chains to reduce costs, enhance operational efficiency, and improve service delivery. As supply chains face challenges such as geopolitical risks, fluctuating demand, and regulatory pressures, businesses are turning to logistics consultants for expert guidance on redesigning their supply chains, implementing digital solutions, and optimizing workflows to stay competitive and agile in the global marketplace.
- For instance, DB Schenker has leveraged Microsoft Azure’s cloud platform to integrate physical logistics with real-time big-data solutions, enhancing supply chain performance and operational efficiency.
Technological Advancements in Logistics
The rapid adoption of digital technologies such as Artificial Intelligence (AI), the Internet of Things (IoT), and blockchain is a key growth driver in the logistics consulting services market. These technologies offer significant opportunities to improve supply chain visibility, optimize routes, predict disruptions, and reduce costs. Logistics consultants are increasingly sought after to help companies integrate advanced technologies into their operations, ensuring seamless data flow, real-time decision-making, and enhanced transparency. As technology continues to evolve, the demand for expertise in implementing cutting-edge solutions is expanding across industries.
- For instance, Tata Consultancy Services (TCS) has integrated AI and cloud capabilities in its AI.Cloud unit, enabling clients to optimize supply chain operations with AI-driven insights and automation.
E-Commerce Growth and Consumer Expectations
The explosive growth of e-commerce is a major driver of logistics consulting services. As online shopping continues to surge, businesses are facing pressure to meet increasingly demanding customer expectations for faster delivery times, greater inventory visibility, and seamless return processes. Logistics consultants are helping companies optimize their supply chains to meet the fast-paced, customer-centric requirements of the e-commerce industry. This shift is driving the need for more agile, automated, and scalable logistics solutions, creating new opportunities for logistics consulting firms.
Key Trends & Opportunities
Focus on Sustainability and Green Logistics
Sustainability is becoming a significant focus in logistics consulting, as companies aim to reduce their carbon footprint and meet regulatory requirements for environmental protection. This trend is creating opportunities for logistics consultants to help businesses implement eco-friendly strategies such as sustainable packaging, electric vehicle (EV) fleets, and energy-efficient warehouse operations. As consumers demand greener practices and governments enforce stricter environmental regulations, consultants who specialize in sustainable logistics are in high demand, offering growth prospects in the logistics services sector.
- For instance, PreZero offers 360° sustainable packaging consulting, helping companies design packaging that meets regulatory, consumer, and environmental standards while improving recyclability and minimizing waste.
Adoption of Autonomous and Smart Technologies
The rise of autonomous vehicles, drones, and smart warehousing is an emerging trend that presents substantial opportunities in the logistics consulting services market. Consultants are increasingly engaged to advise businesses on integrating autonomous technologies that can improve efficiency, reduce human error, and lower operational costs. From last-mile delivery using drones to fully automated warehouses using robotics and AI, the logistics industry is evolving rapidly, and companies seek expert guidance to implement these technologies seamlessly while maintaining cost-effectiveness and service quality.
- For instance, Gatik’s Level 4 autonomous middle‑mile box trucks are operating without a safety driver along repetitive routes between distribution centres and retail locations, which illustrates how freight carriers are moving toward fully autonomous operations.
Key Challenges
Complexity of Global Supply Chains
One of the main challenges in the logistics consulting services market is the increasing complexity of global supply chains. Factors such as fluctuating tariffs, regulatory changes, political instability, and natural disasters can disrupt supply chain operations. Consultants are tasked with helping businesses navigate these challenges, but the fast-changing global landscape requires constant adaptation and agility. Managing the interconnectedness of global supply chains and ensuring smooth operations amid such complexities remains a significant hurdle for both consultants and their clients.
Data Security and Privacy Concerns
As logistics services become more digitized and reliant on advanced technologies, data security and privacy have become major concerns. The use of IoT devices, blockchain, and cloud-based platforms exposes supply chains to the risk of cyber-attacks, data breaches, and unauthorized access. Consulting firms are increasingly addressing these risks, but maintaining secure and compliant systems while embracing innovation poses a considerable challenge. Ensuring that sensitive customer and business data is protected against evolving threats is critical, and logistics consultants must constantly update security strategies to meet this demand.
Regional Analysis
North America
North America holds a significant share of the Global Logistics Consulting Services Market, with an estimated market share of 18%. The market size was USD 3,296.36 million in 2018 and is projected to reach USD 4,155.61 million by 2024, growing to USD 6,233.90 million by 2032, at a CAGR of 5.3%. The region benefits from a highly developed logistics infrastructure, advanced technological adoption, and robust supply chain management practices. The demand for logistics consulting is primarily driven by the increasing need for optimization in transportation, inventory management, and e-commerce supply chains, alongside investments in digital transformation and sustainability initiatives.
Europe
Europe accounts for 17% of the Global Logistics Consulting Services Market. The market was valued at USD 3,899.71 million in 2018 and is expected to grow to USD 4,763.05 million by 2024, reaching USD 6,847.33 million by 2032, with a CAGR of 4.7%. Europe’s steady demand for logistics consulting services is supported by its established supply chain infrastructure and a strong emphasis on sustainability. The region is increasingly adopting automation, AI, and IoT technologies, driving expansion in logistics networks to meet local and international market needs, along with regulatory pressures pushing for greener logistics practices.
Asia Pacific
Asia Pacific commands 28% of the Global Logistics Consulting Services Market, making it the fastest-growing region. The market size was USD 4,960.94 million in 2018 and is projected to reach USD 6,194.09 million by 2024, growing to USD 9,175.21 million by 2032, at a CAGR of 5.1%. The growth is primarily driven by the rapid expansion of e-commerce, increasing manufacturing output, and infrastructure development in countries like China and India. The demand for logistics consulting services is also driven by the need for supply chain optimization, digital transformation, and technological integration to support both domestic and global trade activities.
Latin America
Latin America holds 5% of the Global Logistics Consulting Services Market. The market was valued at USD 1,236.67 million in 2018 and is projected to grow to USD 1,566.54 million by 2024, reaching USD 2,364.58 million by 2032, with a CAGR of 5.4%. Increased trade integration with North America and other emerging markets is driving growth in the region. The demand for logistics consulting services is growing, particularly in transportation, warehousing, and inventory management, as businesses in Latin America seek to improve operational efficiency and support the growing e-commerce sector. Expanding logistics infrastructure is also contributing to market growth.
Middle East
The Middle East holds market share of 2% in the Global Logistics Consulting Services Market. Valued at USD 460.72 million in 2018, the market is expected to reach USD 594.24 million by 2024, and grow to USD 917.52 million by 2032, at a CAGR of 5.7%. The region’s growth is attributed to its strategic location as a logistics hub between Europe, Asia, and Africa. There is increasing demand for supply chain optimization in sectors such as oil and gas, retail, and e-commerce. Additionally, ongoing infrastructure projects, including smart city developments and port expansions, are driving the need for advanced logistics consulting services.
Africa
Africa's logistics consulting services market holds approximately 1.5% of the global market share. The market size was USD 409.37 million in 2018, projected to reach USD 487.67 million by 2024, and grow to USD 676.34 million by 2032, at a CAGR of 4.3%. Africa's market growth is supported by improving infrastructure, increasing intra-regional trade within the African Continental Free Trade Area (AfCFTA), and rising demand for logistics optimization solutions. While infrastructure development is ongoing, the growing e-commerce sector and efforts to streamline supply chain operations are pushing the demand for logistics consulting services, with a focus on sustainability and digital transformation.
Market Segmentations:
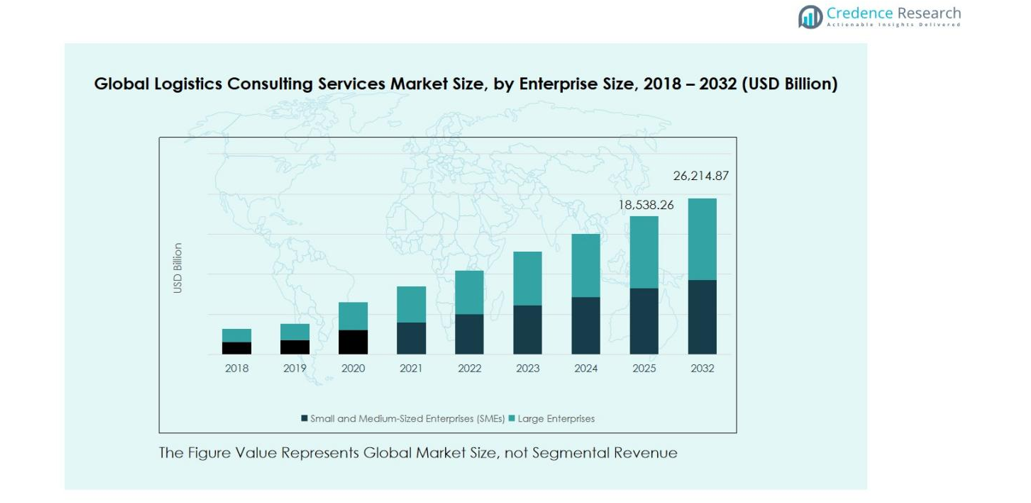
By Services Type:
- Supply Chain Strategy Development
- Logistics Network Design
- Transportation Optimization and Management
- Warehouse Design and Operations Management
- Inventory Planning and Optimization
- Implementation of Logistics Technologies and Solution
- Other Services
By Consulting Delivery Mode:
- On-Site Consulting Services
- Remote and Virtual Consulting
By Enterprise Size:
- Small and Medium-Sized Enterprises (SMEs)
- Large Enterprises
By End User:
- Retail
- Manufacturing
- Healthcare
- Automotive
- Food and Beverage
- E-commerce
- Other Industries
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Global Logistics Consulting Services Market is highly competitive, with key players such as Bain & Company, KPMG International, Clarkston Co., Logistics Bureau, and The Supply Chain Consulting Group leading the market. These firms offer a broad range of services, including supply chain strategy development, transportation optimization, and warehouse management. The market is characterized by the presence of both large multinational consulting firms and smaller, specialized players. As supply chains become more complex and the demand for digital solutions rises, firms are increasingly investing in advanced technologies such as AI, IoT, and blockchain to enhance service offerings. Companies are also focusing on sustainability, as clients seek green logistics solutions to meet regulatory requirements and consumer expectations. Furthermore, the growing trend towards e-commerce and globalization is pushing consulting firms to expand their capabilities and offerings. Strategic partnerships, acquisitions, and continuous innovation in logistics solutions are key tactics to stay competitive in this dynamic market.
Key Player Analysis
- Bain & Company
- YCP Group
- Clarkston Co
- Comcast Corp.
- KPMG International
- Logistics Bureau
- The Supply Chain Consulting Group
- Cybage
- Advatix
- Other Key Players
Recent Developments
- In March 2025, LOGISTEED, Ltd. launched a new Logistics DX Consulting Service in collaboration with its group company LOGISTEED Solutions, Ltd., covering full‑cycle logistics digital transformation from planning through execution.
- In February 2025, Peterson Energy Logistics introduced a dedicated global consultancy service targeted at the Asia‑Pacific & Middle East regions, focusing on resources, energy, minerals and heavy industries with a strong emphasis on sustainability and operational excellence.
- In March 2025, Investcorp acquired a majority stake in Miebach Logistik Holding GmbH (a global supply chain & logistics consultancy).
- In April 2025, Argano announced the acquisition of Netlogistik (a strategic advisory/consulting firm specializing in digital supply chain solutions) as part of its expansion into global logistics consulting services.
Report Coverage
The research report offers an in-depth analysis based on Services Type, Consulting Delivery Mode, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for logistics consulting services is expected to grow steadily, driven by increasing demand for supply chain optimization and digital transformation.
- Adoption of AI, IoT, and blockchain technologies in logistics will continue to be a major growth factor, enhancing operational efficiency and transparency.
- Sustainability initiatives will become a significant driver, with more businesses seeking green logistics solutions to comply with regulatory standards and meet consumer expectations.
- The e-commerce sector will remain a key contributor to market growth, as businesses seek to improve their logistics operations to meet rising consumer demands.
- The rise in global trade and shifting supply chain dynamics will lead to increased need for consulting services in network design, risk management, and strategy development.
- Small and medium-sized enterprises (SMEs) will increasingly invest in logistics consulting services to streamline operations and remain competitive in the global market.
- Integration of autonomous vehicles and drones in logistics will create new consulting opportunities, particularly in transportation and last-mile delivery optimization.
- Geographic expansion, particularly in emerging markets like Asia Pacific and Latin America, will offer untapped growth potential for logistics consulting firms.
- The growing complexity of supply chains and regulatory requirements will drive further demand for specialized consulting services, including compliance and risk management.
- Strategic partnerships, acquisitions, and alliances will remain critical for consulting firms to expand their service offerings and stay competitive in the evolving logistics landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Supply Chain Optimization
As global supply chains become more complex and face disruptions from geopolitical, regulatory, and market forces, companies are seeking logistics consulting services to streamline operations, reduce costs, and improve resilience. Consultants help businesses redesign supply chains, implement digital solutions, and optimize workflows to remain competitive.
Technological Advancements in Logistics
The rapid adoption of AI, IoT, and blockchain technologies is transforming logistics operations, driving demand for consulting expertise to integrate these solutions. Consultants enable clients to achieve real-time visibility, predictive analytics, and automation, which enhance efficiency and transparency across the supply chain.
E-Commerce Growth and Consumer Expectations
The surge in e-commerce has heightened expectations for faster deliveries, better inventory visibility, and seamless returns, pushing businesses to optimize their logistics networks. Consulting firms are instrumental in helping companies adapt to these demands by designing agile, scalable, and customer-centric logistics solutions.
Focus on Sustainability and Green Logistics
With increasing regulatory and consumer pressure for environmentally responsible practices, companies are turning to logistics consultants to develop and implement green logistics strategies. This includes sustainable packaging, energy-efficient warehousing, and low-emission transportation solutions, creating new consulting opportunities.
Expansion of Remote and Virtual Consulting Services
The shift toward remote and virtual consulting, accelerated by digital transformation, allows consulting firms to deliver expertise more flexibly and cost-effectively. This trend is expanding the market by making logistics consulting accessible to a broader range of clients, including SMEs and businesses in emerging markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Logistics Consulting Services Market?
At what Compound Annual Growth Rate is the Global Logistics Consulting Services Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Logistics Consulting Services Market?
What are some challenges faced by the Logistics Consulting Services Market?
Who are the major players in the Logistics Consulting Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Retail
- 1.2.2 Manufacturing
- 1.2.3 Healthcare
- 1.2.4 Automotive
- 1.2.5 Food and Beverage
- 1.2.6 E-commerce
- 1.2.7 Other Industries
- 1.3 By Services Type
- 1.3.1 Supply Chain Strategy Development
- 1.3.2 Logistics Network Design
- 1.3.3 Transportation Optimization and Management
- 1.3.4 Warehouse Design and Operations Management
- 1.3.5 Inventory Planning and Optimization
- 1.3.6 Implementation of Logistics Technologies and Solution
- 1.3.7 Other Services
- 1.4 By Enterprise Size
- 1.4.1 Small and Medium-Sized Enterprises (SMEs)
- 1.4.2 Large Enterprises
- 1.5 By Consulting Delivery Mode
- 1.5.1 On-Site Consulting Services
- 1.5.2 Remote and Virtual Consulting
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,761.2 Billion → 2032: USD 26,214.9 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Logistics Consulting Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Logistics Consulting Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Logistics Consulting Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Logistics Consulting Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Logistics Consulting Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Logistics Consulting Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Logistics Consulting Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Logistics Consulting Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,761.2 Billion → 2032: USD 26,214.9 Billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Logistics Consulting Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Retail
- 12.3.6.2 Manufacturing
- 12.3.6.3 Healthcare
- 12.3.6.4 Automotive
- 12.3.6.5 Food and Beverage
- 12.3.6.6 E-commerce
- 12.3.6.7 Other Industries
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Services Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Supply Chain Strategy Development
- 12.4.6.2 Logistics Network Design
- 12.4.6.3 Transportation Optimization and Management
- 12.4.6.4 Warehouse Design and Operations Management
- 12.4.6.5 Inventory Planning and Optimization
- 12.4.6.6 Implementation of Logistics Technologies and Solution
- 12.4.6.7 Other Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Small and Medium-Sized Enterprises (SMEs)
- 12.5.6.2 Large Enterprises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Consulting Delivery Mode - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 On-Site Consulting Services
- 12.6.6.2 Remote and Virtual Consulting
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Logistics Consulting Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Logistics Consulting Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Logistics Consulting Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Logistics Consulting Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bain & Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 KPMG International
- 18.4 Clarkston Consulting
- 18.5 Logistics Bureau
- 18.6 The Supply Chain Consulting Group
- 18.7 Deloitte
- 18.8 Accenture
- 18.9 PwC
- 18.10 EY
- 18.11 Miebach Consulting
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

