
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Anti-Cancer Drugs Market Size 2023 | USD 198.96 Billion |
| Anti-Cancer Drugs Market, CAGR | XX% |
| Anti-Cancer Drugs Market Size 2032 | USD 411.78 Billion |
Market Overview:
The global anti-cancer drugs market is poised for substantial growth, with projections indicating a rise to USD 411.78 billion by 2032, marking a significant increase from its 2023 valuation of USD 198.96 billion. This expansion is driven by several key factors, including the escalating prevalence of cancer worldwide, fueled by population growth, aging demographics, and lifestyle factors. Moreover, ongoing advancements in treatment options, particularly in areas such as immunotherapy and precision medicine, are revolutionizing cancer care, offering more effective and personalized therapies to patients. The growing support from governments and healthcare institutions, coupled with increasing healthcare expenditure globally, further propels market growth, creating a conducive environment for research, development, and patient access to anti-cancer drugs.
Emerging trends in the anti-cancer drugs market are reshaping the landscape and influencing future growth trajectories. The rise of precision medicine and personalized therapies is a notable trend, allowing for targeted treatments tailored to individual genetic profiles. Additionally, there is a growing focus on immuno-oncology drugs, harnessing the body's immune system to combat cancer, and significant advancements in drug delivery systems, aiming to enhance treatment efficacy while minimizing side effects. Moreover, the increasing adoption of biosimilars and continued consolidation through mergers and acquisitions within the pharmaceutical industry are expected to shape market dynamics in the coming years.
While the market presents significant opportunities for stakeholders, several challenges must be addressed to sustain growth and ensure equitable access to cancer treatments. High costs associated with drug development, stringent regulatory processes, and unequal access to treatment remain prominent challenges. However, innovative funding models, streamlined regulatory frameworks, and collaborative efforts among industry players, research institutions, and healthcare providers can help overcome these challenges and drive continued progress in the fight against cancer.
Market Drivers:
Growing Aging Population and Rising Cancer Burden
The aging population significantly contributes to the rising cancer burden, as older individuals are more susceptible to cellular mutations leading to cancer. This surge is underpinned by the escalating prevalence of cancer globally. The World Health Organization (WHO)’s cancer agency, the International Agency for Research on Cancer (IARC), released the latest estimates of the global burden of cancer. In 2022, there were an estimated 20 million new cancer cases and 9.7 million deaths. Consequently, this demographic shift expands the pool of patients in need of anti-cancer drugs, fueling market demand.
In India, senior citizens account for 14% of the total population, as per the Population Projections Report, 2020. This is estimated to increase to 20.8% by 2050. Consequently, the growing aging population in India further expands the pool of patients in need of anti-cancer drugs, fueling market demand.
Technological Advancements in the Pharmaceutical Industry
Technological advancements and ongoing discoveries in the pharmaceutical industry are key drivers propelling market growth. Innovations span various treatment modalities, including chemotherapy, targeted therapy, immunotherapy, and hormonal therapy. Targeted therapies, in particular, offer a personalized approach to cancer treatment by focusing on specific mutations or pathways involved in cancer cell growth, leading to more effective therapies with reduced side effects. Similarly, immunotherapy presents exciting breakthroughs by leveraging the body's immune system to combat cancer cells, potentially offering long-term remission and even cures.
Increasing Healthcare Expenditure and Public Awareness
The increasing allocation of healthcare expenditure globally, along with growing public awareness about cancer prevention and treatment options, further propels market expansion. Governments and private insurance companies are dedicating more resources to cancer treatment, making anti-cancer drugs more accessible to patients. Heightened awareness empowers individuals to seek early diagnosis and treatment, fostering greater demand for anti-cancer drugs. Moreover, advancements in diagnostic techniques, such as genetic testing and improved imaging technologies, enable earlier and more accurate cancer detection, facilitating timely treatment with anti-cancer drugs and potentially improving patient outcomes.
Unmet Medical Needs and Opportunities for Innovation
Despite significant progress, there remains a notable unmet medical need for effective treatments across various cancers. This presents a significant opportunity for pharmaceutical companies to develop novel anti-cancer drugs. Furthermore, there is a growing focus on orphan drugs targeting rare and aggressive cancers, catering to smaller patient populations but offering substantial potential for enhancing patient lives. These factors collectively underscore the multifaceted drivers behind the anticipated growth trajectory of the anti-cancer drugs market.
Market Trends:
Rise of Personalized Medicine and Targeted Therapies
There’s a growing shift towards personalized medicine, where treatments are tailored to the specific genetic makeup of a patient’s cancer. This trend is fueled by advancements in genomic profiling and the development of targeted therapies that attack specific cancer cell vulnerabilities. This approach offers a more effective treatment with potentially fewer side effects. The International Consortium for Personalised Medicine (ICPerMed) presents a vision of how personalized medicine (PM) will lead to the next generation of healthcare by 2030.
Immunotherapy’s Growing Prominence
Immunotherapy drugs are revolutionizing cancer treatment by harnessing the body’s own immune system to fight cancer cells. Checkpoint inhibitors, a type of immunotherapy, are showing remarkable results in treating various cancers. The success of these treatments is driving further research and development in this area, leading to a wider range of immunotherapy options. As of July 31, 2023, the FDA has approved 11 immune checkpoint inhibitors (ICIs), and there is at least one ICI approved for treating 20 cancer types.
Focus on Early Detection and Minimally Invasive Procedures
Early detection of cancer significantly improves treatment outcomes. Therefore, there’s a growing emphasis on developing and implementing effective early detection methods and minimally invasive procedures for cancer treatment. This includes advancements in liquid biopsies, which allow for easier and earlier cancer detection through blood tests.
Technological Advancements and Big Data Integration
Technological advancements like artificial intelligence (AI) and big data analytics are playing an increasingly crucial role in the development of new anti-cancer drugs. AI is being used to analyze vast amounts of clinical data to identify potential drug targets and accelerate drug discovery. Big data analysis helps researchers understand complex disease mechanisms and develop more effective treatment strategies.
Growing Demand for Biosimilars and Cost-Effectiveness: The high cost of cancer treatment is a major concern for patients and healthcare systems. The increasing availability of biosimilars, which are highly similar versions of existing biological drugs, offers a cost-effective alternative to expensive brand-name cancer drugs. This trend is expected to continue as more biosimilars enter the market, making treatment more accessible to a wider range of patients.
Market Restraints and Challenges:
- High Costs of Drug Development and Treatment: Developing and bringing new anti-cancer drugs to market is a highly expensive and time-consuming process. The research and development phase requires substantial investments in clinical trials, regulatory approvals, and manufacturing infrastructure. This translates to high costs per treatment, which can limit access for patients and strain healthcare budgets globally. Additionally, even established anti-cancer drugs can be very expensive, putting a financial burden on patients and healthcare systems.
- Limited Efficacy and Drug Resistance: While advancements in cancer treatment are ongoing, not all anti-cancer drugs are equally effective for all patients. Many cancers exhibit heterogeneity, meaning variations within the tumor itself. This can lead to limited efficacy of certain drugs for specific patient populations. Furthermore, cancer cells can develop resistance to medications over time, rendering previously effective treatments useless. Researchers are actively exploring ways to overcome drug resistance, but it remains a significant challenge in the anti-cancer drug market.
- Stringent Regulatory Requirements: The regulatory approval process for new anti-cancer drugs is rigorous and involves multiple stages of clinical trials to ensure safety and efficacy. This is crucial to safeguard patient well-being, but it can also lead to delays in bringing new and potentially life-saving treatments to patients. Additionally, navigating the complex regulatory landscape across different countries can be challenging for pharmaceutical companies, further hindering market access.
- Side Effects and Patient Compliance: Many anti-cancer drugs come with a range of severe side effects, such as nausea, fatigue, hair loss, and nerve damage. This can significantly impact a patient's quality of life and may lead to treatment non-compliance, hindering the effectiveness of the medication. Furthermore, some anti-cancer drugs require complex treatment regimens that can be difficult for patients to manage on their own. Strategies to manage side effects and improve patient adherence are crucial considerations in the anti-cancer drug market.
- Focus on Short-Term Profits Over Long-Term Innovation: The pharmaceutical industry often faces pressure to prioritize short-term profits over long-term research and development (R&D) efforts in targeted therapies and personalized medicine approaches. This can lead to a focus on developing drugs that offer faster returns on investment, potentially neglecting the pursuit of more innovative solutions that may have a greater long-term impact on patient outcomes
Recent Developments:
- In September 2023, Amgen reported data from a Phase Ib study of the CodeBreaK 101 clinical trial evaluating LUMAKRAS (sotorasib) in combination with carboplatin and pemetrexed for the treatment of adults with KRAS G12C-mutated advanced non-small cell lung cancer (NSCLC).
- In August 2023, researchers at the City of Hope, one of the leading cancer research and treatment centers in the United States, conducted a new study utilizing proliferating cell nuclear antigen (PCNA). This protein, previously considered challenging for targeted anti-cancer therapy, was used to develop a targeted chemotherapy that, in preclinical research, shows promise in completely eradicating all solid tumors.
- In March 2023, Pfizer acquired Seagen for USD 43.0 billion to invest in its cutting-edge anticancer therapeutics. Pfizer announced plans to scale its antibody-drug conjugate products, which use antibodies to deliver small molecule medications directly to tumor locations.
- In May 2022, Domain Therapeutics successfully raised USD 42 million in a Series A investment led by Panacea Venture, CTI Life Sciences, and 3B Future Health Fund. The company is developing anti-cancer medications that target G protein-coupled receptors (GPCRs), a subset of cell surface proteins. These GPCRs are crucial in helping cancers evade immune checkpoint inhibitor therapy and suppress the immune system.
- In June 2022, Bristol Myers Squibb and Turning Point Therapeutics, Inc. announced a definitive merger agreement for the acquisition of Turning Point Therapeutics. Turning Point Therapeutics is a clinical-stage precision oncology company with a pipeline of investigational medicines designed to target the most common mutations associated with oncogenesis.
- In April 2022, Novartis announced the (FDA) granted commercial licensure approval for its Durham, N.C. site, a multi-product gene therapy manufacturing facility. This approval allows the 170,000 square-foot facilities to make, test and release commercial Zolgensma, as well as produce gene therapy products for current and future clinical trials.
- In June 2021, Bayer AG announced an agreement to acquire Noria Therapeutics Inc. and PSMA Therapeutics Inc. This acquisition grants Bayer exclusive rights to the companies' investigational compounds, helping Bayer expand its oncology portfolio.
- In April 2021, Sanofi acquired Tidal Therapeutics, a pre-clinical biotech company developing an mRNA-based research platform. This acquisition will enable Sanofi to leverage this new technology to expand its research capabilities in oncology, immunology, and other disease areas.
Segments:
By Drug
- Targeted Therapy
- Chemotherapy
- Hormonal Therapy
- Immunotherapy
By Indication
- Lungs Cancer
- Colorectal Cancer
- Breast Cancer
- Liver Cancer
- Bladder Cancer
- Head & Neck Cancer
- Prostate Cancer
- Others
By Geography
- North America
- The U.S.
- Canada
- Europe
- The U.K.
- Germany
- France
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of the World
Key player:
- Hoffmann-La Roche Ltd
- Eli Lilly and Company
- Novartis AG
- Celgene Corporation
- Amgen Inc
- Pfizer Inc
- Bayer AG
- AstraZeneca
- Takeda Pharmaceutical Company Limited
Regional Analysis:
North America is currently the dominant player, holding the largest market share due to factors like a high prevalence of cancer, advanced healthcare infrastructure, and strong research and development efforts. Additionally, favorable government policies and high disposable income contribute to the strong market position in this region.
Europe follows closely behind North America, with a mature market driven by similar factors like established healthcare systems, significant investments in cancer research, and growing government support for novel therapies. However, stringent regulatory processes and price control measures might influence market growth to a certain extent.
Asia Pacific is projected to be the fastest-growing region in the anti-cancer drugs market. This growth is fueled by a rising prevalence of cancer due to aging populations and lifestyle changes. Additionally, increasing healthcare awareness, improving healthcare infrastructure, and growing disposable income in emerging economies within this region present significant opportunities for market expansion. Latin America and the Middle East & Africa are expected to experience moderate growth, driven by factors like rising healthcare expenditure and increasing government focus on improving cancer care access. However, limited access to advanced healthcare facilities and challenges in affordability might hinder market growth in these regions.
Future Outlook:
- Rising Cancer Prevalence: The increasing incidence of cancer globally will continue to drive demand for anti-cancer drugs.
- Aging Population: As the global population ages, the risk of cancer rises, further fueling market expansion.
- Advancements in Drug Discovery: Continuous research and development efforts will lead to the introduction of more targeted and effective anti-cancer drugs.
- Personalized Medicine: The growing focus on personalized medicine will create opportunities for tailored cancer treatment plans utilizing specific drug combinations.
- Immunotherapy Boom: Immunotherapy is expected to remain a prominent and rapidly evolving segment of the anti-cancer drug market.
- Technological Integration: Integration of artificial intelligence and big data analytics will accelerate drug discovery and development processes.
- Focus on Affordability: Growing concerns about healthcare costs will necessitate the development of cost-effective treatment options and improved drug accessibility.
- Emerging Markets Rise: The anti-cancer drugs market in developing economies is anticipated to witness significant growth due to rising disposable incomes and increasing healthcare infrastructure investments.
- Emphasis on Early Detection: Early cancer detection initiatives will likely lead to higher demand for diagnostic tools and targeted drugs for early-stage cancers.
- Biosimilars Market Expansion: The biosimilars market is expected to expand, offering more affordable alternatives to existing anti-cancer drugs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Aging Population and Rising Cancer Burden
The increasing proportion of elderly individuals globally is leading to a higher incidence of cancer, as older populations are more susceptible to cellular mutations. This demographic shift is expanding the patient pool and driving demand for anti-cancer drugs.
Technological Advancements in Treatment Modalities
Innovations in targeted therapy, immunotherapy, and precision medicine are enabling more effective and personalized cancer treatments. These advancements are improving patient outcomes and expanding the range of treatable cancers, fueling market growth.
Increasing Healthcare Expenditure and Public Awareness
Rising global healthcare spending and heightened public awareness about cancer prevention and treatment are making anti-cancer drugs more accessible. Early diagnosis and improved treatment options are increasing the uptake of these drugs.
Unmet Medical Needs and Opportunities for Innovation
Despite progress, many cancers still lack effective treatments, creating opportunities for pharmaceutical companies to develop novel drugs, including those targeting rare or aggressive cancers. This ongoing innovation is a key driver of market expansion.
Adoption of Biosimilars and Cost-Effective Therapies
The introduction and increasing acceptance of biosimilars are providing more affordable alternatives to expensive branded anti-cancer drugs. This is improving access to treatment, especially in emerging markets, and supporting overall market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What factors are driving the growth of the anti-cancer drugs market?
How do technological advancements contribute to the expansion of the market?
What role does the aging population play in the demand for anti-cancer drugs?
How are pharmaceutical companies addressing unmet medical needs in the anti-cancer drugs market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug
- 1.2.1 Targeted Therapy
- 1.2.2 Chemotherapy
- 1.2.3 Hormonal Therapy
- 1.2.4 Immunotherapy
- 1.3 By Indication
- 1.3.1 Lungs Cancer
- 1.3.2 Colorectal Cancer
- 1.3.3 Breast Cancer
- 1.3.4 Liver Cancer
- 1.3.5 Bladder Cancer
- 1.3.6 Head & Neck Cancer
- 1.3.7 Prostate Cancer
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
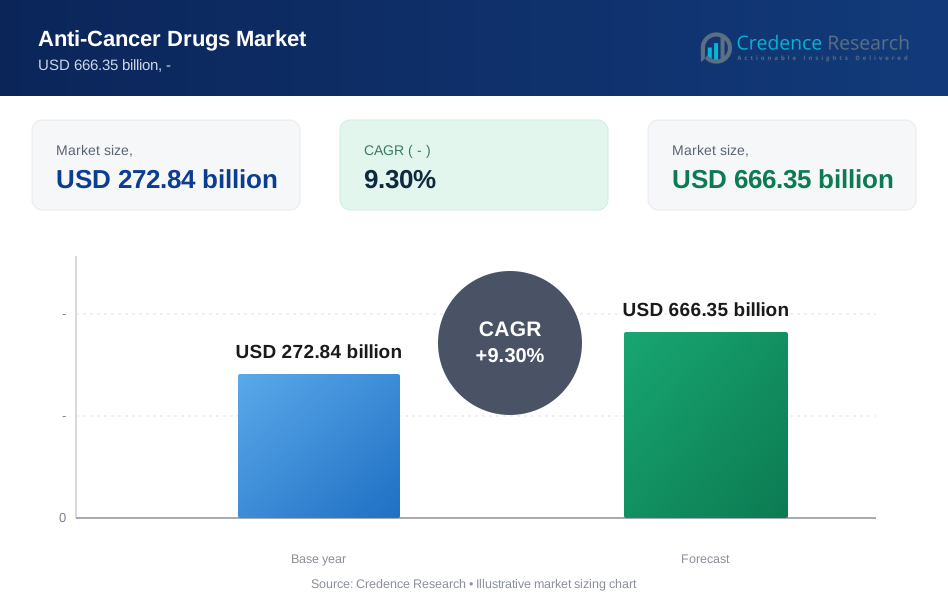
- 2.5.1 2032: USD 272.84 billion → Forecast year: USD 666.35 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti-Cancer Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti-Cancer Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti-Cancer Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti-Cancer Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti-Cancer Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti-Cancer Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti-Cancer Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti-Cancer Drugs Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 272.84 billion → Forecast year: USD 666.35 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti-Cancer Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Targeted Therapy
- 12.3.7.2 Chemotherapy
- 12.3.7.3 Hormonal Therapy
- 12.3.7.4 Immunotherapy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lungs Cancer
- 12.4.7.2 Colorectal Cancer
- 12.4.7.3 Breast Cancer
- 12.4.7.4 Liver Cancer
- 12.4.7.5 Bladder Cancer
- 12.4.7.6 Head & Neck Cancer
- 12.4.7.7 Prostate Cancer
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti-Cancer Drugs Geographic Market Outlook
- 13.1 Regional Market Size and Share, 2032
- 13.2 Regional Market Forecast
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Anti-Cancer Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Anti-Cancer Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2032
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Hoffmann-La Roche Ltd
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Eli Lilly and Company
- 17.4 Novartis AG
- 17.5 Celgene Corporation
- 17.6 Amgen Inc
- 17.7 Pfizer Inc
- 17.8 Bayer AG
- 17.9 AstraZeneca
- 17.10 Takeda Pharmaceutical Company Limited
- 17.11 Sanofi
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

