
Market Overview:
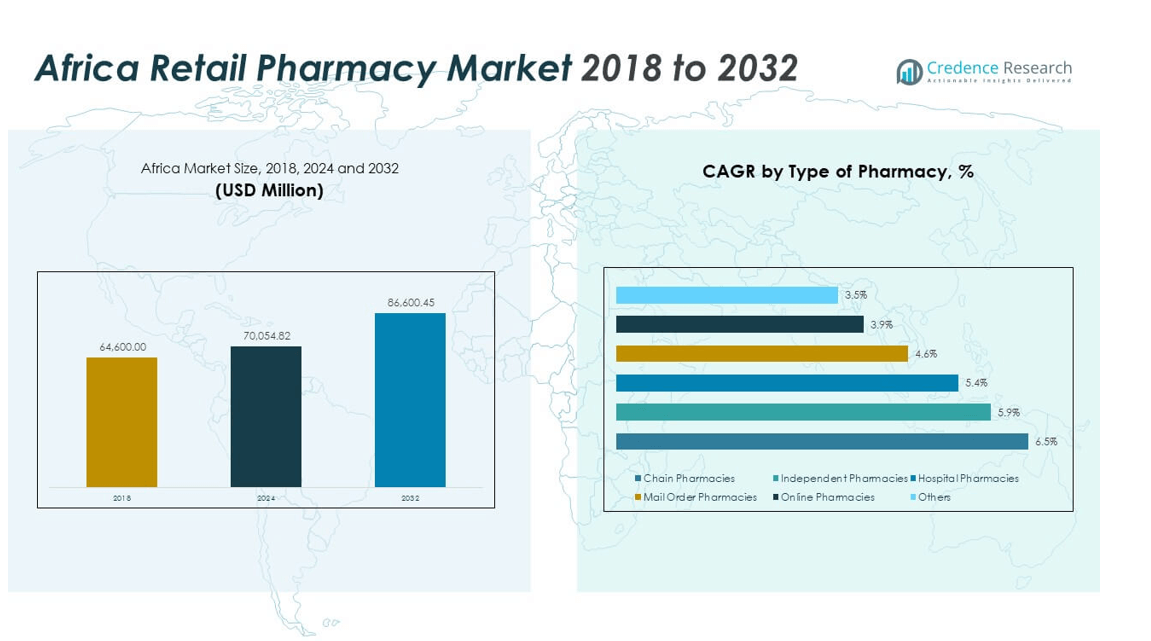
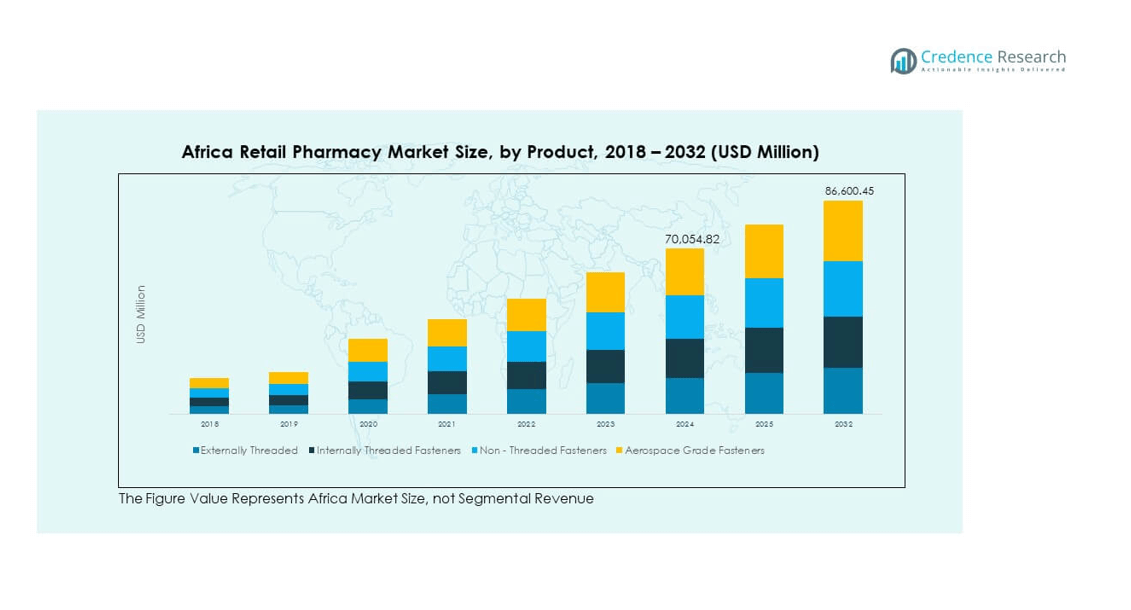
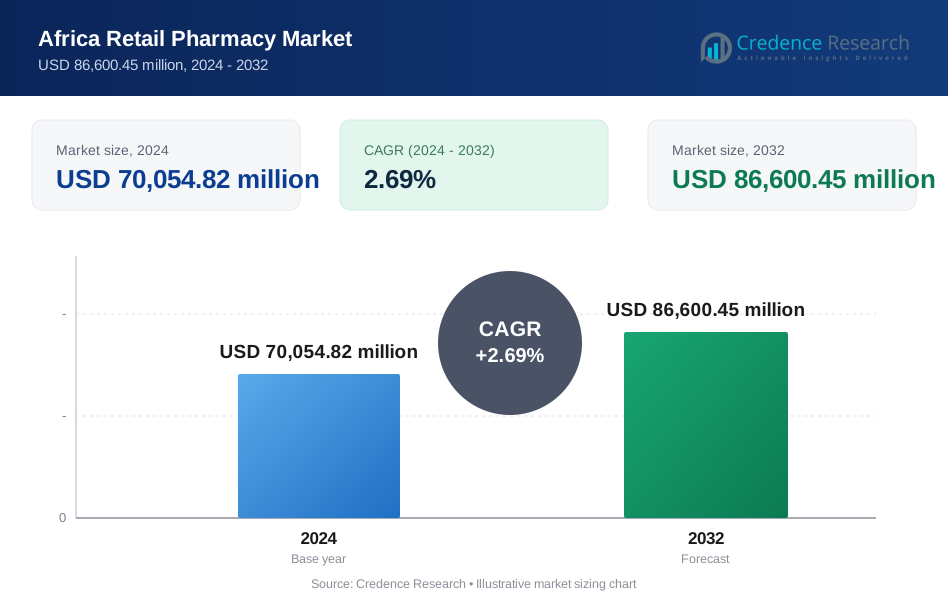
The Africa Retail Pharmacy Market size was valued at USD 68,600.00 million in 2018 to USD 70,054.82 million in 2024 and is anticipated to reach USD 86,600.45 million by 2032, at a CAGR of 2.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Africa Retail Pharmacy Market Size 2024 | USD 70,054.82 million |
| Africa Retail Pharmacy Market, CAGR | 2.69% |
| Africa Retail Pharmacy Market Size 2032 | USD 86,600.45 million |
Growing healthcare needs, increasing chronic disease cases, and expanding access to medicines are driving the Africa Retail Pharmacy Market. Urbanization and rising disposable incomes encourage more people to seek pharmacy-based healthcare solutions. Expanding health insurance coverage and government support for better drug distribution networks are also boosting retail pharmacy demand. Pharmacies are evolving into one-stop healthcare points offering prescription drugs, over-the-counter medicines, and wellness products. Digital transformation and e-pharmacy platforms further strengthen consumer accessibility, enhancing efficiency in healthcare delivery across the region.
Regionally, South Africa and Nigeria lead the Africa Retail Pharmacy Market due to advanced infrastructure and strong consumer demand. Kenya and Egypt are emerging markets, supported by growing investments in healthcare, rising population, and increasing access to modern retail channels. Francophone Africa is slowly adopting structured pharmacy models, but regulatory and supply chain challenges limit growth. North African nations benefit from stronger pharmaceutical manufacturing bases, while Sub-Saharan regions are seeing rapid growth as healthcare awareness spreads and governments invest in improving accessibility.
Market Insights:
- The Africa Retail Pharmacy Market was valued at USD 68,600.00 million in 2018, reached USD 70,054.82 million in 2024, and is projected to hit USD 86,600.45 million by 2032, growing at a CAGR of 2.69%.
- South Africa leads with around 35% share due to advanced infrastructure and established pharmacy chains, followed by Egypt at 25% driven by strong pharmaceutical manufacturing, and Nigeria at 20% supported by its large population and rising healthcare needs.
- The Rest of Africa, holding 20% share, is the fastest-growing region, driven by expanding e-pharmacy adoption, rising healthcare investments, and growing middle-class populations in markets like Kenya and Ghana.
- Externally threaded products dominate with about 35% share in 2024, supported by widespread application across pharmacy channels.
- Aerospace-grade products, though holding 20% share, show steady growth potential with rising demand for advanced pharmaceutical-grade solutions.
Market Drivers:
Rising Healthcare Needs and Expanding Chronic Disease Burden:
The Africa Retail Pharmacy Market benefits from growing healthcare demands and an increasing chronic disease burden. Rising cases of diabetes, hypertension, and cardiovascular conditions drive higher prescription and non-prescription drug sales. Urbanization is changing lifestyles, creating a steady need for pharmaceutical support. Expanding middle-class populations are seeking better healthcare access, fueling retail pharmacy visits. The aging population also demands continuous medication access, reinforcing pharmacy relevance. Pharmacies act as critical points for regular drug supply in urban and semi-urban regions. This consistent demand anchors retail pharmacies as integral parts of Africa’s healthcare delivery system. It creates opportunities for both local and multinational players to expand reach.
- For instance, Clicks Group in South Africa reported an 8.9% increase in pharmacy sales in 2024, supported by 11.8 million loyal ClubCard members and a repeat prescription service participation rising to 53%, reflecting the increasing demand for chronic disease medicines.
Government Policies Supporting Accessibility and Healthcare Expansion:
Government initiatives and supportive healthcare regulations are key drivers shaping the Africa Retail Pharmacy Market. National programs encourage medicine affordability and availability in urban and rural locations. Public-private partnerships are promoting stronger pharmacy networks across key African economies. Many governments are investing in health insurance schemes that boost consumer access to pharmacies. Enhanced regulatory frameworks are reducing counterfeit drugs, which strengthens trust in retail pharmacies. Infrastructure development across emerging regions is also helping distribution channels operate efficiently. Rural access programs ensure pharmacies expand beyond urban clusters. It gives pharmacies a central role in improving drug accessibility across the continent.
- For instance, Dis-Chem Pharmacies in South Africa have invested significantly in their distribution center capacity, optimizing supply chain efficiency to service expanded retail footprints and onboard new independent pharmacy customers, aiming to increase national presence beyond urban centers in trading space over three years.
Technological Integration Enhancing Customer Convenience and Efficiency:
The Africa Retail Pharmacy Market is moving toward digital integration, which accelerates accessibility and efficiency. E-pharmacy platforms are gaining popularity, offering doorstep delivery and virtual consultation. Pharmacies are adopting point-of-sale software to streamline inventory management and reduce errors. Mobile applications are increasing consumer engagement with features like refill reminders and promotions. Digital payment solutions encourage more purchases, especially in urban regions with rising smartphone penetration. Technology also helps pharmacies analyze consumer behavior and personalize offerings. Automated dispensing systems are emerging in larger retail chains to improve speed and accuracy. It strengthens consumer trust by offering consistent quality service and reliable product availability.
Expanding Consumer Awareness and Demand for Preventive Healthcare:
Increasing awareness of preventive healthcare and wellness is boosting demand in the Africa Retail Pharmacy Market. Consumers are seeking vitamins, supplements, and over-the-counter products to support healthier lifestyles. Pharmacies have become important touchpoints for preventive care advice, especially in urban centers. Lifestyle diseases encourage people to adopt regular wellness checks and nutritional support. Awareness campaigns by governments and private firms reinforce the importance of proactive healthcare. Pharmacies stock a wide range of products that support immunity and long-term health. Consumers now prefer pharmacies that combine drug supply with wellness services. It is driving pharmacies to diversify into preventive care segments to meet rising expectations.
Market Trends:
Emergence of Chain Pharmacies and Consolidation of Retail Outlets:
The Africa Retail Pharmacy Market is witnessing strong growth in chain pharmacies and retail consolidation. Large pharmacy groups are expanding networks, offering standardized services across multiple locations. Consolidation is improving supply chain efficiencies, reducing product shortages, and ensuring uniform pricing. Customers prefer branded chains due to reliability and consistent service quality. Independent pharmacies are partnering with larger groups to survive competitive pressures. Chain expansion is especially visible in South Africa, Nigeria, and Egypt. Consolidation is helping pharmacies achieve economies of scale and negotiate better supplier contracts. It is setting new benchmarks in professional pharmacy management and customer satisfaction across Africa.
- For instance, Goodlife Pharmacy increased its store presence from 19 to 150 stores under LeapFrog stewardship, reaching 2 million consumers annually across East Africa by 2025, exemplifying rapid network expansion and operational consolidation in the region.
Integration of Telemedicine and Pharmacy Services:
The Africa Retail Pharmacy Market is evolving with the integration of telemedicine services into pharmacy networks. Pharmacies are now offering virtual consultations alongside dispensing medicines. This integration supports rural communities with limited access to healthcare professionals. Telemedicine creates new revenue streams while strengthening pharmacy relevance in digital healthcare ecosystems. Pharmacies collaborate with doctors and diagnostic labs to deliver end-to-end patient support. Consumers benefit from convenience, affordability, and comprehensive care solutions under one roof. This trend aligns with rising smartphone adoption and digital healthcare platforms. It reflects the growing importance of pharmacies in bridging gaps between patients and healthcare providers.
- For instance, mPharma partnered with TytoCare to implement telehealth services across 35 pharmacies in Ghana, Kenya, Uganda, Zambia, and Nigeria, facilitating over 8,000 remote physical examinations since June 2021, enabling rapid virtual consultations often within 10 minutes.
Expansion of Specialty Pharmacies and Niche Healthcare Products:
The Africa Retail Pharmacy Market is witnessing rising demand for specialty pharmacies catering to complex conditions. Specialty outlets focus on oncology, rare diseases, and advanced treatments requiring specific storage. Pharmacies offering such products gain competitive advantages and consumer trust. Growth in biotechnology and specialty drug pipelines is fueling the demand for specialized services. Patients prefer pharmacies with expertise in handling complex prescriptions and counseling. Niche product categories such as dermatology and pediatric care are also expanding. These pharmacies differentiate themselves by offering value-added services beyond basic drug dispensing. It is positioning them as essential partners in delivering advanced and personalized care.
Growing Focus on Health and Wellness Retail Segments:
The Africa Retail Pharmacy Market is broadening into health and wellness segments. Pharmacies are increasingly stocking organic supplements, nutraceuticals, and personal care products. Consumers prefer pharmacies for wellness purchases due to trust and expert guidance. Urban customers are driving demand for fitness-related nutrition, skincare, and preventive health items. Retail outlets are redesigning store layouts to highlight wellness product categories. Pharmacies use loyalty programs to encourage regular purchases across wellness lines. Partnerships with global health and nutrition brands are expanding product ranges. It strengthens the role of pharmacies as holistic healthcare providers beyond traditional medicine dispensing.
Market Challenges Analysis:
Regulatory Variability and Prevalence of Counterfeit Drugs:
The Africa Retail Pharmacy Market faces significant challenges due to diverse regulatory systems across countries. Inconsistent regulations complicate cross-border operations and hinder uniform growth. Counterfeit drugs remain a persistent issue, undermining trust in retail pharmacies. Weak enforcement mechanisms allow unauthorized outlets to flourish, limiting quality assurance. High regulatory compliance costs also burden smaller pharmacies and restrict their expansion. Fragmented policies slow down standardization efforts and affect industry reputation. Consumers often face risks of substandard products due to poor monitoring. It creates a pressing need for stricter governance to safeguard patient safety and industry credibility.
Infrastructure Gaps and Limited Access in Rural Areas:
The Africa Retail Pharmacy Market struggles with infrastructure gaps that restrict its rural penetration. Many remote communities lack access to reliable retail pharmacies. Poor transport and logistics infrastructure delay medicine distribution to underserved areas. Power shortages affect storage of temperature-sensitive products in many regions. Pharmacies face high operating costs when expanding into less-developed markets. Skilled workforce shortages in pharmacy practice further weaken rural service delivery. Urban markets continue to dominate due to better infrastructure and customer density. It reinforces the urban-rural divide and limits equitable access to healthcare across Africa.
Market Opportunities:
Expansion of E-Pharmacy Platforms and Digital Healthcare Integration:
The Africa Retail Pharmacy Market presents strong opportunities through the expansion of e-pharmacy platforms. Growing internet penetration and smartphone use are fueling adoption of digital channels. Consumers increasingly seek doorstep delivery and online consultation for convenience. E-pharmacies can reach rural populations where physical outlets remain scarce. Partnerships with telecom operators and digital payment providers strengthen scalability. It creates a pathway for pharmacies to build hybrid models combining online and offline operations. The rising trend of digital healthcare ensures steady opportunities for innovation.
Rising Demand for Preventive Healthcare and Wellness Products:
The Africa Retail Pharmacy Market shows promising opportunities in preventive healthcare and wellness expansion. Increasing consumer preference for immunity boosters, supplements, and lifestyle products fuels growth. Pharmacies can leverage this demand by diversifying product portfolios into holistic wellness. Collaborations with global nutraceutical and healthcare brands can widen offerings. Health-conscious consumers encourage pharmacies to integrate fitness and nutrition categories. Wellness-focused loyalty programs attract repeat customers and strengthen brand value. It positions retail pharmacies as trusted destinations for comprehensive healthcare and lifestyle solutions.
Market Segmentation Analysis:
By Type of Pharmacy
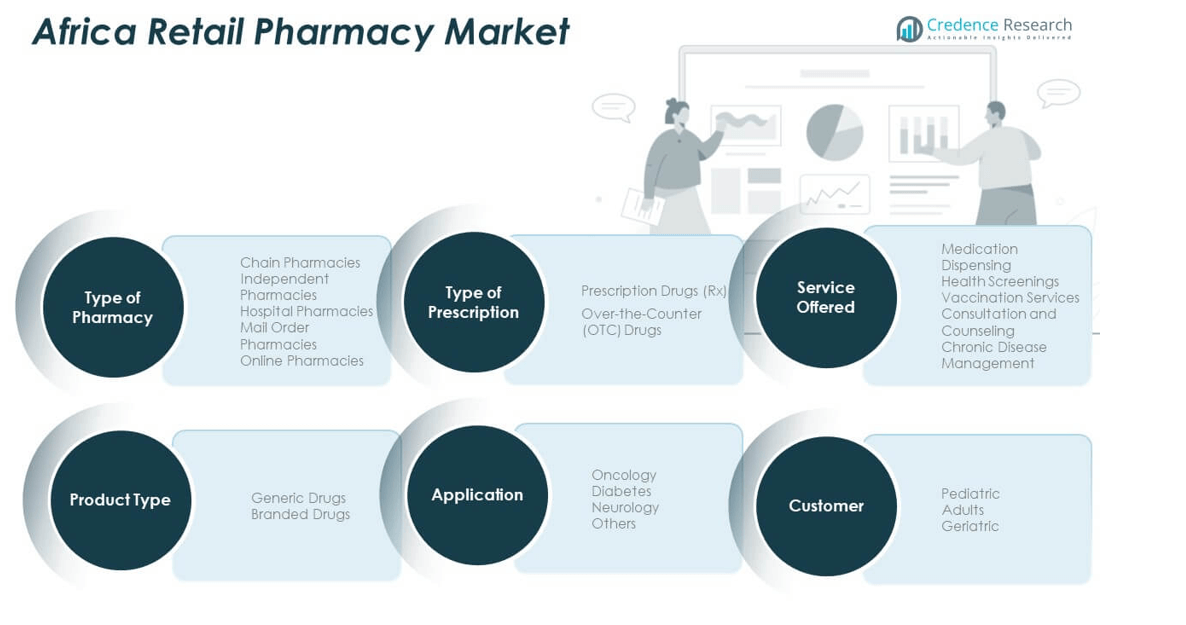
The Africa Retail Pharmacy Market includes chain pharmacies, independent outlets, hospital pharmacies, mail order services, and online platforms. Chain pharmacies dominate urban markets due to standardized service and broad product ranges, while independent outlets retain relevance in rural and semi-urban areas. Online pharmacies are emerging as high-growth channels driven by digital adoption.
- For instance, Dis-Chem's e-commerce operations currently contribute revenue and are expanding through online prescription services and on-demand delivery, integrating physical store presence with digital channels to enhance accessibility and convenience.
By Product Type
Generic drugs hold a substantial share due to affordability and government initiatives supporting access. Branded drugs maintain strong demand in urban centers where consumers seek quality assurance and established brand trust.
By Type of Prescription
Prescription drugs (Rx) represent the majority share, reflecting the growing burden of chronic conditions. Over-the-counter (OTC) drugs expand steadily with rising self-medication trends and consumer awareness of preventive health.
By Application
Oncology and diabetes lead the application segment due to increasing prevalence of lifestyle-related and critical illnesses. Neurology shows steady demand, while the "others" category covers diverse therapeutic needs across regions.
By Services Offered
Medication dispensing remains the primary service, supported by rising demand for vaccination and chronic disease management. Pharmacies increasingly provide health screenings, consultations, and counseling to expand their role in healthcare delivery.
By Customer Segment
Adults form the largest consumer base, followed by a growing geriatric segment requiring long-term medication. Pediatric demand continues in vaccines and child-specific therapies, supporting steady sales across age groups.
Segmentation:
By Type of Pharmacy
- Chain Pharmacies
- Independent Pharmacies
- Hospital Pharmacies
- Mail Order Pharmacies
- Online Pharmacies
By Product Type
- Generic Drugs
- Branded Drugs
By Type of Prescription
- Prescription Drugs (Rx)
- Over-the-Counter (OTC) Drugs
By Application
- Oncology
- Diabetes
- Neurology
- Others
By Services Offered
- Medication Dispensing
- Health Screenings
- Vaccination Services
- Consultation and Counselling
- Chronic Disease Management
By Customer Segment
- Pediatric
- Adults
- Geriatric
By Country
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
South Africa: Market Leader with Strong Infrastructure
South Africa holds the largest share of the Africa Retail Pharmacy Market, accounting for nearly 35% of total revenue. Its advanced healthcare infrastructure and wide network of chain pharmacies, including Clicks Group and Dis-Chem Pharmacies, strengthen market dominance. High urbanization rates and strong consumer purchasing power support steady demand for both prescription and OTC drugs. The country benefits from favorable insurance coverage and a mature retail distribution model. Online pharmacies are also expanding, supported by high internet penetration. It remains the most developed market in Africa, offering consistent growth and innovation opportunities.
Egypt and Nigeria: Expanding High-Growth Hubs
Egypt contributes around 25% of the Africa Retail Pharmacy Market share, driven by a robust pharmaceutical manufacturing base and government-backed health reforms. Nigeria holds nearly 20%, supported by rapid population growth and increasing healthcare needs. Pharmacies in Egypt focus on branded drugs and hospital-linked services, while Nigeria’s independent outlets dominate due to uneven urban-rural distribution. Both regions are seeing rising investments in chain pharmacies and e-pharmacy models. It reflects strong potential for expansion across urban centers and semi-urban regions.
Rest of Africa: Emerging Frontier with Untapped Potential
The Rest of Africa accounts for about 20% of the Africa Retail Pharmacy Market and represents the fastest-growing region. Kenya and Ghana are key contributors, benefiting from rising middle-class populations and growing healthcare awareness. Limited infrastructure challenges remain, but digital platforms are helping bridge accessibility gaps. Independent pharmacies dominate, though regional players are expanding their presence in urban clusters. Governments in East and West Africa are encouraging local manufacturing and pharmacy regulation to improve trust and availability. It positions the region as an attractive frontier for long-term growth and investment.
Key Player Analysis:
- Clicks Group (Clicks Pharmacy)
- Dis-Chem Pharmacies
- mPharma
- Medplus
- Kahira Pharmaceuticals
- Goodlife Pharmacy
- Haltons Pharmacy
Competitive Analysis:
The Africa Retail Pharmacy Market is competitive, with strong participation from regional chains, independent outlets, and online platforms. Large players such as Clicks Group and Dis-Chem Pharmacies dominate in South Africa with extensive networks and standardized services. Companies like mPharma and Goodlife Pharmacy are expanding across multiple African countries through strategic partnerships and digital solutions. Independent pharmacies maintain relevance in rural and semi-urban regions, although they face pressure from expanding chains and online services. The market shows increasing competition driven by consumer demand for affordability, accessibility, and wellness-focused products. It continues to evolve as players strengthen supply chains, expand product portfolios, and leverage technology to enhance customer engagement.
Recent Developments:
- In May 2026, Adalvo and Cipla expanded their strategic partnership with the launch of Vyfocis® capsules in South Africa, adding a new branded pharmaceutical product to the South African pharmacy channel.
- In April 2026, Clicks Group reported that it had reached a major retail-pharmacy milestone by opening its 1,000th store and expanding its national pharmacy network to 795 pharmacies by the end of February 2026.
- In April 2026, UPD, Clicks Group’s pharmaceutical wholesaler, expanded its pharma-compliant electric delivery fleet to 85 vehicles, supporting medicine distribution to the retail pharmacy network with lower fuel-cost exposure.
- In March 2026, Strides Pharma Science announced that its subsidiary had entered definitive agreements with Sandoz to acquire and in-license a portfolio of branded generic products across Sub-Saharan Africa, a move the company said would strengthen visibility in retail pharmacy and broaden its hospital-network offering.
- In December 2025, SPAR Group’s annual reporting showed that the Aptekor acquisition had been integrated into SPAR Health’s operations, supporting Pharmacy at SPAR’s pharmaceutical wholesaling and independent-pharmacy support model in South Africa.
Report Coverage:
The research report offers an in-depth analysis based on type of pharmacy, product type, prescription type, application, services offered, and customer segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of chain pharmacies will accelerate consolidation across urban markets.
- Online pharmacies will gain traction with growing smartphone use and digital adoption.
- Preventive healthcare and wellness products will expand their share in pharmacy sales.
- Regulatory reforms will strengthen trust in pharmacy networks across the region.
- Chronic disease management services will drive long-term customer loyalty.
- Regional players will expand through partnerships and acquisitions.
- Independent pharmacies will remain strong in underserved rural regions.
- Telemedicine integration will make pharmacies central to holistic healthcare.
- Local manufacturing of generic drugs will improve affordability and access.
- Consumer loyalty programs will support recurring purchases and higher engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Healthcare Needs and Chronic Disease Burden
Increasing prevalence of chronic diseases such as diabetes, hypertension, and cardiovascular conditions is driving demand for both prescription and non-prescription medicines, making retail pharmacies essential points of care across Africa.
Government Policies Supporting Accessibility
National health initiatives, expanded insurance coverage, and public-private partnerships are improving medicine affordability and distribution, enabling pharmacies to reach more urban and rural populations and boosting overall market growth.
Technological Integration and E-Pharmacy Expansion
Digital transformation, including the rise of e-pharmacy platforms, mobile applications, and automated dispensing systems, is enhancing consumer convenience, expanding access to medicines, and streamlining pharmacy operations.
Expanding Consumer Awareness and Preventive Healthcare Demand
Growing awareness of preventive health and wellness is increasing demand for vitamins, supplements, and over-the-counter products, prompting pharmacies to diversify offerings and become holistic healthcare providers.
Urbanization and Rising Disposable Incomes
Rapid urbanization and a growing middle class are increasing the number of consumers seeking pharmacy-based healthcare solutions, supporting the expansion of chain pharmacies and modern retail channels.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Africa Retail Pharmacy Market in 2023, 2032, and the CAGR?
At what Compound Annual Growth Rate is the Africa Retail Pharmacy Market projected to grow between 2024 and 2032?
What are the key drivers of the Africa Retail Pharmacy Market?
How are retail pharmacies addressing the demand for healthcare in rural areas?
What role does digital transformation play in the Africa Retail Pharmacy Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Oncology
- 1.2.2 Diabetes
- 1.2.3 Neurology
- 1.2.4 Others
- 1.3 By Product Type
- 1.3.1 Generic Drugs
- 1.3.2 Branded Drugs
- 1.4 By Services Offered
- 1.4.1 Medication Dispensing
- 1.4.2 Health Screenings
- 1.4.3 Vaccination Services
- 1.4.4 Consultation and Counselling
- 1.4.5 Chronic Disease Management
- 1.5 By Type of Pharmacy
- 1.5.1 Chain Pharmacies
- 1.5.2 Independent Pharmacies
- 1.5.3 Hospital Pharmacies
- 1.5.4 Mail Order Pharmacies
- 1.5.5 Online Pharmacies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 70,054.82 million → 2032: USD 86,600.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Africa Retail Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Africa Retail Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Africa Retail Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Africa Retail Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Africa Retail Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Africa Retail Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Africa Retail Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Africa Retail Pharmacy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 70,054.82 million → 2032: USD 86,600.45 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Africa Retail Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oncology
- 12.3.7.2 Diabetes
- 12.3.7.3 Neurology
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Generic Drugs
- 12.4.7.2 Branded Drugs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Services Offered - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Medication Dispensing
- 12.5.7.2 Health Screenings
- 12.5.7.3 Vaccination Services
- 12.5.7.4 Consultation and Counselling
- 12.5.7.5 Chronic Disease Management
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Pharmacy - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Chain Pharmacies
- 12.6.7.2 Independent Pharmacies
- 12.6.7.3 Hospital Pharmacies
- 12.6.7.4 Mail Order Pharmacies
- 12.6.7.5 Online Pharmacies
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Africa Retail Pharmacy End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Africa Retail Pharmacy Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Africa Retail Pharmacy Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Africa Retail Pharmacy Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Clicks Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dis-Chem Pharmacies
- 18.4 mPharma
- 18.5 Medplus
- 18.6 Kahira Pharmaceuticals
- 18.7 Goodlife Pharmacy
- 18.8 Haltons Pharmacy
- 18.9 SPAR Group
- 18.10 Strides Pharma Science
- 18.11 Adcock Ingram
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

