
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Antibody Drug Conjugates (ADC) Market Size 2024 | USD 14,115 million |
| Antibody Drug Conjugates (ADC) Market, CAGR | 9% |
| Antibody Drug Conjugates (ADC) Market Size 2032 | USD 28,125 million |
Market Overview
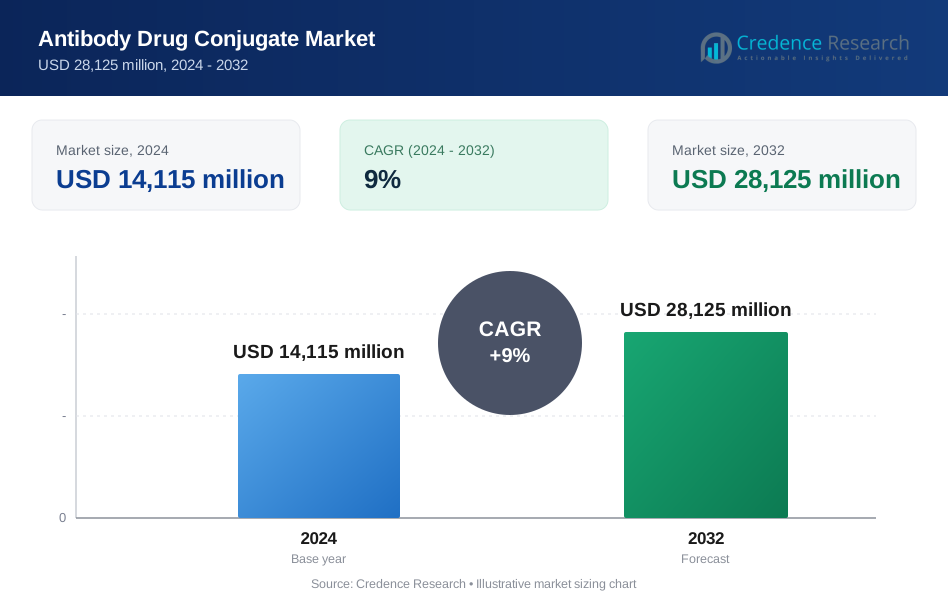
The Antibody Drug Conjugates (ADC) Market is projected to grow from USD 14,115 million in 2024 to USD 28,125 million by 2032, registering a compound annual growth rate (CAGR) of 9%.
The Antibody Drug Conjugates (ADC) Market is driven by the increasing prevalence of cancer and the growing demand for targeted therapies that offer high efficacy with fewer side effects compared to conventional treatments. Advances in ADC technology, such as improved linker technologies and more potent cytotoxic drugs, are enhancing their therapeutic potential, fueling market growth. Additionally, the rising adoption of personalized medicine and the focus on developing next-generation ADCs for various cancer types are key trends supporting market expansion. Pharmaceutical companies are increasingly investing in ADC development, with several entering strategic partnerships to advance research and commercialization. Furthermore, favorable regulatory support, including accelerated approval processes, is expediting the availability of new ADC therapies in the market. As the pipeline for ADCs continues to expand, the integration of innovative technologies and collaborations is expected to further enhance the market's growth trajectory, making ADCs a central component in the fight against cancer.
The Antibody Drug Conjugates (ADC) Market is witnessing significant growth across various regions. North America leads the market with a 45% share, driven by advanced healthcare infrastructure and a strong presence of key players such as Seagen, Inc. and Pfizer. Europe follows with a 30% share, supported by increasing cancer prevalence and strong healthcare systems in countries like Germany and the UK. The Asia Pacific region holds 15% of the market, with growing investments in healthcare and rising cancer awareness, particularly in Japan, China, and India. Key players such as AstraZeneca, Takeda Pharmaceutical Company Ltd., and Daiichi Sankyo are prominent in these regions, driving innovation and expanding market access. Strategic collaborations and regulatory support across these regions will continue to shape the market’s competitive landscape.
Market Insights
- The Antibody Drug Conjugates (ADC) Market is projected to grow from USD 14,115 million in 2024 to USD 28,125 million by 2032, with a compound annual growth rate (CAGR) of 9%.
- The increasing prevalence of cancer and the demand for targeted therapies with fewer side effects compared to conventional treatments are key drivers of market growth.
- Advancements in ADC technology, such as improved linker technologies and more potent cytotoxic drugs, are enhancing their therapeutic potential and boosting market demand.
- The rising adoption of personalized medicine and the development of next-generation ADCs for various cancer types are critical trends supporting market expansion.
- Strategic collaborations between pharmaceutical companies and biotech firms are accelerating ADC development and market commercialization, helping meet growing demand.
- North America leads the ADC market with a 45% market share, driven by advanced healthcare infrastructure, high healthcare expenditure, and strong market players.
- High production costs and limited efficacy in certain cancer types present challenges, requiring further innovation in manufacturing and clinical application to overcome these barriers
Market Drivers
Rising Cancer Prevalence
The increasing incidence of cancer globally is a significant driver for the Antibody Drug Conjugates (ADC) Market. With cancer cases on the rise, there is a pressing need for more targeted and effective therapies that can specifically attack cancer cells while minimizing damage to healthy tissue. ADCs offer a promising solution by delivering potent drugs directly to tumor cells, ensuring higher precision in treatment. This growing need for effective cancer therapies boosts ADC adoption.
- For instance, Seagen’s Adcetris (brentuximab vedotin) has become a standard therapy for certain types of lymphoma, with clinical studies showing significant improvements in overall response rates and progression-free survival when combined with chemotherapy.
Technological Advancements in ADC Development
Advancements in ADC technology play a crucial role in the market's growth. Enhanced linker technologies and more potent cytotoxic agents have improved ADC performance, allowing for greater precision and efficacy. These innovations enable ADCs to better target and destroy cancer cells, which directly contributes to their increasing demand. The continuous development of more sophisticated ADC formulations enhances their therapeutic potential, supporting market expansion.
- For instance, Gilead Sciences’ Trodelvy (sacituzumab govitecan) uses a CL2A acid-cleavable linker with PEG chains, a novel design that improves stability and targeted drug release, contributing to its FDA approval for metastatic triple-negative breast cancer.
Strategic Collaborations and Partnerships
The Antibody Drug Conjugates Market is benefiting from an increase in strategic collaborations between pharmaceutical companies and biotech firms. These partnerships focus on accelerating ADC development and bringing novel therapies to market faster. Collaborative efforts help share resources, reduce risks, and leverage expertise in advanced drug development. As these partnerships continue, they will drive more rapid innovation and increase the availability of new ADC therapies to meet growing market demand.
Supportive Regulatory Environment
Regulatory agencies are increasingly providing support for the Antibody Drug Conjugates Market. Accelerated approval processes and fast-track pathways help bring ADC therapies to market more quickly, which is crucial in addressing urgent cancer treatment needs. These regulatory incentives facilitate the approval of novel therapies, allowing ADCs to enter the market faster. The growing number of ADCs approved for use in various cancer indications further supports the expansion of the market.
Market Trends
Shift Towards Personalized Medicine
One prominent trend in the Antibody Drug Conjugates (ADC) Market is the shift towards personalized medicine. With the rise of precision therapies, ADCs are being tailored to individual patient profiles based on genetic and molecular factors. This approach enhances treatment efficacy and minimizes adverse effects, driving the demand for customized ADC therapies. Healthcare providers increasingly focus on delivering personalized treatment options, particularly in oncology, where precision is crucial for improved patient outcomes.
- For instance, tisotumab vedotin-tftv (Tivdak, Pfizer/Genmab) targets tissue factor in cervical cancer, demonstrating the use of ADCs tailored to tumor-specific antigens to improve efficacy and minimize off-target effects.
Growing Focus on Combination Therapies
Combination therapies involving ADCs are gaining significant attention in the market. Researchers are exploring how ADCs can be combined with other therapeutic agents, such as immune checkpoint inhibitors or targeted therapies, to enhance treatment outcomes. These combined approaches aim to improve the overall effectiveness of cancer treatments, reduce resistance, and achieve better results in complex cancer types. This trend has driven innovation, leading to new ADC combination therapies entering clinical trials.
- For instance, Brentuximab vedotin, an ADC, combined with AVD chemotherapy (doxorubicin, vinblastine, dacarbazine) was approved in 2018 for previously untreated Hodgkin lymphoma. The Phase III trial showed a progression-free survival of 82.1% for the combination, compared to 78.8% with the standard ABVD regimen.
Rising Investment in ADC Research and Development
The Antibody Drug Conjugates Market is experiencing increased investment in research and development. Both large pharmaceutical companies and smaller biotech firms are dedicating more resources to discovering and developing next-generation ADCs. This investment focuses on optimizing ADC design, improving targeting capabilities, and expanding their use in multiple therapeutic areas. The continuous R&D in ADC technologies contributes to the accelerated pace of innovation, driving the market's expansion as novel therapies emerge.
Regulatory Push for Accelerated Approvals
Regulatory bodies are increasingly offering accelerated approval pathways for ADCs, further propelling market growth. These fast-track programs, including Breakthrough Therapy Designation and Priority Review, reduce time-to-market for innovative ADC therapies. Regulatory agencies, such as the FDA, recognize the potential of ADCs in treating life-threatening conditions, particularly cancer, and are streamlining approval processes. This trend supports the timely availability of new ADC treatments, enabling healthcare systems to respond rapidly to emerging treatment needs.
Market Challenges Analysis
High Production Costs and Complex Manufacturing
One of the primary challenges facing the Antibody Drug Conjugates (ADC) Market is the high production costs associated with manufacturing these therapies. The complexity of ADC development requires specialized raw materials, highly skilled labor, and advanced technologies, driving up production expenses. The need for precise formulation and the synthesis of cytotoxic drugs adds layers of complexity to the manufacturing process. These high costs may limit accessibility for smaller biotech firms and hinder widespread adoption. Overcoming these manufacturing hurdles is critical for scaling ADC production while maintaining cost-efficiency.
- For instance, Daiichi Sankyo’s ENHERTU (trastuzumab deruxtecan), a leading ADC, requires advanced modular manufacturing platforms to handle its complex structure, which includes a monoclonal antibody, a cleavable linker, and a potent topoisomerase inhibitor payload.
Limited Efficacy in Certain Cancer Types
While ADCs offer promising results, their efficacy may be limited in certain cancer types, posing a challenge to the growth of the Antibody Drug Conjugates Market. Tumors can develop resistance mechanisms that reduce ADC effectiveness, making treatment less effective in specific patient populations. The heterogeneity of cancer cells also presents difficulties in targeting them precisely with ADCs. Research and development efforts are focused on overcoming these limitations, but achieving consistent results across all cancer types remains a significant challenge. Addressing this issue is vital for maximizing the therapeutic potential of ADCs.
Market Opportunities
Expansion into New Therapeutic Areas
The Antibody Drug Conjugates (ADC) Market presents significant opportunities for growth as it expands into new therapeutic areas beyond oncology. While ADCs are currently most prevalent in cancer treatment, ongoing research explores their potential for treating autoimmune disorders, cardiovascular diseases, and infectious diseases. These areas hold promise due to the ability of ADCs to provide highly targeted therapies. The expansion into these therapeutic areas could drive market growth by offering novel treatment options for a broader range of patients, addressing unmet medical needs.
Advances in Personalized Cancer Therapy
Advancements in personalized medicine create substantial opportunities for the ADC market, particularly in cancer treatment. The ability to tailor ADC therapies based on genetic and molecular profiling of patients enhances treatment efficacy and minimizes side effects. This trend aligns with the growing demand for individualized therapies, opening doors for ADCs to be used in more specific cancer subtypes. As personalized cancer treatments become more prevalent, the market for ADCs will likely see continued expansion, providing more tailored and effective therapeutic options for patient
Market Segmentation Analysis:
By Product
The Antibody Drug Conjugates (ADC) Market is segmented by product, with leading ADC therapies such as Kadcyla, Enhertu, Adcetris, Padcev, Trodelvy, and Polivy. These products represent a significant portion of the market, with Kadcyla and Enhertu being prominent in breast cancer treatment. Adcetris and Padcev are highly effective in treating blood cancers, while Trodelvy has shown promise in treating triple-negative breast cancer. These therapies are crucial in expanding the therapeutic scope of ADCs, and continued innovation in this segment will likely drive market growth.
- For instance, Adcetris (brentuximab vedotin, from Seagen and Takeda) has become a standard of care for relapsed or refractory Hodgkin lymphoma, offering improved outcomes for patients with limited treatment options (based on documented clinical guidelines and product approvals).
By Disease Type
By disease type, the Antibody Drug Conjugates Market is primarily segmented into breast cancer, blood cancer, and others. Breast cancer dominates the market due to the high prevalence of the disease and the success of ADCs like Kadcyla and Enhertu in treating it. Blood cancers, such as lymphoma and leukemia, also account for a substantial market share, with therapies like Adcetris and Polivy proving effective. The "others" segment includes ADCs used in treating various cancer types, creating opportunities for ADCs to address a broader range of diseases in the future.
- For instance, Enhertu also received FDA approval in January 2021 for treating advanced gastric cancer after trastuzumab-based therapy, based on the DESTINY-Gastric01 Phase II trial, which showed a four-month overall survival benefit over standard chemotherapy.
By Linker Type
The market is further segmented by linker type, including non-cleavable and cleavable linkers. Cleavable linkers are designed to release the cytotoxic drug inside the target cell, offering greater precision in cancer treatment. Non-cleavable linkers, on the other hand, allow for more stable delivery of the drug to the target site. Both types of linkers play a crucial role in the performance and effectiveness of ADCs, influencing their therapeutic applications in various cancer treatments within the ADC market.
Segments:
Based on Product
- Kadcyla
- Enhertu
- Adcetris
- Padcev
- Trodelvy
- Polivy
- Others
Based on Disease Type
- Breast Cancer
- Blood Cancer
- Others
Based on Linker Type
- Non-Cleavable
- Cleavable
Based on Target
- HER2
- CD22
- CD30
- Others
Based on Payload Type
- MMAE/auristatin
- calicheamicin
- Maytansinoids
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the Antibody Drug Conjugates (ADC) Market, accounting for 45% of the total market share. The region benefits from advanced healthcare infrastructure, high healthcare expenditure, and a strong presence of key players in the ADC industry. The increasing prevalence of cancer and the rising demand for targeted therapies significantly contribute to the market's growth in North America. Regulatory support, particularly from the FDA, accelerates the approval of innovative ADC therapies. These factors combine to make North America a dominant region in the global ADC market.
Europe
Europe holds a market share of 30% in the Antibody Drug Conjugates Market, driven by a high cancer incidence and an increasing focus on precision medicine. The region benefits from well-established healthcare systems and a strong emphasis on innovation in cancer treatment. Countries like Germany, the UK, and France are leading the market, with increasing adoption of ADCs in clinical settings. Regulatory pathways in Europe, including fast-track approvals for promising cancer therapies, support the growth of the market in this region.
Asia Pacific
The Asia Pacific region accounts for 15% of the Antibody Drug Conjugates Market. The rising healthcare investments and improvements in cancer treatment infrastructure are driving market growth. In countries such as Japan, China, and India, the increasing incidence of cancer combined with growing awareness about advanced therapies like ADCs contributes to market expansion. The Asia Pacific market also benefits from increasing collaborations between pharmaceutical companies and research institutions, which accelerates the development and accessibility of ADCs in this region.
Key Player Analysis
- Pfizer, Inc.
- AstraZeneca
- Seagen, Inc.
- Takeda Pharmaceutical Company Ltd.
- GlaxoSmithKline Plc
- Hoffmann-La Roche Ltd.
- Gilead Sciences, Inc.
- Daiichi Sankyo Company Ltd.
- Astellas Pharma, Inc.
- ADC Therapeutics SA
Competitive Analysis
The Antibody Drug Conjugates (ADC) Market is highly competitive, with several key players driving innovation and market growth. Companies such as Seagen, Inc., Pfizer, and AstraZeneca are leading the charge in developing advanced ADC therapies, focusing on precision medicine to enhance efficacy and reduce side effects. These firms leverage strong research and development capabilities, with extensive pipelines of ADC products targeting various cancer types. Other prominent players like F. Hoffmann-La Roche Ltd. and Takeda Pharmaceutical Company Ltd. are also making significant strides in the market, securing regulatory approvals for ADC therapies that address unmet medical needs. Emerging biotech firms, such as ADC Therapeutics SA, are further intensifying competition by focusing on specialized ADC technologies and niche applications. The competitive landscape is characterized by strategic partnerships, acquisitions, and collaborations aimed at accelerating the development of next-generation ADCs. As the market expands, the focus will be on innovation, market accessibility, and regulatory success.
Recent Developments
- In June 2023, Lonza acquired Synaffix B.V., a biotechnology company specializing in commercializing clinical-stage technology platforms for developing antibody-drug conjugates (ADCs).
- In July 2023, ImmunoGen, Inc. entered into a multi-target license and option agreement with ImmunoBiochem to develop next-generation ADCs.
- In July 2023, BeiGene and DualityBio formed a partnership aimed at advancing differentiated ADC therapy for treating solid tumors.
- In January 2024, Celltrion, Inc., and WuXi XDC signed a Memorandum of Understanding (MOU) for integrated services focused on ADCs, including their development and manufacturing.
- In January 2024, Johnson & Johnson Services, Inc. acquired Ambrx Biopharma, Inc., which possesses proprietary ADC technology for developing next-generation ADCs aimed at treating cancers. J&J plans to leverage this technology, particularly for its prostate cancer portfolio.
Market Concentration & Characteristics
The Antibody Drug Conjugates (ADC) Market is characterized by a moderate to high concentration, with several large pharmaceutical companies and biotech firms dominating the market. Industry leaders such as Seagen, Pfizer, and AstraZeneca hold substantial market shares, driving technological advancements and research into new ADC therapies. These players possess significant resources for research and development, enabling them to create and commercialize innovative products. The market also features smaller biotech firms like ADC Therapeutics SA, which focus on specialized ADC technologies and niche applications. A key characteristic of the ADC market is its reliance on regulatory approvals and strategic partnerships, which accelerate product development and market entry. Despite the concentration, the market remains dynamic, with continuous innovation and expanding competition. New entrants and ongoing collaborations are expected to increase market diversity while maintaining a competitive edge for major players in the ADC space.
Report Coverage
The research report offers an in-depth analysis based on Product, Disease Type, Linker Type, Target, Payload Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The ADC market is expected to experience significant growth, driven by the increasing incidence of cancer and the demand for targeted therapies.
- Advancements in linker technologies and payloads are enhancing the specificity and efficacy of ADCs, leading to improved treatment outcomes.
- Regulatory agencies are streamlining approval processes for ADCs, facilitating faster market entry for new therapies.
- Strategic collaborations between pharmaceutical companies and biotech firms are accelerating the development and commercialization of ADCs.
- The breast cancer segment is anticipated to dominate the ADC market, with several ADC therapies receiving approvals for this indication.
- Emerging markets, particularly in Asia Pacific, are showing increased adoption of ADC therapies due to rising cancer prevalence and healthcare infrastructure improvements.
- The development of next-generation ADCs targeting solid tumors is expanding the therapeutic applications of these therapies.
- Advancements in antibody engineering are leading to the creation of more potent and selective ADCs, enhancing their therapeutic potential.
- The integration of artificial intelligence and machine learning in ADC development is streamlining the discovery and optimization processes.
- Increased investment in ADC research and development is expected to drive innovation and bring new therapies to market, benefiting patients worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cancer Prevalence
The increasing global incidence of cancer is driving demand for more effective and targeted therapies, making ADCs a preferred option due to their ability to selectively deliver cytotoxic agents to tumor cells while sparing healthy tissue.
Technological Advancements in ADC Development
Innovations in linker technologies and more potent cytotoxic payloads are enhancing the efficacy and safety of ADCs, expanding their therapeutic potential and supporting broader adoption in oncology.
Strategic Collaborations and Partnerships
Pharmaceutical and biotech companies are increasingly forming partnerships to accelerate ADC research, development, and commercialization, pooling resources and expertise to bring new therapies to market faster.
Supportive Regulatory Environment
Favorable regulatory frameworks, including accelerated approval pathways and fast-track designations, are expediting the introduction of new ADC therapies, enabling quicker patient access to innovative treatments.
Shift Towards Personalized Medicine
The trend toward personalized and precision medicine is boosting the development of ADCs tailored to specific tumor markers and patient profiles, improving treatment outcomes and expanding the market for targeted cancer therapies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Antibody Drug Conjugates Market?
What are the key segments within the Antibody Drug Conjugates Market?
Which Linker Type is expected to post the highest CAGR during the forecast period?
Who are the major players in the global antibody drug conjugate Market?
What are the major market drivers of the Antibody Drug Conjugate industry?
What are the major market restraints of the Antibody Drug Conjugate industry?
What are the major market opportunities of the Antibody Drug Conjugate industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Target
- 1.2.1 HER2
- 1.2.2 CD22
- 1.2.3 CD30
- 1.2.4 Others
- 1.3 By Product
- 1.3.1 Kadcyla
- 1.3.2 Enhertu
- 1.3.3 Adcetris
- 1.3.4 Padcev
- 1.3.5 Trodelvy
- 1.3.6 Polivy
- 1.3.7 Others
- 1.4 By Linker Type
- 1.4.1 Non-Cleavable
- 1.4.2 Cleavable
- 1.5 By Disease Type
- 1.5.1 Breast Cancer
- 1.5.2 Blood Cancer
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,115 million → 2032: USD 28,125 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Antibody Drug Conjugate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Antibody Drug Conjugate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Antibody Drug Conjugate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Antibody Drug Conjugate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Antibody Drug Conjugate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Antibody Drug Conjugate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Antibody Drug Conjugate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Antibody Drug Conjugate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,115 million → 2032: USD 28,125 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Antibody Drug Conjugate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Target - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 HER2
- 12.3.7.2 CD22
- 12.3.7.3 CD30
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Kadcyla
- 12.4.7.2 Enhertu
- 12.4.7.3 Adcetris
- 12.4.7.4 Padcev
- 12.4.7.5 Trodelvy
- 12.4.7.6 Polivy
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Linker Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Non-Cleavable
- 12.5.7.2 Cleavable
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Disease Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Breast Cancer
- 12.6.7.2 Blood Cancer
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Antibody Drug Conjugate Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Antibody Drug Conjugate Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Antibody Drug Conjugate Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 AstraZeneca
- 17.4 Seagen, Inc.
- 17.5 Takeda Pharmaceutical Company Ltd.
- 17.6 GlaxoSmithKline Plc
- 17.7 Hoffmann-La Roche Ltd.
- 17.8 Gilead Sciences, Inc.
- 17.9 Daiichi Sankyo Company Ltd.
- 17.10 Astellas Pharma, Inc.
- 17.11 ADC Therapeutics SA
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

