
Market Overview
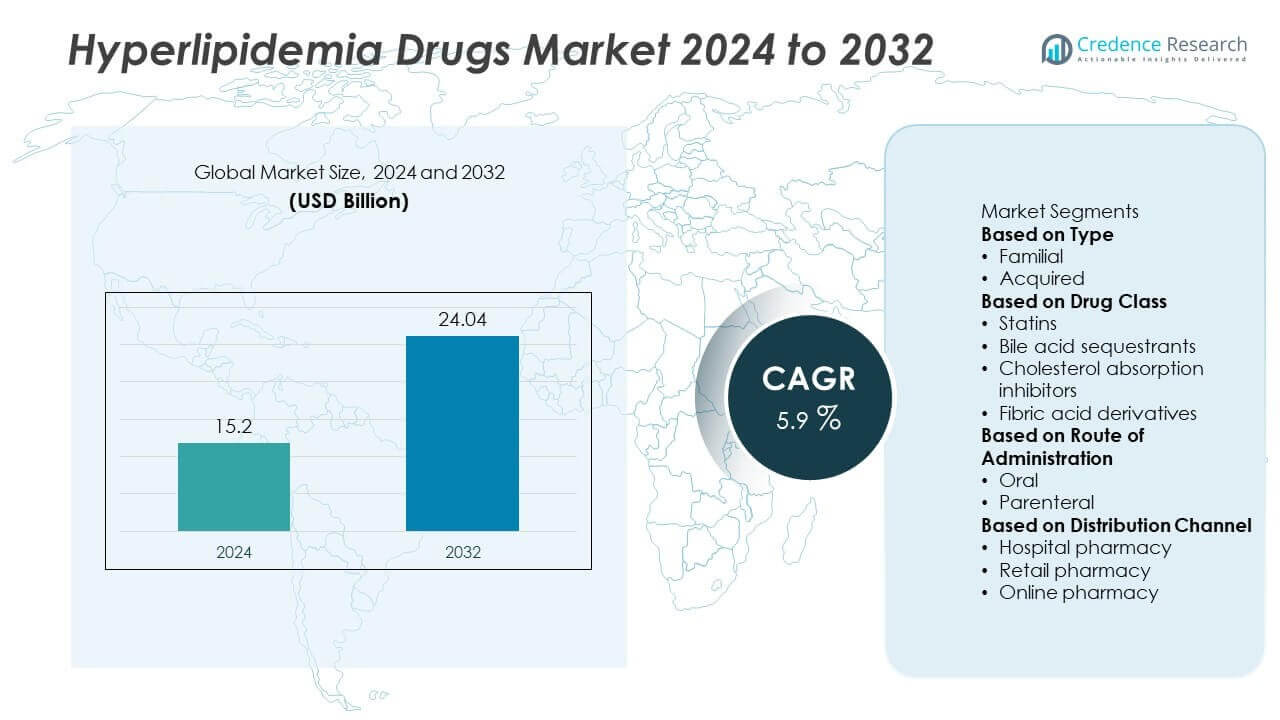
The Hyperlipidemia Drugs market was valued at USD 15.2 billion in 2024 and is projected to reach USD 24.04 billion by 2032, expanding at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hyper Automation Market Size 2024 | USD 15.2 Billion |
| Hyper Automation Market, CAGR | 5.9% |
| Hyper Automation Market Size 2032 | USD 24.04 Billion |
The Hyperlipidemia Drugs market is shaped by top players including Johnson & Johnson, F. Hoffmann-La Roche Ltd, Amgen Inc., Eli Lilly and Company, AstraZeneca PLC, Dr. Reddy’s Laboratories Limited, Merck & Co., Inc., Bristol-Myers Squibb Company, Alnylam Pharmaceuticals, Inc., and GSK plc. These companies lead through established statins, innovative PCSK9 inhibitors, and emerging RNA-based therapies. Regionally, North America dominated the market in 2024 with 41% share, supported by strong healthcare infrastructure and early access to biologics. Europe followed with 29%, driven by robust screening programs and treatment guidelines, while Asia-Pacific accounted for 21%, emerging as the fastest-growing region with rising cardiovascular disease prevalence and expanding healthcare access.
 Market Insights
- The Hyperlipidemia Drugs market was valued at USD 15.2 billion in 2024 and is projected to reach USD 24.04 billion by 2032, growing at a CAGR of 5.9% during 2024–2032.
- Rising prevalence of cardiovascular diseases and obesity drives demand, with acquired hyperlipidemia leading at 72% share in 2024, supported by growing awareness and screening programs.
- Statins remained the dominant drug class with 61% share, while PCSK9 inhibitors and RNA-based therapies are gaining traction as key trends in advanced treatment options.
- The market is highly competitive with players such as Johnson & Johnson, F. Hoffmann-La Roche Ltd, Amgen Inc., Eli Lilly and Company, AstraZeneca PLC, Dr. Reddy’s Laboratories Limited, Merck & Co., Inc., Bristol-Myers Squibb Company, Alnylam Pharmaceuticals, Inc., and GSK plc focusing on innovation, partnerships, and pipeline expansion.
- Regionally, North America led with 41% share, followed by Europe at 29% and Asia-Pacific at 21%, while Latin America and Middle East & Africa accounted for 6% and 3%, respectively.
Market Segmentation Analysis:
By Type
The acquired hyperlipidemia segment dominated the market in 2024, accounting for nearly 72% share. Its dominance is driven by lifestyle-related factors such as obesity, poor diet, and sedentary behavior, which contribute significantly to cholesterol abnormalities. The increasing global burden of diabetes and cardiovascular diseases further accelerates the demand for effective treatments. Familial hyperlipidemia, while a smaller segment, remains important due to genetic screening and early interventions. However, the large patient base with acquired conditions continues to sustain strong demand for drug therapies, keeping this segment in the lead.
- For instance, a review of the Dutch familial hypercholesterolemia (FH) cascade screening program found that, on average, approximately eight new FH cases were detected per index patient, although the exact number varies by study [2023, 2024]. A review of the Dutch program further showed that the percentage of treated FH patients increased significantly two years after genetic testing [2011, 2024].
By Drug Class
Statins emerged as the leading drug class, holding over 61% of the Hyperlipidemia Drugs market in 2024. Their dominance is supported by proven efficacy in lowering LDL cholesterol and reducing cardiovascular risks, making them the first-line therapy. The widespread use of generic statins further boosts accessibility and affordability. Other classes, including bile acid sequestrants, cholesterol absorption inhibitors, and fibric acid derivatives, address specific patient groups and combination therapies. However, the established clinical benefits, cost-effectiveness, and high prescription rates ensure statins maintain the largest market share.
- For instance, studies on familial hypercholesterolemia (FH) have shown that a genetic diagnosis can increase the uptake of and adherence to lipid-lowering therapies. A 2018 report found that confirmation of a genetic variant led to a significant effect on patients' plasma low-density lipoprotein cholesterol (LDL-C) levels.
By Route of Administration
Oral administration led the market in 2024, capturing nearly 85% share. Its dominance is attributed to the convenience of daily oral dosing and high patient adherence, particularly for statins and cholesterol absorption inhibitors. Oral drugs remain the preferred route due to ease of prescribing, low cost, and broad acceptance across patient populations. Parenteral options, including PCSK9 inhibitors, are gaining traction for patients unresponsive to oral therapies, but their high cost limits widespread use. Despite advancements in injectable therapies, oral formulations continue to dominate the hyperlipidemia treatment landscape.
Key Growth Drivers
Rising Prevalence of Cardiovascular Diseases
The growing global burden of cardiovascular diseases remains a primary driver for the hyperlipidemia drugs market. Unhealthy diets, obesity, smoking, and sedentary lifestyles significantly increase cholesterol-related disorders. According to health data, cardiovascular diseases continue to be the leading cause of death worldwide, accounting for millions of cases annually. This rising incidence fuels demand for effective cholesterol-lowering drugs, especially statins and novel biologics. As healthcare systems prioritize preventive care, the need for accessible and effective hyperlipidemia treatments continues to strengthen market growth across developed and emerging regions.
- For instance, global cardiovascular disease prevalence is projected to rise to 1.14 billion cases by 2050, with ischemic heart disease causing nearly 9 million deaths in 2021, underscoring the critical necessity for advanced cholesterol management therapies in medical protocols.
Increasing Awareness and Screening Programs
Expanding awareness campaigns and preventive healthcare initiatives have significantly improved early detection of hyperlipidemia. Governments and healthcare organizations actively promote cholesterol screening, encouraging patients to seek timely treatment. Early diagnosis not only increases drug prescriptions but also drives long-term adherence to therapies. Additionally, employer-led health checkups and insurance incentives for regular screening further boost treatment uptake. With more patients identified at early stages, the market sees consistent demand for both generic statins and advanced therapies, supporting sustainable growth in the hyperlipidemia drugs market.
- For instance, screening programs have been shown to increase the diagnosis rate of hyperlipidemia, facilitating earlier intervention that has been associated with significant, sustained reductions in LDL cholesterol levels over periods ranging from one to several years.
Advancements in Novel Therapeutics
The development of advanced drug classes, such as PCSK9 inhibitors and RNA-based therapies, creates new growth opportunities. These treatments demonstrate superior efficacy in patients resistant to traditional statins or with high genetic risk. Clinical trials highlight their ability to reduce LDL cholesterol to unprecedented levels, improving outcomes for high-risk populations. Pharmaceutical companies are heavily investing in research and partnerships to expand the pipeline of next-generation drugs. These innovations strengthen the market by addressing unmet medical needs and offering effective options beyond conventional therapies.
Key Trends & Opportunities
Rising Demand for Combination Therapies
A key trend in the hyperlipidemia drugs market is the increasing use of combination therapies. Physicians prescribe dual regimens of statins with cholesterol absorption inhibitors or bile acid sequestrants to maximize treatment effectiveness. This approach benefits patients with resistant hyperlipidemia, improving cholesterol management and reducing cardiovascular risks. Pharmaceutical companies are responding by developing fixed-dose combinations that improve compliance and outcomes. The growing adoption of multi-drug regimens creates strong opportunities for manufacturers to expand product portfolios and enhance treatment accessibility.
- For instance, in the IMPROVE-IT clinical trial, Merck's Vytorin (a combination of ezetimibe and simvastatin) lowered the median time-weighted average low-density lipoprotein (LDL) cholesterol to 1.4 mmol/L compared to 1.8 mmol/L for simvastatin monotherapy, representing an average difference of 0.4 mmol/L.
Expansion of Biologics and Specialty Drugs
The market is witnessing rising adoption of biologics such as PCSK9 inhibitors, driven by their effectiveness in lowering LDL cholesterol levels among high-risk patients. Specialty drugs also gain traction as personalized medicine advances, offering tailored solutions for complex cases like familial hypercholesterolemia. Although high costs limit widespread use, reimbursement policies and greater physician confidence are driving uptake in developed markets. As patents expire for leading biologics, biosimilars are expected to emerge, creating further opportunities while enhancing accessibility in cost-sensitive regions.
- For instance, Amgen’s PCSK9 inhibitor Repatha has been reported to reduce LDL cholesterol by up to 1.5 mmol/L in high-risk patients, showing significant efficacy and helping a substantial patient subset achieve cholesterol targets beyond statins alone.
Key Challenges
High Cost of Advanced Therapies
The high pricing of biologics and specialty drugs poses a major barrier in the hyperlipidemia drugs market. Treatments like PCSK9 inhibitors, though effective, remain unaffordable for many patients, especially in developing economies. Limited reimbursement coverage further restricts access, leading to uneven adoption across regions. Healthcare providers often prefer cost-effective statins, which reduces the potential reach of newer therapies. This cost challenge continues to hinder broad market penetration, forcing companies to focus on pricing strategies and collaborations with payers to improve affordability.
Patient Adherence and Long-Term Compliance Issues
Another critical challenge lies in ensuring patient adherence to long-term hyperlipidemia treatment. Many patients discontinue therapies once cholesterol levels normalize, which raises risks of relapse and cardiovascular events. Side effects associated with statins, such as muscle pain, further contribute to poor compliance. Lack of continuous follow-up and limited patient education exacerbate the issue. Pharmaceutical companies and healthcare providers must invest in adherence programs, digital health tools, and awareness campaigns to address this challenge, ensuring better outcomes and sustained market growth.
Regional Analysis
North America
North America dominated the Hyperlipidemia Drugs market in 2024 with 41% share, driven by high prevalence of cardiovascular diseases and widespread adoption of statins and advanced biologics. Strong healthcare infrastructure, early access to novel therapies, and significant awareness programs further strengthen demand. The U.S. leads with high prescription rates and robust clinical research, while Canada supports adoption through public health initiatives. Favorable reimbursement policies and the presence of major pharmaceutical companies also drive growth. Continued emphasis on preventive healthcare and rising use of PCSK9 inhibitors sustain the region’s leadership.
Europe
Europe accounted for 29% share of the Hyperlipidemia Drugs market in 2024, supported by strict cardiovascular disease management guidelines and high screening rates. Countries such as Germany, the UK, and France drive adoption due to strong healthcare coverage and access to advanced therapies. Widespread prescription of generic statins ensures affordability, while demand for biologics continues to rise in high-risk populations. The region benefits from government-led preventive health initiatives, further increasing early treatment uptake. With growing focus on reducing cardiovascular mortality, Europe remains a key contributor to global hyperlipidemia drug sales.
Asia-Pacific
Asia-Pacific captured 21% share of the Hyperlipidemia Drugs market in 2024 and is projected to be the fastest-growing region. Rising urbanization, changing lifestyles, and a surge in obesity and diabetes cases drive demand for cholesterol-lowering therapies. Countries like China, India, and Japan lead adoption, with expanding healthcare infrastructure and increasing access to generic statins supporting market growth. Government initiatives to reduce cardiovascular burden and rising health awareness encourage higher screening and treatment rates. Though biologics adoption is limited by costs, demand for affordable oral drugs strengthens Asia-Pacific’s growth potential.
Latin America
Latin America represented 6% share of the Hyperlipidemia Drugs market in 2024, driven by growing incidence of obesity and cardiovascular diseases in countries such as Brazil and Mexico. Expanding access to affordable generics and government-led health campaigns support adoption. The region faces challenges from limited healthcare budgets, but increasing investments in digital health programs and preventive screenings are improving awareness and treatment uptake. While use of advanced biologics is restricted due to cost, the demand for statins and cholesterol absorption inhibitors continues to expand steadily across the region.
Middle East & Africa
The Middle East & Africa held 3% share of the Hyperlipidemia Drugs market in 2024, with adoption concentrated in urban centers of the UAE, Saudi Arabia, and South Africa. Rising prevalence of obesity, diabetes, and cardiovascular risk factors fuels demand for cholesterol-lowering therapies. Government initiatives promoting preventive healthcare and early detection programs are boosting treatment penetration. However, limited healthcare resources and affordability constraints hinder widespread access to biologics. Growing availability of generic statins and international collaborations in healthcare infrastructure development are expected to support steady growth in the region.
Market Segmentations:
By Type
- Familial
- Acquired
By Drug Class
- Statins
- Bile acid sequestrants
- Cholesterol absorption inhibitors
- Fibric acid derivatives
By Route of Administration
- Oral
- Parenteral
By Distribution Channel
- Hospital pharmacy
- Retail pharmacy
- Online pharmacy
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Hyperlipidemia Drugs market includes major players such as Johnson & Johnson, F. Hoffmann-La Roche Ltd, Amgen Inc., Eli Lilly and Company, AstraZeneca PLC, Dr. Reddy’s Laboratories Limited, Merck & Co., Inc., Bristol-Myers Squibb Company, Alnylam Pharmaceuticals, Inc., and GSK plc. These companies drive competition through strong portfolios of statins, biologics, and novel therapies targeting both acquired and familial hyperlipidemia. Leading firms invest heavily in research on PCSK9 inhibitors, RNA-based treatments, and combination drugs to enhance efficacy and address resistant patient groups. Partnerships and acquisitions strengthen market positioning, while generic manufacturers improve accessibility in cost-sensitive regions. Companies also focus on expanding global distribution networks and patient adherence programs to increase long-term treatment compliance. With rising cardiovascular disease prevalence and demand for advanced therapies, competition remains intense, pushing players to differentiate based on clinical outcomes, safety, affordability, and innovative treatment pipelines.
Key Player Analysis
- Johnson & Johnson
- Hoffmann-La Roche Ltd
- Amgen Inc.
- Eli Lilly And Company
- AstraZeneca PLC
- Reddy’s Laboratories Limited
- Merck & Co., Inc.
- Bristol-Myers Squibb Company
- Alnylam Pharmaceuticals, Inc.
- GSK plc
Recent Developments
- In August 2025, the FDA expanded Repatha (evolocumab) indication to include adults at increased MACE risk from uncontrolled LDL-C.
- In June 2025, Merck announced positive topline Phase III results for enlicitide decanoate in hyperlipidemia trials
- In March 2025, AstraZeneca’s experimental oral AZD0780 showed ~50.7 % LDL-C reduction at 12 weeks (added to statin).
- In May 2024, Roche’s Tina-quant® Lp(a) assay received FDA Breakthrough Device Designation.
Report Coverage
The research report offers an in-depth analysis based on Type, Drug Class, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising global cardiovascular disease prevalence.
- Statins will continue to dominate prescriptions due to cost-effectiveness and proven outcomes.
- Biologics such as PCSK9 inhibitors will expand adoption among high-risk patients.
- RNA-based therapies will gain attention as innovative options for resistant cases.
- Combination therapies will rise to improve treatment outcomes and adherence.
- Emerging biosimilars will increase accessibility of advanced biologics in cost-sensitive markets.
- Asia-Pacific will record the fastest growth supported by expanding healthcare access.
- Preventive screening programs will drive earlier diagnosis and long-term therapy adoption.
- Pharmaceutical companies will invest in R&D to develop safer and more effective drugs.
- Patient adherence programs and digital health tools will shape future treatment compliance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The increasing global burden of cardiovascular diseases, fueled by unhealthy diets, obesity, and sedentary lifestyles, is driving demand for hyperlipidemia drugs as effective cholesterol management becomes a critical component of preventive healthcare.
Increasing Awareness and Screening Programs
Government and healthcare organization-led awareness campaigns and screening initiatives are leading to earlier detection of hyperlipidemia, resulting in higher prescription rates and improved long-term adherence to drug therapies.
Advancements in Novel Therapeutics
The introduction of advanced drug classes such as PCSK9 inhibitors and RNA-based therapies is expanding treatment options for patients resistant to traditional statins, addressing unmet needs and driving market growth.
Expansion of Combination Therapies
The growing use of combination therapies, such as statins with cholesterol absorption inhibitors, is improving treatment effectiveness for resistant cases and encouraging pharmaceutical companies to develop fixed-dose combinations, thereby expanding the market.
Improved Healthcare Access in Emerging Markets
Expanding healthcare infrastructure and increased access to affordable generic statins in regions like Asia-Pacific and Latin America are enabling broader patient reach and supporting rapid market growth in these areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hyperlipidemia Drugs market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hyperlipidemia Drugs market projected to grow between 2025 and 2032?
Which Hyperlipidemia Drugs market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hyperlipidemia Drugs market?
Who are the leading companies in the Hyperlipidemia Drugs market?
Which region commanded the largest share of the Hyperlipidemia Drugs market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Familial
- 1.2.2 Acquired
- 1.3 By Drug Class
- 1.3.1 Statins
- 1.3.2 Bile acid sequestrants
- 1.3.3 Cholesterol absorption inhibitors
- 1.3.4 Fibric acid derivatives
- 1.3.5 PCSK9 inhibitors
- 1.3.6 RNA-based therapies
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Parenteral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15.2 billion → 2032: USD 24.04 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hyperlipidemia Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hyperlipidemia Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hyperlipidemia Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hyperlipidemia Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hyperlipidemia Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hyperlipidemia Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hyperlipidemia Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hyperlipidemia Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15.2 billion → 2032: USD 24.04 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hyperlipidemia Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Familial
- 12.3.7.2 Acquired
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Statins
- 12.4.7.2 Bile acid sequestrants
- 12.4.7.3 Cholesterol absorption inhibitors
- 12.4.7.4 Fibric acid derivatives
- 12.4.7.5 PCSK9 inhibitors
- 12.4.7.6 RNA-based therapies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Parenteral
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hyperlipidemia Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hyperlipidemia Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hyperlipidemia Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Johnson & Johnson
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 F. Hoffmann-La Roche Ltd
- 17.4 Amgen Inc.
- 17.5 Eli Lilly and Company
- 17.6 AstraZeneca PLC
- 17.7 Dr. Reddy’s Laboratories Limited
- 17.8 Merck & Co., Inc.
- 17.9 Bristol-Myers Squibb Company
- 17.10 Alnylam Pharmaceuticals, Inc.
- 17.11 GSK plc
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

