
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia Pacific Ceramic Fiber Market Size 2024 | USD 986.5 Million |
| Asia Pacific Ceramic Fiber Market, CAGR | 5.8% |
| Asia Pacific Ceramic Fiber Market Size 2032 | USD 1548.75 Million |
Market Overview:
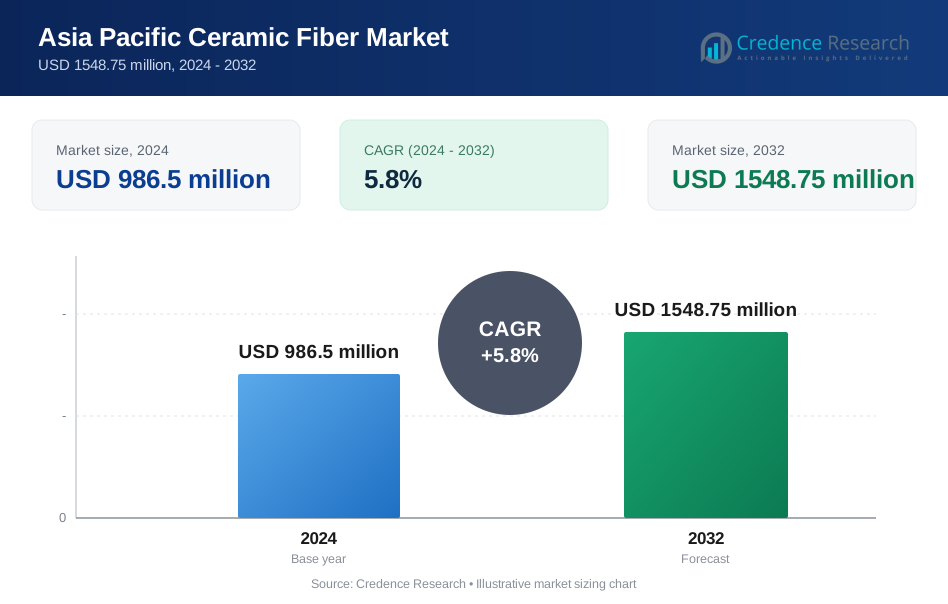
The Asia Pacific Ceramic Fiber Market is projected to grow from USD 986.5 million in 2024 to USD 1548.75 million by 2032, at a CAGR of 5.8% from 2024 to 2032.
Key drivers fueling the growth of the ceramic fiber market in Asia Pacific include the escalating demand for energy-efficient insulation materials, stringent regulations on energy consumption, and the growing need for fire-resistant materials. Ceramic fibers offer excellent thermal insulation properties, which help reduce energy consumption and improve operational efficiency. Additionally, the rise in global awareness regarding environmental sustainability is pushing industries to adopt more eco-friendly materials. Furthermore, the expanding industrial base in countries like China, India, and Japan, coupled with a surge in infrastructure development, has led to a rise in the demand for high-temperature insulation solutions. The growing trend of adopting renewable energy sources also drives the need for advanced thermal insulation products. Additionally, advancements in ceramic fiber production technologies and the increasing adoption of these materials in industrial applications further contribute to market growth.
Regionally, Asia Pacific holds a dominant share in the global ceramic fiber market due to its strong industrial base and rapid infrastructure development. China leads the market in terms of production and consumption, followed by India and Japan, where ceramic fiber usage is increasing in sectors such as manufacturing, automotive, and petrochemicals. The growing demand for high-performance insulation in various industries, particularly in the automotive and energy sectors, is a key factor driving market growth. The ongoing industrialization and increasing construction activities in countries like India, along with a growing emphasis on energy conservation, are expected to fuel the market demand further in the coming years. Additionally, government initiatives aimed at promoting energy efficiency in industries across the region are expected to enhance the adoption of ceramic fiber materials.
Market Insights:
- The Asia Pacific ceramic fiber market is projected to grow from USD 986.5 million in 2024 to USD 1548.75 million by 2032, at a CAGR of 5.8%.
- Increased demand for energy-efficient insulation materials is driving the growth of the market, as ceramic fibers offer excellent thermal insulation properties.
- Stringent regulations on energy consumption across the region are pushing industries to adopt more eco-friendly insulation solutions, further fueling market expansion.
- Industrialization in countries like China, India, and Japan, along with rapid infrastructure development, is significantly increasing the demand for high-performance ceramic fiber products.
- Advancements in ceramic fiber production technologies are making these materials more cost-effective and improving their thermal insulation properties, boosting their adoption.
- China holds the largest market share, contributing more than 40% of the total market, driven by its robust industrial base and energy efficiency initiatives.
- Competition from alternative insulation materials such as mineral wool and fiberglass continues to challenge the ceramic fiber market, particularly in cost-sensitive sectors.
Market Drivers:
Growing Demand for Energy-Efficient Insulation Materials:
The rising demand for energy-efficient materials across various industries is one of the key drivers for the growth of the Asia Pacific ceramic fiber market. Ceramic fibers offer superior thermal insulation properties, which help reduce energy consumption, improve heat retention, and enhance operational efficiency in industrial processes. For instance, Morgan Advanced Materials has reported a 25% reduction in energy usage in industrial furnaces due to their ceramic fiber insulation. As industries seek to minimize energy usage and adhere to strict environmental regulations, the demand for advanced insulation materials like ceramic fibers continues to rise, particularly in high-temperature applications.
Stringent Regulations on Energy Consumption:
Governments across the Asia Pacific region are implementing stringent regulations to reduce energy consumption and promote environmental sustainability. These regulations are driving industries to adopt energy-efficient solutions, including the use of ceramic fibers for insulation. For instance, the Chinese government's regulations on energy efficiency have led to a 30% increase in the adoption of ceramic fibers in the industrial sector. As industries comply with these regulations, there is a significant increase in the adoption of high-performance insulation materials that meet sustainability goals while ensuring efficiency.
Increasing Industrialization and Infrastructure Development:
The rapid industrialization and expanding infrastructure in key countries such as China, India, and Japan are major factors contributing to the market's growth. As these nations continue to invest in large-scale infrastructure projects, the demand for high-performance materials, including ceramic fibers, has surged. For instance, the Indian government's "Make in India" initiative has boosted the manufacturing sector, resulting in a 40% increase in the demand for ceramic fibers. Ceramic fibers are widely used in industries like manufacturing, petrochemicals, automotive, and construction, further fueling market expansion.
Advancements in Ceramic Fiber Production Technologies:
Advancements in ceramic fiber manufacturing technologies have made it more cost-effective and efficient to produce these materials. Improved production methods have enabled the creation of higher-quality products with better insulation properties, which in turn enhances the overall performance of industrial processes. For instance, Unifrax Corporation has developed new manufacturing techniques that have reduced production costs by 15% while improving product quality. These technological developments have made ceramic fibers more accessible, accelerating their adoption across various sectors.
Market Trends:
Increasing Adoption of Eco-friendly Materials:
A key trend in the Asia Pacific ceramic fiber market is the growing emphasis on sustainability and eco-friendly materials. With increasing environmental awareness and stringent regulations aimed at reducing carbon footprints, industries are shifting towards sustainable solutions. For instance, Morgan Advanced Materials' ceramic fibers, which offer excellent thermal insulation properties, are being widely adopted not an eco-friendly alternative to conventional insulation materials. Ceramic fibers, which offer excellent thermal insulation properties, are being widely adopted as an eco-friendly alternative to conventional insulation materials. Their recyclability and energy-saving benefits align with the region's focus on environmental sustainability.
Technological Advancements in Production Methods:
Technological innovations in the production of ceramic fibers are significantly shaping market trends. Recent advancements in manufacturing processes have enhanced the quality, efficiency, and cost-effectiveness of ceramic fibers. For instance, Unifrax Corporation has developed new production methods resulting in high-performance ceramic fibers with superior heat resistance and improved durability. As a result, industries across various sectors are increasingly incorporating ceramic fibers into their operations to meet the growing demand for energy-efficient and high-performance materials.
Growth of High-Temperature Insulation Applications:
Another prominent trend is the growing use of ceramic fibers in high-temperature applications. For instance, Kyocera Corporation's ceramic fibers, known for their excellent thermal stability and resistance to high temperatures, are gaining traction in sectors such as petrochemicals, steel manufacturing, and automotive, further driving the market's expansion. As industrial processes across the region become more complex and energy-intensive, the need for materials capable of withstanding extreme temperatures has increased.
Rising Investment in Infrastructure and Industrial Projects:
The rapid industrialization and infrastructure development in countries like China and India are also contributing to the market’s growth. Significant investments in new infrastructure projects, including power plants and transportation networks, are driving demand for ceramic fibers. For instance, the Indian government's initiatives in large-scale infrastructure projects have boosted the demand for ceramic fibers by 30%. These fibers are used extensively for insulation in high-temperature environments, further contributing to their rising demand across various industries.
Market Challenges Analysis:
High Cost of Raw Materials:
One of the primary challenges faced by the Asia Pacific ceramic fiber market is the high cost of raw materials used in the production of ceramic fibers. The production of high-quality ceramic fibers requires specialized materials such as alumina and silica, which can be expensive. The fluctuating prices of these raw materials pose a challenge to manufacturers, particularly in the face of rising operational costs. This can lead to increased product prices, potentially limiting market growth in cost-sensitive industries.
Lack of Skilled Workforce:
Another challenge is the limited availability of skilled labor required to handle advanced ceramic fiber production processes. As the market for ceramic fibers continues to grow, the demand for workers with expertise in high-temperature insulation technologies is rising. However, the shortage of skilled technicians and engineers in this field can hinder the efficiency and productivity of manufacturers. This challenge is particularly prominent in emerging markets such as India, where the industrial sector is rapidly expanding.
Environmental and Health Concerns:
Despite their eco-friendly attributes, the production and use of ceramic fibers raise some environmental and health concerns. Workers exposed to high concentrations of ceramic fiber dust during manufacturing or installation can face respiratory issues. This has led to regulatory scrutiny in some countries, imposing stricter health and safety standards on manufacturers and users. Compliance with these regulations often requires significant investment in protective equipment and safety protocols, adding to operational costs.
Competition from Alternative Insulation Materials:
The ceramic fiber market also faces competition from alternative insulation materials, such as mineral wool and fiberglass, which are often less expensive and easier to handle. These alternatives, while not as thermally efficient as ceramic fibers, continue to present significant competition, particularly in industries where cost plays a critical role in decision-making.
Market Opportunities:
The Asia Pacific ceramic fiber market presents significant opportunities driven by the increasing demand for high-performance materials in various industries. With rapid industrialization and infrastructure development, especially in emerging economies like China and India, the need for advanced insulation materials is expanding. Ceramic fibers offer superior thermal stability and energy efficiency, making them ideal for use in industries such as petrochemicals, manufacturing, automotive, and power generation. The rising focus on energy conservation and sustainable practices further creates opportunities for manufacturers to capitalize on the growing preference for eco-friendly insulation materials.
Additionally, ongoing technological advancements in the production of ceramic fibers present considerable market opportunities. Innovations in manufacturing techniques have led to the development of cost-effective and high-quality ceramic fibers, enhancing their performance and making them more accessible to a wider range of industries. This technological progress not only improves the material properties, such as heat resistance and durability, but also lowers production costs, increasing the market's potential. Furthermore, the growing adoption of renewable energy sources and the need for more efficient energy storage solutions provide new avenues for ceramic fiber applications, particularly in thermal insulation for energy systems. These factors, combined with the region's commitment to reducing carbon footprints, position the ceramic fiber market for continued growth and expansion.
Market Segmentation Analysis:
By Product:
The market is primarily divided into ceramic fiber blankets, boards, modules, papers, and others. Ceramic fiber blankets dominate the market due to their excellent thermal insulation properties and versatility in industrial applications, such as furnaces and kilns.
By Form:
The market is segmented into flexible, rigid, and paper forms. Flexible ceramic fibers, such as blankets and felts, are widely used due to their adaptability and ease of installation in various industrial environments. Rigid forms, such as boards and modules, are gaining traction in high-temperature applications, offering superior mechanical strength and structural integrity.
By Temperature:
The ceramic fiber market is categorized into low, medium, and high-temperature products. High-temperature ceramic fibers are in high demand across industries such as metallurgy, petrochemicals, and power generation due to their ability to withstand extreme conditions, providing superior heat resistance and thermal stability.
Segmentations:
By Product:
- Ceramic Fiber Blankets
- Boards
- Modules
- Papers
- Others
By Form:
- Flexible
- Rigid
- Paper
By Temperature:
- Low
- Medium
- High
By Application:
- Petrochemicals
- Steel Manufacturing
- Automotive
- Power Generation
- Construction
By Region:
- China
- India
- Japan
- South Korea
- Southeast Asia
- Rest of Asia Pacific
Regional Analysis:
China
China holds the largest market share in the Asia Pacific ceramic fiber market, accounting for more than 40% of the total market in 2023. The country’s rapid industrialization and increasing demand for high-performance insulation materials in industries such as petrochemicals, manufacturing, and power generation are key factors contributing to this dominance. China’s significant infrastructure development projects and strong industrial base continue to fuel the demand for ceramic fibers, particularly for high-temperature applications. The Chinese government’s focus on energy efficiency and sustainability has further supported the widespread adoption of ceramic fibers in various industrial processes, especially in energy-intensive sectors.
India
India holds the second-largest market share in the Asia Pacific ceramic fiber market, representing 20% of the overall market in 2023. The country's growing industrial sector, along with ongoing infrastructure development and a shift towards energy-efficient solutions, has led to an increasing demand for ceramic fiber products. Industries such as steel manufacturing, automotive, and power generation are seeing substantial growth, driving the need for thermal insulation solutions. India's commitment to reducing carbon emissions and enhancing energy conservation further supports the adoption of ceramic fibers, especially in high-temperature applications where superior insulation properties are required.
Japan
Japan accounts for 15% of the Asia Pacific ceramic fiber market. The country's mature industrial sector, including automotive, petrochemicals, and electronics, demands high-quality ceramic fiber products for various applications. Japan’s commitment to technological advancements and environmental sustainability is a significant factor in driving the adoption of energy-efficient insulation solutions. The automotive and manufacturing sectors in Japan continue to be key contributors to the demand for ceramic fibers, with a focus on improving thermal efficiency, reducing energy consumption, and enhancing operational performance.
South Korea and Southeast Asia
South Korea and Southeast Asia collectively contribute 25% of the market share. South Korea, with its advanced manufacturing capabilities, is seeing increased demand for ceramic fibers in high-tech industries such as electronics and automotive. Southeast Asia, including countries like Indonesia, Thailand, and Vietnam, is experiencing rapid industrial growth, which is fueling the demand for ceramic fibers. The increasing emphasis on infrastructure development and energy conservation regulations in these regions further drives the market. As industries continue to expand and adopt more energy-efficient materials, both South Korea and Southeast Asia are expected to experience steady growth in the coming years.
Key Player Analysis:
- Morgan Advanced Materials
- Unifrax
- RHI Magnesita
- Isolite Insulating Products Co. Ltd.
- Promat International
- ICL Industrial Products
- Thermal Ceramics
- Nutec Bickley
- Kaohsiung Ceramic Fiber Industry Co., Ltd.
- Chongqing Ceramic Fiber Insulation Material Co., Ltd.
Competitive Analysis:
The Asia Pacific ceramic fiber market is highly competitive, with several key players striving to expand their market presence through innovation, strategic partnerships, and geographic expansion. For instance, Morgan Advanced Materials, Unifrax, and RHI Magnesita are focusing on product innovation, offering high-performance ceramic fibers that meet the increasing demand for energy-efficient insulation solutions. Leading companies such as Morgan Advanced Materials, Unifrax, and RHI Magnesita are focusing on product innovation, offering high-performance ceramic fibers that meet the increasing demand for energy-efficient insulation solutions. These companies are leveraging advanced manufacturing technologies to reduce production costs and enhance product quality.
Additionally, regional players like Isolite Insulating Products Co. Ltd. and Nutec Bickley are strengthening their market position by improving distribution networks and increasing their product offerings. With growing industrialization in countries like China, India, and Japan, market leaders are investing heavily in infrastructure and expanding production capacities to meet the rising demand for high-temperature insulation. Competitive strategies are focused on catering to diverse industrial applications and maintaining cost-effective solutions for energy-efficient solutions.
Recent Developments:
- In October 2024, RHI Magnesita announced its half-year results for 2024, highlighting strong cash conversion despite challenging market conditions. The company remains on track to achieve an Adjusted EBITA of at least €410 million at a margin of 11.0% in 2024, driven by normal seasonality in the cement market, a higher weighting of steel sales volumes in the second half, and unit cost savings from increased capacity utilization and efficiency measures.
- In February 2024, RHI Magnesita's Annual Report for 2023 was released, emphasizing the company's strategy to grow primarily through acquisitions rather than greenfield expansion. This approach aims to avoid over-supplying a low-growth market while seeking significant M&A synergy potential from cost savings, network efficiencies, cross-selling, and procurement benefits. The company completed six acquisitions in 2023 and a total of nine since December 2021, with plans to benefit from a full year contribution from these acquisitions in 2024.
- In August 2023, Morgan Advanced Materials was mentioned as one of the key players in the ceramic fiber market, contributing to the Asia Pacific region's growth due to its significant presence in the market.
Market Concentration & Characteristics:
The Asia Pacific ceramic fiber market is moderately concentrated, with a few dominant players holding significant market share, while regional players also maintain a strong presence. Leading companies such as Morgan Advanced Materials, Unifrax, and RHI Magnesita dominate the market, leveraging their extensive production capabilities and global distribution networks to cater to the growing demand across industries like petrochemicals, power generation, and automotive. The market is characterized by strong competition driven by product innovation, cost efficiency, and technological advancements. Companies focus on enhancing product quality and expanding their portfolios to meet the increasing need for energy-efficient and high-performance insulation materials. The market also sees active consolidation through mergers, acquisitions, and partnerships, allowing major players to increase their reach and operational efficiency. Despite the dominance of large players, regional and local manufacturers continue to serve niche markets with tailored offerings, contributing to the overall market diversity.
Report Coverage:
The research report offers an in-depth analysis based on Product, Form, Temperature, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Asia Pacific ceramic fiber market is expected to continue growing due to increasing demand for energy-efficient insulation materials across industrial sectors.
- Rising industrialization in countries such as China, India, and Southeast Asia will significantly drive the demand for ceramic fibers.
- Key industries, including petrochemicals, automotive, power generation, and steel manufacturing, will continue to be major consumers of ceramic fibers.
- Advancements in production technologies will make ceramic fibers more cost-effective and enhance their performance, leading to broader adoption.
- The focus on environmental sustainability will drive increased use of ceramic fibers, given their energy-saving properties and recyclability.
- High-temperature applications will remain a major growth area, especially in energy-intensive industries like metallurgy and chemicals.
- Stringent regulations around energy conservation and carbon emissions in the region will further boost the adoption of ceramic fibers.
- The development of infrastructure and construction projects across the region will increase the need for high-performance insulation materials.
- Companies will increasingly invest in R&D to develop innovative ceramic fiber products with improved thermal efficiency and durability.
- The market will likely see continued consolidation through mergers and partnerships, allowing players to expand their reach and product offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Asia Pacific Ceramic Fiber Market?
What are the key drivers for the growth of the ceramic fiber market in Asia Pacific?
How do ceramic fibers contribute to energy efficiency?
Which countries are driving the demand for ceramic fibers in Asia Pacific?
What role do government initiatives play in the market growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Ceramic Fiber Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Ceramic Fiber Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 986.5 million → 2032: USD 1548.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Ceramic Fiber Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Ceramic Fiber Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Ceramic Fiber Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Ceramic Fiber Market Drivers
- 3.3 Asia Pacific Ceramic Fiber Market Restraints & Challenges
- 3.4 Asia Pacific Ceramic Fiber Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Ceramic Fiber Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Ceramic Fiber Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Ceramic Fiber category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Ceramic Fiber Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Ceramic Fiber Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Ceramic Fiber market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Ceramic Fiber Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Ceramic Fiber Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Ceramic Fiber Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Ceramic Fiber (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Ceramic Fiber Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Ceramic Fiber Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Ceramic Fiber Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Ceramic Fiber Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Ceramic Fiber Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Ceramic Fiber Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Ceramic Fiber Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Ceramic Fiber Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Ceramic Fiber Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
