
Market Overview:
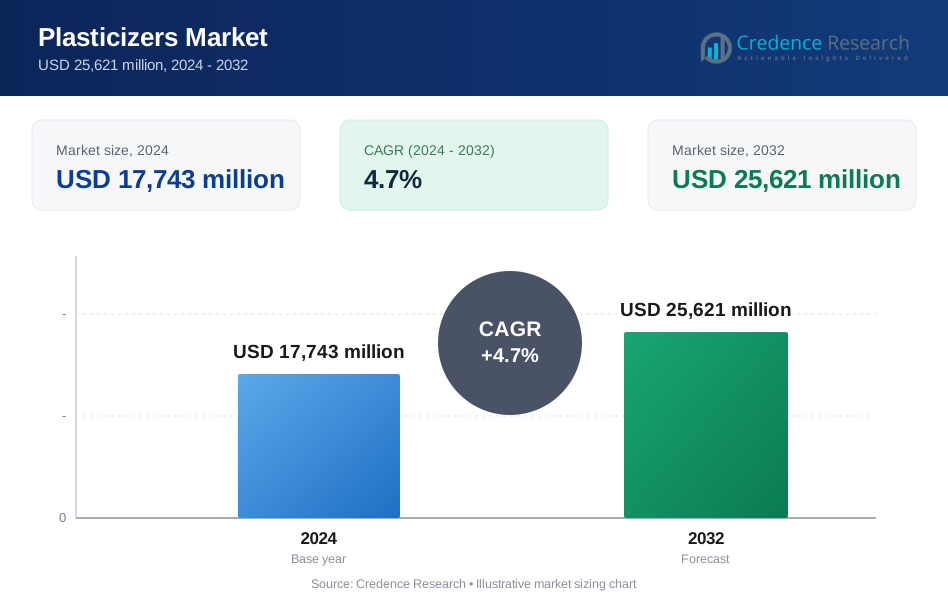
The Plasticizers market was valued at USD 17,743 million in 2024. The market is projected to reach USD 25,621 million by 2032. This growth reflects a 4.7% CAGR from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plasticizers Market Size 2024 | USD 17,743 million |
| Plasticizers Market , CAGR | 4.7% |
| Plasticizers Market Size 2032 | USD 25,621 million |
Market growth is driven by rising demand for flexible PVC across construction, automotive, and consumer goods. Builders use plasticized materials for cables, flooring, and roofing membranes. Automotive producers rely on plasticizers for interior trims and wire insulation. Packaging manufacturers increase usage for films and sheets requiring softness and durability. Urbanization supports steady infrastructure development. Product innovation improves performance and safety profiles. Manufacturers also shift toward efficient processing to reduce production costs and improve material consistency across applications.
Asia Pacific leads the market due to strong manufacturing activity and large construction output. China and India remain key contributors because of rapid urban growth. Southeast Asian countries show rising demand from packaging and consumer goods production. Europe maintains stable demand driven by automotive and building renovation activities. North America benefits from steady industrial output and replacement demand. Emerging markets in Latin America and the Middle East gain traction as infrastructure investment expands and local plastic processing capacity improves.

Market Insights:
- The Plasticizers market was valued at USD 17,743 million in 2024 and is projected to reach USD 25,621 million by 2032, expanding at a 4.7% CAGR, supported by steady PVC demand across construction, automotive, and consumer goods.
- Asia-Pacific (45%), Europe (25%), and North America (20%) dominate due to strong manufacturing bases, mature construction activity, and established polymer processing capacity.
- Asia-Pacific also remains the fastest-growing region, holding about 45% share, driven by infrastructure expansion, urban housing demand, and large-scale PVC production in China and India.
- By product type, phthalate plasticizers account for around 65% share due to cost efficiency and broad PVC compatibility, while non-phthalate plasticizers hold nearly 35%, supported by regulated and sensitive applications.
- By application, wire and cable leads with about 40% share, followed by flooring and wall covering at nearly 30%, reflecting strong demand from power infrastructure and building construction.
Market Drivers:
Strong Demand From Flexible PVC Applications Across Construction And Infrastructure Sectors
The Plasticizers market benefits from steady growth in flexible PVC demand. Construction projects use plasticized PVC for cables, pipes, and flooring. Infrastructure expansion supports long product lifecycles and repeat material use. Urban housing drives consumption of flexible building materials. Plasticizers improve softness and durability in harsh environments. Manufacturers rely on consistent performance for large-scale projects. Public infrastructure upgrades sustain long-term material demand. The sector values cost efficiency and material reliability.
- For instance, BASF SE reports that its Palatinol® TOTM (Trioctyl Trimellitate) plasticizer is designed for long-term cable insulation use up to 90 °C and 105 °C, meeting stringent VDE and UL standards for building wiring and automotive applications.
Rising Use In Automotive Interiors And Electrical Systems For Performance Enhancement
Automotive producers use plasticizers for interior trims and dashboards. Wire and cable insulation requires flexibility and heat resistance. Vehicle production volumes support stable material consumption. Lightweight components improve fuel efficiency targets. Plasticizers support vibration resistance and noise control. Design flexibility helps meet comfort expectations. The Plasticizers market aligns with evolving vehicle standards. Supply chains prioritize dependable formulation quality.
- For instance, LANXESS AG states its Mesamoll® plasticizer maintains elasticity below −50 °C, supporting automotive interior performance in cold climates.
Growth In Consumer Goods And Packaging Manufacturing Activities
Consumer goods producers rely on plasticized materials for durability. Packaging films need flexibility for transport and storage. E-commerce growth increases packaging volumes. Plasticizers help maintain product integrity under stress. Manufacturers prefer materials that allow fast processing. High output facilities depend on stable compound behavior. Brand owners value consistent appearance and feel. These factors support steady demand growth.
Expansion Of Industrial Manufacturing And Polymer Processing Capacity
Industrial plants increase polymer processing investments worldwide. Plasticizers support molding and extrusion efficiency. Production lines value predictable flow behavior. Large-scale manufacturing needs uniform material properties. Processing stability reduces downtime risks. Cost control remains a core priority for producers. Plasticizers support scale economies across industries. Industrial growth sustains base demand levels.
Market Trends:
Shift Toward Balanced Performance Formulations With Improved Efficiency Profiles
Producers focus on optimized plasticizer blends for performance balance. Formulations aim for durability and process stability. End users demand materials with consistent output quality. Efficiency gains help reduce waste rates. Manufacturers refine blends for specific applications. The Plasticizers market reflects this formulation focus. Custom solutions gain preference over generic grades. Technical support becomes a key differentiator.
- For instance, Eastman Chemical Company confirms its Eastman 168™ non-phthalate plasticizer delivers low volatility below 0.01% at 130 °C, improving processing consistency in PVC compounding.
Rising Preference For Application-Specific Plasticizer Solutions
End users seek tailored materials for targeted uses. Flooring, cables, and films require different flexibility levels. Suppliers develop niche-grade offerings. Customization improves customer retention. Processing conditions drive formulation choices. Buyers value technical collaboration with suppliers. Plasticizers adapt to varied polymer systems. Specialized demand shapes product portfolios.
- For instance, Perstorp Holding AB reports that its Emoltene™ plasticizers achieve low fogging values below 2 mg, meeting automotive interior standards.
Integration Of Advanced Compounding And Processing Technologies
Modern compounding improves dispersion and material uniformity. Automation supports tighter quality control. Process optimization reduces energy use. Manufacturers invest in upgraded production lines. Technology adoption shortens production cycles. Consistent batch quality gains importance. Plasticizers support compatibility with advanced equipment. Innovation supports competitive positioning.
Increased Focus On Supply Chain Reliability And Regional Sourcing
Manufacturers prioritize stable raw material access. Regional sourcing reduces logistics risks. Local production supports faster delivery cycles. Buyers seek suppliers with diversified capacity. Supply continuity influences long-term contracts. The Plasticizers market responds to sourcing resilience needs. Strategic partnerships strengthen distribution networks. Reliability becomes a selection criterion.
Market Challenges Analysis:
Regulatory Pressure On Chemical Usage And Compliance Requirements
Chemical regulations affect plasticizer selection decisions. Compliance adds testing and certification costs. Manufacturers adjust formulations to meet standards. Approval timelines can slow product launches. Documentation requirements increase operational complexity. The Plasticizers market faces regional regulatory variation. Smaller producers face higher compliance burdens. Regulatory clarity remains critical for planning.
Volatility In Raw Material Supply And Pricing Stability
Feedstock availability affects production planning. Price fluctuations impact margin control. Manufacturers manage inventory risks carefully. Long-term contracts reduce exposure but limit flexibility. Supply disruptions challenge delivery commitments. It requires constant cost monitoring. Buyers seek predictable pricing structures. Volatility influences procurement strategies.
Market Opportunities:
Expansion In Emerging Economies With Growing Industrial And Construction Activity
Emerging regions invest heavily in infrastructure. Industrialization raises polymer consumption levels. Local manufacturing capacity continues to expand. Plasticizers support diverse end-use needs. The Plasticizers market can tap unmet regional demand. Suppliers benefit from early market entry. Distribution partnerships support growth access. Rising incomes boost downstream consumption.
Innovation In High-Performance And Specialty Plasticizer Applications
Specialty applications create new revenue paths. Advanced polymers need compatible plasticizers. Performance-driven sectors demand tailored solutions. Innovation supports differentiation in competitive markets. Technical expertise strengthens customer relationships. Producers invest in research-led development. Specialty demand improves margin potential. This opportunity supports long-term growth.
Market Segmentation Analysis:
By Product Type
Phthalate plasticizers hold wide use due to cost efficiency and strong compatibility with PVC. These products support large-volume applications that require stable flexibility. Non-phthalate plasticizers gain preference in regulated and sensitive uses. Manufacturers adopt these alternatives to meet safety and compliance needs. Performance parity improves adoption rates. Product selection depends on end-use requirements. The Plasticizers market balances cost and regulatory expectations. It supports both segments through tailored formulations.
- For instance, UPC Technology Corporation supplies DINP grades meeting REACH compliance for flooring systems with controlled migration levels below EU limits.
By Application
Wire and cable applications rely on plasticizers for insulation flexibility and thermal resistance. Flooring and wall covering demand durability and surface stability. Film and sheet uses require uniform softness and tear resistance. Each application values predictable material behavior. Processing efficiency remains a key requirement. Plasticizers enable consistent output across varied formats. Application-specific grades support performance needs. Demand aligns with industrial output trends.
- For instance, Evonik Industries AG states its plasticizer additives support PVC cable compounds rated for continuous operation at 105 °C under IEC standards.
By End-Use Industry
Building and construction leads consumption due to high PVC usage. Automotive and transportation use plasticized materials for interiors and wiring systems. Consumer goods depend on flexible plastics for durability and comfort. Each industry prioritizes long service life. Cost control influences material choice. Plasticizers support design flexibility. End-use diversity stabilizes demand patterns.
Segmentation:
By Product Type
- Phthalate Plasticizers
- Non-Phthalate Plasticizers
By Application
- Wire and Cable
- Flooring and Wall Covering
- Film and Sheet
By End-Use Industry
- Building and Construction
- Automotive and Transportation
- Consumer Goods
By Geographic Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the global market at around 45%. The Plasticizers market in this region benefits from large-scale manufacturing and construction activity. China leads due to high PVC consumption across infrastructure and consumer goods. India supports demand through urban housing and power cable expansion. Southeast Asia adds volume from packaging and footwear production. Cost-sensitive manufacturing favors high-volume plasticizer usage. Strong domestic supply chains improve regional competitiveness.
Europe
Europe accounts for nearly 25% of global demand. The Plasticizers market in Europe reflects stable consumption across construction and automotive sectors. Western Europe leads due to mature building renovation activity. Germany and France anchor demand through industrial and transport applications. Regulatory oversight shapes product selection toward compliant formulations. Producers focus on performance consistency and quality assurance. Regional demand remains steady rather than rapid.
North America
North America represents about 20% of the overall market. The Plasticizers market in this region relies on automotive, construction, and consumer goods demand. The United States dominates due to large-scale polymer processing capacity. Infrastructure maintenance supports steady PVC usage. Manufacturers emphasize reliability and long-term supply contracts. Domestic production reduces import dependence. Demand growth remains moderate and stable.
Key Player Analysis:
- BASF SE
- Eastman Chemical Company
- Dow Inc.
- ExxonMobil Corporation
- Evonik Industries AG
- LG Chem Ltd.
- Arkema SA
- LANXESS AG
Competitive Analysis:
The Plasticizers market shows moderate consolidation with strong global and regional players. Large chemical companies lead through broad product portfolios and scale advantages. These firms invest in formulation depth to serve regulated and high-volume applications. Cost leadership remains critical in commodity grades. Specialty offerings help suppliers defend margins. Regional producers compete on pricing and local supply reliability. Strategic capacity placement supports faster delivery. It rewards players with feedstock access, technical service strength, and long-term customer contracts.
Recent Developments:
- In November 2025, BASF officially commissioned its high-performance dispersant production line at the Jiangbei New Material Technology Park, Nanjing, China. This new facility establishes a stable local supply to support fast-growing market demand in the industrial coatings and automotive sectors. The plant employs advanced CFRP technology for dispersants and state-of-the-art production processes, enabling the green transformation of customers in Asia with lower product carbon footprint (PCF) products.
- In June 2025, Evonik decided to localize the final production step of its POLYVEST® ST-E 60 in Shanghai, China. This expansion significantly increased production capacity of silane-functionalized polybutadienes, with the expansion expected to be fully operational by Q3 2025. This strategic investment supports Evonik's long-term goals of sustainability, operational excellence, and regional growth in Asia, enhancing supply security and customer proximity in the region.
- In May 2024, ExxonMobil announced that its new 20-liter lubricant pails now come in plastic packaging made of 50% post-consumer recycled (PCR) content, including discarded plastic pails, jars, and battery casings. The equivalent of roughly 2.3 million plastic bottles has been recycled to make these pails since launching in 2023. This initiative surpasses India's 30% recycled plastic requirement and represents a first in pail-packaging for lubricants in India.
- In November 2024, ExxonMobil announced a $200 million investment to expand advanced recycling operations. The company built new facilities at its Baytown and Beaumont sites to begin operations in 2026, adding 350 million pounds per year of advanced recycling capacity. This brings ExxonMobil's total capacity to 500 million pounds annually and positions the company toward its goal of processing 1 billion pounds of plastic annually by 2027 through facilities across North America, Europe, and Asia.
Report Coverage:
The research report offers an in-depth analysis based on product type, application, end-use industry, and geographic region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand remains tied to construction and infrastructure activity.
- Non-phthalate solutions gain wider commercial acceptance.
- Product customization supports application-specific growth.
- Asia-Pacific retains manufacturing leadership.
- Regulatory clarity shapes long-term formulation strategies.
- Supply chain resilience becomes a buying criterion.
- Process efficiency drives supplier differentiation.
- Automotive interiors sustain stable consumption.
- Packaging demand supports volume consistency.
- Technical collaboration strengthens customer retention.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Plasticizers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Plasticizers market projected to grow between 2025 and 2032?
Which Plasticizers market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Plasticizers market?
Who are the leading companies in the Plasticizers market?
Which region commanded the largest share of the Plasticizers market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,743 million → 2032: USD 25,621 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plasticizers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plasticizers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plasticizers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plasticizers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plasticizers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plasticizers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plasticizers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plasticizers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,743 million → 2032: USD 25,621 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plasticizers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plasticizers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Plasticizers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Plasticizers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

