
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia Pacific Commercial Amino Acids Market Size 2024 | USD 618.60 million |
| Asia Pacific Commercial Amino Acids Market, CAGR | 7.54% |
| Asia Pacific Commercial Amino Acids Market Size 2032 | USD 1106.18 million |
Market Overview:
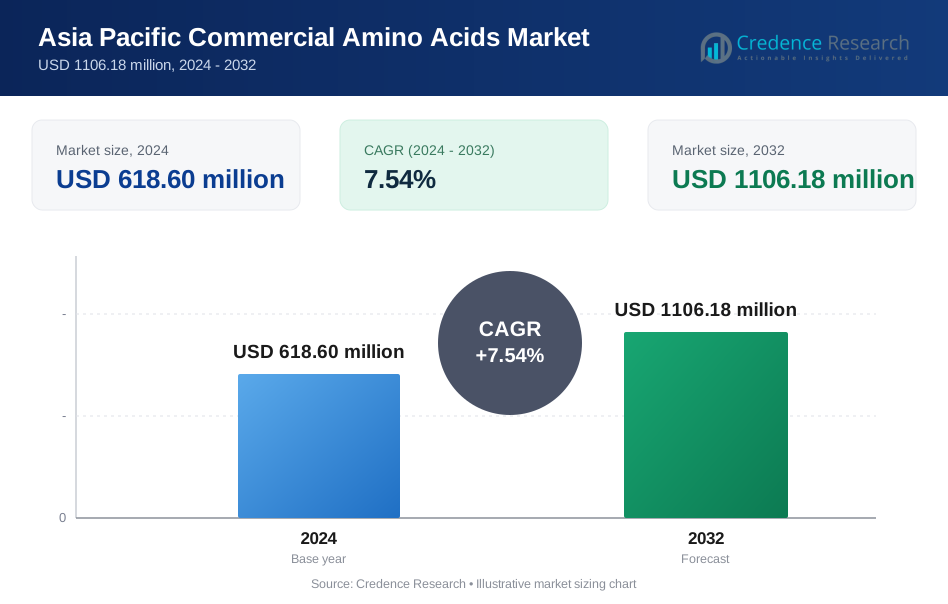
The Asia Pacific Commercial Amino Acids Market is projected to grow from USD 618.60 million in 2024 to an estimated USD 1106.18 million by 2032, with a compound annual growth rate (CAGR) of 7.54% from 2024 to 2032.
Several key drivers are propelling the growth of the Asia Pacific commercial amino acids market. The expanding pharmaceutical industry in the region has created a demand for amino acids as essential components in drug formulations, particularly for biopharmaceuticals and parenteral nutrition. Additionally, the booming livestock sector has significantly increased the consumption of amino acids such as lysine, methionine, and threonine in animal feed to enhance growth and productivity. Furthermore, the region’s evolving food and beverage industry has witnessed a surge in demand for amino acid-enriched functional foods, catering to the preferences of a health-conscious population. Advances in biotechnology and fermentation processes are also making amino acid production more efficient, reducing costs, and enabling wider accessibility.
Regionally, China and India dominate the Asia Pacific commercial amino acids market, fueled by their large populations, rapid urbanization, and increasing disposable incomes. China, being a global leader in amino acid production, exports substantial quantities to other regions while meeting its domestic demand. Meanwhile, Japan and South Korea are notable for their advanced pharmaceutical and nutraceutical sectors, driving the demand for high-purity amino acids. Emerging economies in Southeast Asia, including Indonesia and Vietnam, are also witnessing accelerated growth due to rising agricultural and industrial activities. The diverse economic and industrial landscape of the Asia Pacific region ensures sustained growth and the development of new market opportunities.
Market Insights:
- The Asia Pacific commercial amino acids market is projected to grow from USD 618.60 million in 2024 to USD 1106.18 million by 2032, with a robust CAGR of 7.54%.
- Expanding pharmaceutical industries in countries like Japan, India, and South Korea drive demand for high-purity amino acids used in biopharmaceuticals and parenteral nutrition.
- Rising meat consumption in China, India, and Vietnam has fueled the demand for amino acid-enriched animal feed, particularly lysine and methionine, to improve livestock productivity.
- Increased consumer interest in health benefits has driven the adoption of amino acids in functional foods and nutraceuticals, especially in developed markets like Japan and Australia.
- Technological advancements in fermentation and biotechnology have improved production efficiency, enabling cost-effective manufacturing and broader market access.
- Southeast Asia, including Indonesia and Vietnam, is emerging as a significant growth hub due to rapid industrialization, urbanization, and government initiatives to boost agricultural productivity.
- Challenges such as fluctuating raw material costs, regulatory complexities, and competition from synthetic alternatives continue to influence the market dynamics, requiring innovation and strategic investment.
Market Drivers:
Growing Demand in Pharmaceuticals
The pharmaceutical industry's expansion across the Asia Pacific region is a significant driver for the commercial amino acids market. Amino acids are vital components in drug formulations, including biopharmaceuticals, parenteral nutrition, and metabolic treatments. Countries such as Japan, South Korea, and India are investing heavily in the production of advanced drugs and therapies, creating a steady demand for high-purity amino acids like L-Glutamine and L-Arginine. For instance, Ajinomoto Bio-Pharma Services has developed a high-purity L-Glutamine product used in parenteral nutrition, which meets stringent pharmaceutical standards. Additionally, the rise in chronic diseases and an aging population further contribute to the growing utilization of amino acids in pharmaceutical applications, supporting the market's upward trajectory.
Rising Use in Animal Nutrition
The booming livestock sector in the Asia Pacific region is driving significant demand for amino acids used in animal feed. The increasing adoption of intensive farming practices has made amino acids like lysine, methionine, and threonine essential for enhancing animal growth, immunity, and productivity. Countries such as China, India, and Vietnam are witnessing rising meat consumption, necessitating efficient feed solutions. "For example, Evonik Industries has developed a fermentation-based DL-Methionine product called Mepron® that improves feed conversion efficiency and reduces nitrogen excretion in livestock. As farmers seek cost-effective ways to optimize livestock health, the role of amino acids in improving feed conversion efficiency becomes crucial, thereby bolstering market growth.
Surge in Functional Foods and Nutraceuticals
The rapid expansion of the functional foods and nutraceuticals sector is another key driver of the amino acids market in Asia Pacific. Growing consumer awareness of the health benefits associated with amino acids, such as improved muscle recovery, enhanced cognitive function, and better digestion, has led to increased incorporation of these compounds into dietary supplements and fortified food products. For instance, Kyowa Hakko Bio Co., Ltd. has introduced a range of amino acid-based supplements targeting muscle recovery and cognitive health. Countries like China, Japan, and Australia are at the forefront of this trend, as consumers increasingly demand innovative health-focused products. This shift is creating opportunities for manufacturers to introduce specialized formulations targeting diverse health concerns.
Advancements in Production Technologies
Technological advancements in amino acid production, particularly through microbial fermentation, are revolutionizing the industry. Innovations in biotechnology and the use of genetically modified organisms have improved yield efficiency and reduced production costs, making amino acids more accessible to a wider range of industries. For example, CJ CheilJedang has developed a microbial fermentation process that increases lysine production efficiency by 30%. These advancements are particularly evident in countries such as China and South Korea, where significant investments in research and development are driving innovation. As a result, manufacturers are better positioned to meet the growing demand from sectors such as pharmaceuticals, animal feed, and food and beverages while maintaining competitive pricing and quality.
Market Trends:
Rising Demand for Plant-Based Amino Acids
The Asia Pacific commercial amino acids market is witnessing a growing preference for plant-based amino acids. With increasing consumer inclination toward vegetarian and vegan diets, plant-derived amino acids such as soy-based and pea-based products are gaining traction. This trend aligns with the broader movement toward sustainable and cruelty-free food production, encouraging manufacturers to explore alternative sources. For instance, ADM has developed a range of soy-based amino acids, which are not only environmentally friendly but also provide a complete amino acid profile, making them suitable for various applications in food and nutrition. The technological advancements in plant-based protein extraction processes are further boosting the availability and affordability of these amino acids, especially in countries like India and China, where vegetarianism is prevalent.
Expansion of Nutraceutical Applications
The nutraceutical industry is emerging as a significant consumer of amino acids in the Asia Pacific region. The increasing adoption of amino acids in functional foods and beverages to address health concerns such as obesity, immunity enhancement, and chronic diseases is a notable trend. For instance, L-Carnitine is gaining popularity for its role in weight management, while L-Glutamine is widely used in recovery-focused dietary supplements. This growing demand for health-oriented food products is creating lucrative opportunities for amino acid manufacturers to collaborate with nutraceutical companies and develop innovative formulations.
Technological Advancements in Production Processes
Advances in biotechnology and fermentation methods are transforming the production landscape of amino acids in the Asia Pacific. The shift from traditional chemical synthesis to microbial fermentation not only improves production efficiency but also addresses environmental concerns by reducing waste and emissions. The adoption of genetically engineered microorganisms for enhanced yield is particularly prominent in leading markets like China and Japan. For instance, CJ CheilJedang has implemented advanced biotechnology to engineer microorganisms for the mass production of amino acids. These innovations enable manufacturers to offer high-quality amino acids at competitive prices, thereby expanding their reach across diverse industries.
Emergence of Southeast Asia as a Growth Hub
Southeast Asia is increasingly emerging as a growth hub within the Asia Pacific commercial amino acids market. For instance, Meihua Holdings Group has also been expanding its international presence, investing in research and development to introduce new amino acid products with enhanced functionalities, thereby meeting the rising demand in Southeast Asia. Countries like Indonesia, Vietnam, and Thailand are experiencing robust industrialization and urbanization, leading to a surge in demand for amino acids across various applications, including animal feed and processed foods. The growing middle-class population in these regions, coupled with rising awareness of nutrition and health benefits, is driving the adoption of amino acid-enriched products. Additionally, government initiatives to promote livestock and agricultural productivity further fuel the demand for amino acids in these markets, providing new growth avenues for regional manufacturers.
Market Challenges Analysis:
Fluctuating Raw Material Costs
The Asia Pacific commercial amino acids market faces challenges stemming from volatile raw material prices. Key inputs, such as corn and sugarcane used in amino acid production, are subject to fluctuations due to climate conditions, global supply chain disruptions, and agricultural policy changes. These price variations increase production costs and impact profit margins, especially for small and medium-sized manufacturers.
Regulatory Complexities
Stringent regulatory frameworks related to food safety, pharmaceutical standards, and environmental compliance present significant hurdles for market players. Meeting these regulations requires substantial investment in quality control and certification processes. Inconsistent regulatory enforcement across different countries within the region further complicates market expansion for global and regional manufacturers.
Competition from Synthetic Alternatives
The market faces competitive pressure from synthetic and chemically derived amino acids, which are often more cost-effective to produce. These alternatives can pose a threat to bio-based amino acids, particularly in price-sensitive markets. Overcoming this challenge requires significant innovation to enhance production efficiency and cost competitiveness.
Infrastructure and Technological Limitations
In emerging economies within the Asia Pacific, inadequate infrastructure and limited access to advanced manufacturing technologies hinder the growth of the amino acids market. Small-scale producers often struggle to adopt modern fermentation techniques, which can restrict their ability to scale production and meet quality standards.
Awareness and Adoption Barriers
In some rural and developing areas, limited awareness of the benefits of amino acids in applications such as animal feed and dietary supplements remains a challenge. This lack of awareness slows market penetration and adoption, particularly among small-scale farmers and local manufacturers.
Market Opportunities:
The Asia Pacific commercial amino acids market presents significant growth opportunities driven by rising consumer awareness of health and wellness, coupled with increasing industrial demand. The growing adoption of amino acids in dietary supplements, functional foods, and beverages offers substantial potential, especially in rapidly urbanizing economies like China and India. The expanding middle-class population and rising disposable incomes have fueled the demand for high-quality protein-rich diets, boosting the use of amino acids in food fortification. Additionally, advancements in biotechnology and fermentation processes are enabling more cost-efficient production methods, opening doors for small and medium-sized enterprises to compete in the market.
The livestock sector offers another major opportunity, as the shift towards intensive farming practices increases the need for amino acid-enriched feed to enhance animal health and productivity. Furthermore, the expanding pharmaceutical and nutraceutical industries are driving demand for amino acids used in biopharmaceuticals, parenteral nutrition, and therapeutic applications. Emerging markets in Southeast Asia, such as Indonesia and Vietnam, present untapped potential due to their growing agricultural and industrial activities. Efforts toward sustainability and bio-based production methods are gaining prominence, appealing to environmentally conscious consumers and investors. This combination of factors underscores the promising growth trajectory of the Asia Pacific commercial amino acids market.
Market Segmentation Analysis:
The Asia Pacific commercial amino acids market is segmented by type, application, end-use, and form, offering a diverse range of growth opportunities across industries.
By Type, key amino acids such as L-Glutamine, L-Leucine, L-Tryptophan, L-Carnitine, and L-Arginine dominate the market. L-Glutamine and L-Leucine are in high demand for their role in muscle recovery and protein synthesis, while L-Carnitine is widely utilized in weight management products.
By Application, the market caters to animal feed, food and beverages, pharmaceuticals, cosmetics, and nutraceuticals. Animal feed represents a significant share, driven by the demand for lysine and methionine to enhance livestock productivity. The food and beverage sector is growing steadily as consumers opt for protein-enriched products, while the pharmaceutical segment benefits from amino acids used in biopharmaceuticals and parenteral nutrition.
By End-Use, segments such as livestock, pet food, human nutrition, personal care, and healthcare highlight the market’s versatility. Livestock dominates due to the increasing adoption of amino acid-based feed supplements, while human nutrition continues to expand with dietary supplements and functional foods.
By Form, amino acids are available as powders, liquids, and granules. Powders hold the largest share due to their versatility and ease of incorporation into formulations, while liquids and granules cater to specific industrial and consumer needs.
Segmentation:
By Type:
- L-Glutamine
- L-Leucine
- L-Tryptophan
- L-Carnitine
- L-Arginine
By Application
- Animal Feed
- FoodBeverage
- Pharmaceuticals
- Cosmetics
- Nutraceuticals
By End-use
- Livestock
- Pet Food
- Human Nutrition
- Personal Care
- Healthcare
By Form
- Powder
- Liquid
- Granules
Regional Analysis:
The Asia Pacific commercial amino acids market demonstrates significant regional diversity, driven by variations in industrial capabilities, economic development, and demand patterns. The market is led by key economies such as China, India, Japan, and South Korea, each contributing uniquely to the overall growth dynamics. Emerging markets in Southeast Asia, including Indonesia, Vietnam, and Thailand, are rapidly gaining traction due to increasing industrialization and rising consumer awareness of health and nutrition.
China holds the largest market share, contributing approximately 40% to the regional market in 2024. The country is a global leader in amino acid production and export, supported by its advanced manufacturing infrastructure and vast raw material availability. Domestic demand remains robust, driven by the growth of the pharmaceutical, animal feed, and food and beverage industries.
India accounts for around 25% of the regional market share and is experiencing rapid growth due to its expanding pharmaceutical and nutraceutical sectors. The country’s livestock industry is also a major consumer of amino acids, particularly lysine and methionine, as farmers adopt high-quality feed additives to improve productivity.
Japan and South Korea jointly contribute nearly 20% of the market, leveraging their advanced pharmaceutical, biotechnology, and food processing industries. These countries demand high-purity amino acids for specialized applications in biopharmaceuticals, parenteral nutrition, and functional foods. Both nations also invest significantly in research and development to improve amino acid production technologies.
Emerging economies in Southeast Asia collectively account for approximately 10–15% of the market. Countries like Indonesia, Vietnam, and Thailand are witnessing strong growth as industrialization drives demand for amino acids in animal feed and processed foods. Rising disposable incomes and growing health consciousness among consumers further fuel the adoption of amino acid-enriched products in these nations.
The diverse economic and industrial landscape of the Asia Pacific region fosters a dynamic market environment. While established economies like China and Japan drive technological advancements and large-scale production, emerging markets provide new growth opportunities. This regional interplay ensures sustained growth of the Asia Pacific commercial amino acids market, supported by expanding applications and increasing investments in biotechnology and production efficiency.
Key Player Analysis:
-
-
- Phibro Animal Health Corporation
- Meihua Holdings Group Co., Ltd
- Kemin Industries, Inc
- Ajinomoto
- RSP amino acids
- Biaffin
- AnaSpec
- ChemPep Inc
- IRIS Biotech
- PepTech Corporation
- Synthetech
- Bluestar Adisseo Co
- CJ CheilJedang Corp
- ADM
- Shandong Sanyuan Biotechnology
- Yantai Tianzheng Biotechnology
- Cargill
- Ajinomoto
- Bifidobacterium
- Sinopec
- Chunming Agricultural
- Zhejiang Medicine
- Kyowa Hakko Bio
- Nutraceutics
- Evonik Industries
-
Competitive Analysis:
The Asia Pacific commercial amino acids market is highly competitive, with a mix of global players and regional manufacturers striving to capture market share. Major companies leverage advanced production technologies, large-scale manufacturing facilities, and extensive distribution networks to maintain dominance. These players focus on innovation, cost optimization, and sustainability to address evolving customer demands. Regional manufacturers play a vital role in catering to domestic markets by offering cost-effective products tailored to local requirements. For example, Meihua Holdings Group Co., Ltd. in China focuses on producing amino acids for the domestic market, ensuring affordability and accessibility. China, as a key production hub, leads in global exports, while India capitalizes on its expanding pharmaceutical and livestock industries. The competition is intensified by the adoption of biotechnological advancements, which enable efficient and environmentally friendly production processes. Strategic partnerships, mergers, and acquisitions are frequently pursued to strengthen market presence and technological capabilities. This competitive landscape, marked by technological innovation and regional diversity, ensures sustained growth and market evolution in the Asia Pacific region.
Recent Developments:
- In September 2024, Ajinomoto Co., Inc. and Danone launched a global strategic partnershipaimed at reducing greenhouse gas emissions from the dairy industry. This collaboration focuses on sustainable practices and innovations to lower the environmental impact of dairy production.
- In August 2024, Evonik Industries materially lifted its outlook for 2024,raising its adjusted EBITDA expectations by €200 million. This adjustment reflects the company's strong performance in the second quarter, driven by good volume development in Specialty Additives and lower production costs.
Market Concentration & Characteristics:
The Asia Pacific commercial amino acids market exhibits a moderately fragmented structure, with several key players and regional manufacturers competing for market share. Prominent companies dominate production and export, leveraging advanced technologies and large-scale manufacturing capacities. The market is characterized by high demand across multiple sectors, including pharmaceuticals, animal feed, and food and beverages, driving diverse product offerings. The competitive landscape is further shaped by continuous innovation in fermentation and biotechnology processes, enabling cost-effective and sustainable amino acid production. Strategic partnerships and investments in research and development are common practices among leading players to meet evolving consumer needs and regulatory standards. Regional diversity also plays a significant role, with countries like China and India leading production, while emerging markets in Southeast Asia contribute to demand growth. This dynamic environment underscores the market’s adaptability and potential for sustained expansion amidst technological advancements and regional economic development.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Application, By End-use and By Form. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing utilization in pharmaceuticals, food and beverages, and animal feed is expected to sustain market growth.
- Innovations in fermentation and biotechnological methods will enhance production efficiency and reduce costs.
- Consumer preference for protein-rich and amino-acid-enriched functional foods is likely to drive demand.
- The use of amino acids in drug development and biopharmaceutical formulations will remain a key growth area.
- The demand for amino acids in animal feed will grow as the livestock sector modernizes and intensifies.
- China and India will maintain dominance due to high production capacities and growing domestic demand.
- Southeast Asian countries, such as Indonesia and Vietnam, will witness significant growth driven by economic development and industrialization.
- Efforts to produce bio-based and eco-friendly amino acids will gain traction in response to environmental concerns.
- Collaborations among manufacturers and end-users will improve market penetration and product innovation.
- Adapting to stringent regulations on food safety and pharmaceutical standards will shape market strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Asia Pacific commercial amino acids market?
What are the major factors driving the market growth?
Which countries dominate the Asia Pacific amino acids market?
What challenges does the Asia Pacific commercial amino acids market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Commercial Amino Acids Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Commercial Amino Acids Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 618.60 million → 2032: USD 1106.18 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Commercial Amino Acids Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Commercial Amino Acids Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Commercial Amino Acids Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Commercial Amino Acids Market Drivers
- 3.3 Asia Pacific Commercial Amino Acids Market Restraints & Challenges
- 3.4 Asia Pacific Commercial Amino Acids Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Commercial Amino Acids Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Commercial Amino Acids Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Commercial Amino Acids category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Commercial Amino Acids Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Commercial Amino Acids Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Commercial Amino Acids market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Commercial Amino Acids Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Commercial Amino Acids Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Commercial Amino Acids Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Commercial Amino Acids (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Commercial Amino Acids Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Commercial Amino Acids Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Commercial Amino Acids Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Commercial Amino Acids Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Commercial Amino Acids Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Commercial Amino Acids Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Commercial Amino Acids Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Commercial Amino Acids Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Commercial Amino Acids Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
