
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automated Truck Loading System Market Size 2024 | USD 3,955.00 million |
| Automated Truck Loading System Market, CAGR | 8.4% |
| Automated Truck Loading System Market Size 2032 | USD 7540.2 million |
Market Overview:
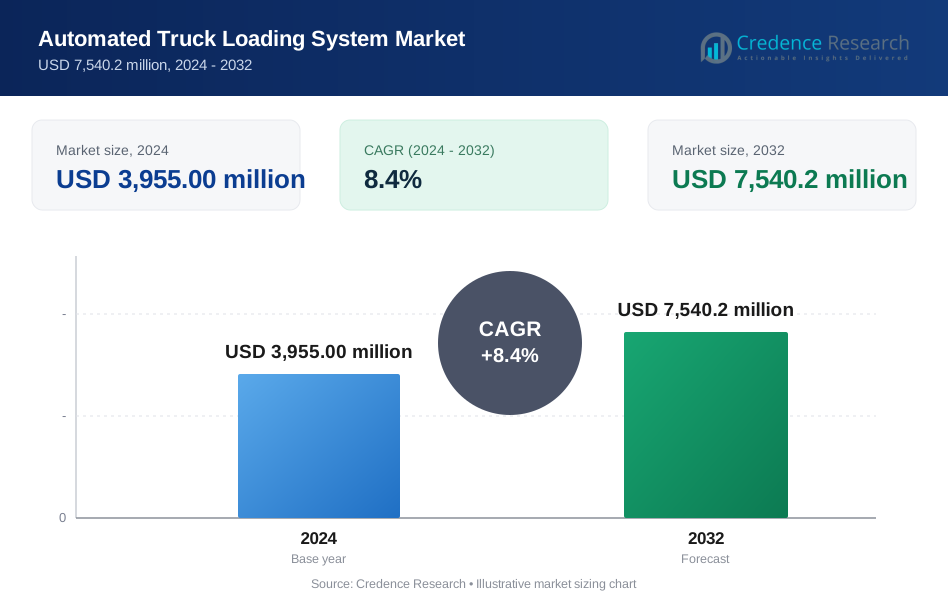
The Automated Truck Loading System Market is projected to grow from USD 3,955.00 million in 2024 to an estimated USD 7540.2 million by 2032, with a compound annual growth rate (CAGR) of 8.4% from 2024 to 2032.
Key drivers are transforming the dynamics of the Automated Truck Loading System Market. The rise of e-commerce and just-in-time delivery models is increasing shipment frequency and pressuring logistics providers to reduce dwell time and improve asset utilization. Labor shortages and rising wage costs across industrialized nations have made manual loading increasingly unsustainable. Companies are turning to automated systems to ensure consistent performance, mitigate operational risks, and improve workforce safety. Technological advancements-particularly in AI-driven sorting, robotics, and IoT-enabled platforms-are further enhancing the functionality and intelligence of these systems. Integration with warehouse management systems (WMS) and transportation management systems (TMS) allows real-time tracking, predictive maintenance, and data-driven optimization. Regulatory factors also play a role; occupational safety standards and environmental policies are prompting organizations to reduce manual handling and lower energy consumption, aligning with broader ESG goals.
Regional trends illustrate varied levels of adoption and growth potential. North America leads the market with a share of approximately 36%, underpinned by strong logistics infrastructure, high labor costs, and rapid digital transformation across warehouses and fulfillment centers. The U.S. is particularly active in deploying large-scale automation in response to labor shortages and rising e-commerce volumes. Europe follows with around 28% market share, supported by regulatory incentives for workplace safety and environmental sustainability. Countries like Germany, the Netherlands, and France are investing heavily in warehouse automation, especially in automotive and retail sectors. Asia-Pacific, currently holding nearly 22% of global market share, is expected to exhibit the fastest growth, fueled by industrial expansion, rising labor costs, and the build-out of smart logistics hubs in China, India, Japan, and Southeast Asia. The region's manufacturing dominance and ongoing infrastructure upgrades create fertile ground for automation vendors. Meanwhile, Latin America and the Middle East & Africa present emerging opportunities, though adoption remains limited by infrastructure variability and budget constraints. However, international investments in port automation and smart city initiatives are beginning to stimulate demand in these regions.
Market Insights:
- The Automated Truck Loading System Market is projected to grow from USD 3,955.00 million in 2024 to USD 7,540.2 million by 2032, registering a strong CAGR of 8.4%.
- E-commerce expansion and just-in-time delivery models are accelerating the demand for automation to reduce truck dwell time and increase throughput.
- Rising labor costs and shortages in developed economies are pushing logistics operators to replace manual loading with automated systems.
- Integration of AI, robotics, and IoT platforms is enhancing system intelligence, enabling predictive maintenance and real-time performance monitoring.
- High capital investment and complex installation requirements remain key adoption barriers, particularly for small and mid-sized enterprises.
- North America holds the largest market share at 36%, followed by Europe at 28%, with Asia-Pacific emerging as the fastest-growing region at 22% market share.
- Lack of infrastructure standardization in developing regions and customization challenges across diverse fleets continue to limit broader deployment.
Market Drivers:
Rising Labor Costs and Workforce Shortages Are Accelerating Automation in Freight Handling:
The global logistics industry faces growing challenges from labor shortages and rising wages, especially in high-volume warehousing and transportation hubs. These pressures are driving businesses to automate critical operations like truck loading, where manual processes can be time-consuming, inconsistent, and hazardous. The Automated Truck Loading System Market is gaining traction as companies seek solutions that reduce reliance on manual labor while improving safety and efficiency. Automated systems ensure consistent performance, lower operational risks, and minimize downtime, offering clear economic advantages. By replacing labor-intensive tasks with mechanical precision, businesses can stabilize costs and improve long-term workforce planning. This shift supports resilience in logistics operations, especially during peak seasons or supply chain disruptions.
- For example, a Dematic deployment at a European distribution hub led to a decrease in manual loading staff from 20 to 12 per shift, while maintaining a consistent loading rate of 120 pallets per hour.
Growth of E-Commerce and Demand for Faster Fulfillment Are Boosting System Adoption:
E-commerce continues to expand rapidly, increasing the volume and frequency of shipments across distribution networks. Consumers and businesses now expect faster delivery times, putting pressure on fulfillment centers and logistics providers to streamline loading and dispatch operations. The Automated Truck Loading System Market is benefiting from this demand for speed, as automated systems reduce truck turnaround time and improve loading accuracy. These systems support 24/7 operation and eliminate bottlenecks associated with manual loading processes. Logistics firms are investing in automation to gain competitive advantage and meet the pace of just-in-time delivery models. The growing scale and complexity of e-commerce supply chains make automation a strategic requirement rather than a discretionary upgrade.
- For example, Swisslog system enables a leading retailer to process 1,800 pallets daily with just eight operators, compared to 18 previously required.
Increasing Emphasis on Workplace Safety and Risk Reduction Supports Automation Investment:
Manual truck loading often exposes workers to repetitive motion injuries, heavy lifting, and accidents from slips or equipment malfunctions. Businesses are under pressure to meet strict occupational safety standards and reduce recordable incidents in logistics environments. The Automated Truck Loading System Market provides a compelling alternative, replacing high-risk tasks with engineered solutions that improve safety outcomes. These systems reduce direct human interaction with moving loads and operate within controlled parameters. Automation helps organizations comply with health and safety regulations while lowering workers' compensation costs and liability. Investing in automated systems is becoming a proactive risk management strategy for logistics and manufacturing companies.
Standardization and Scalability of Modern Logistics Infrastructure Are Enabling System Integration:
Large logistics providers and manufacturers are redesigning warehouses and docks to standardize layouts and processes, allowing seamless integration of automated technologies. The Automated Truck Loading System Market is gaining from these trends, as uniform infrastructure enables faster deployment and easier scalability. Standard dock sizes, trailer dimensions, and load configurations support consistent automated performance across fleets and locations. Companies benefit from economies of scale and simplified maintenance when deploying systems across regional or global networks. It offers modular designs that align with evolving logistics facility standards and layout efficiencies. The move toward uniform infrastructure is expanding the scope and feasibility of full-scale automation in loading operations.
Market Trends:
Adoption of Robotic and Conveyor-Based Loading Technologies Is Replacing Manual Operations:
The logistics industry is moving away from traditional manual loading methods toward robotic and conveyor-based systems that offer speed, consistency, and lower operational risks. These systems handle a wide variety of load types, including pallets, cartons, and irregular items, with minimal human intervention. The Automated Truck Loading System Market is experiencing a shift toward flexible designs that integrate robotic arms, automated guided vehicles (AGVs), and telescopic conveyors. These technologies enhance productivity by reducing truck dwell time and increasing throughput. Warehouses and distribution centers are prioritizing automation to handle higher volumes with fewer errors. The demand for precise, programmable solutions is growing across manufacturing, retail, and third-party logistics sectors.
- For example, Knapp AG 2024 case study highlights a facility where the integration of AGVs and telescopic conveyors reduced truck dwell time from 45 minutes to 15 minutes per load and increased throughput by 33%
Integration with Warehouse Management and IoT Platforms Is Enhancing System Intelligence:
Modern automated loading systems are no longer standalone assets but part of broader digital ecosystems that connect with warehouse management systems (WMS), transportation management systems (TMS), and IoT sensors. This integration allows real-time monitoring, predictive maintenance, and data-driven optimization of loading schedules and vehicle utilization. The Automated Truck Loading System Market is evolving with solutions that communicate seamlessly across logistics operations, enabling synchronized workflows. It supports visibility across the supply chain, which is essential for just-in-time delivery and route planning. Businesses are using analytics from these systems to improve capacity planning and reduce fuel and labor costs. Smart connectivity is becoming a core requirement for buyers evaluating new automation investments.
- For example, Vanderlande’s 2024 annual report documents that their integrated ATLS solutions enabled clients to achieve a 20% reduction in operational costs and a 15% increase in vehicle utilization.
Customization and Modular System Design Are Supporting Diverse Industry Applications:
Demand for customized and modular truck loading solutions is increasing as industries seek automation tailored to their unique operational needs. From automotive to food and beverage sectors, companies require systems that handle specific packaging formats, loading patterns, and environmental conditions. The Automated Truck Loading System Market is responding with modular configurations that allow flexibility in layout, capacity, and automation level. This approach supports scalable deployment and faster return on investment. It also enables gradual upgrades without full system overhauls, which is valuable for facilities with budget or space constraints. Customization enhances market reach by addressing niche requirements in specialized logistics environments.
Focus on Sustainability and Operational Efficiency Is Shaping System Innovation:
Energy efficiency, reduced emissions, and waste minimization are becoming integral to logistics strategies worldwide. Companies are selecting automated loading systems that align with their environmental goals while improving operational output. The Automated Truck Loading System Market is seeing innovation in energy-efficient motors, compact system footprints, and automated load planning to reduce empty space in shipments. These features support both cost savings and sustainability metrics. Automation reduces idling time and fuel consumption by minimizing truck loading delays. Forward-looking companies view system upgrades as a pathway to meet ESG commitments and maintain compliance with evolving environmental regulations.
Market Challenges Analysis:
High Capital Expenditure and Complex Installation Requirements Are Slowing Adoption:
The initial investment required for automated truck loading systems remains a significant barrier for many organizations, especially small and mid-sized enterprises. These systems often demand customized configurations, integration with existing infrastructure, and specialized installation, which increases upfront costs. The Automated Truck Loading System Market faces resistance from buyers weighing return on investment against short-term financial constraints. Installation downtime and operational disruptions during system setup can also deter rapid implementation. Complex site conditions, such as non-standard dock layouts and trailer variability, further complicate deployment. Without strong financial incentives or support, adoption in cost-sensitive industries remains limited.
Lack of Standardization and Flexibility Limits Applicability Across Diverse Logistics Environments:
Many logistics operations lack uniform trailer types, loading dock designs, and cargo handling procedures, making standard automation solutions difficult to apply universally. The Automated Truck Loading System Market must address this challenge by developing more adaptable and configurable technologies. It struggles to scale across fleets or networks with inconsistent infrastructure or mixed load types. Custom engineering increases lead times and implementation costs, deterring operators seeking fast, repeatable automation. Industries with highly variable product dimensions or unpredictable loading volumes also find current systems less suitable. Bridging the gap between customization and standardization is necessary to unlock broader market penetration.
Market Opportunities:
Growth of High-Throughput Logistics and E-Commerce Hubs Is Creating Strong Demand Potential:
The expansion of large-scale distribution centers and fulfillment hubs offers significant growth prospects for automated loading technologies. E-commerce, retail, and 3PL providers are scaling operations to handle rising shipment volumes and compressed delivery timelines. The Automated Truck Loading System Market can capitalize on this trend by delivering high-speed, continuous-flow solutions that reduce vehicle idle time and labor dependency. These systems align with the operational goals of large logistics hubs seeking to maximize dock productivity and shipment accuracy. High-throughput environments require automation to meet service level agreements and manage growing order complexity. Investment in these facilities creates a sustained demand pipeline for advanced loading solutions.
Emerging Markets and Infrastructure Modernization Present Long-Term Expansion Opportunities:
Rapid urbanization and industrial development in emerging economies are driving investment in modern logistics infrastructure. Governments and private operators are developing automated warehouses, smart ports, and multimodal transport hubs to improve supply chain efficiency. The Automated Truck Loading System Market stands to benefit by offering modular, cost-effective solutions tailored to new infrastructure projects. It can address the automation gap in regions where labor challenges, safety regulations, and urban congestion are influencing operational models. Strategic partnerships with local system integrators can further accelerate market entry. These regions offer long-term growth potential as logistics networks evolve to meet international trade and delivery demands.
Market Segmentation Analysis:
By System Type
The Automated Truck Loading System Market includes a wide range of technologies tailored to specific operational needs. Chain, slat, and belt conveyor systems dominate heavy-duty and continuous-load applications. Skate and roller track systems serve low-friction, high-speed environments. Automated Guided Vehicles (AGVs) and robotic arms are gaining adoption for their flexibility and precision in dynamic layouts.
- For instance, Automated Guided Vehicles (AGVs) and robotic arms are gaining adoption for their flexibility and precision in dynamic layouts.
By Truck Type
Modified trucks support seamless automation and are preferred in purpose-built logistics setups. Non-modified trucks require adaptable solutions, expanding market demand for retrofittable systems.
- For instance, Non-modified trucks require adaptable solutions, expanding market demand for retrofittable systems-these accounted for about 40% of new ATLS installations in 2023, as companies seek to upgrade existing fleets without major capital investment.
By Loading Dock Type
Flush and enclosed docks are standard in high-volume operations. Sawtooth docks enhance maneuverability in space-constrained layouts. Climate-controlled and air-conditioned docks support industries like food and pharmaceuticals that require regulated environments.
By Application / Industry
Logistics and warehousing lead adoption, followed by manufacturing, food and beverages, and automotive. Growth is also evident in retail, pharmaceutical, packaging, and airports, where speed and accuracy are essential.
By Technology
Conveyor systems remain the backbone of automation. AGVs and robotic arms are rising due to operational flexibility and real-time responsiveness.
By Installation Type
New installations dominate greenfield projects. Retrofit installations gain traction in legacy facilities seeking modernization.
Segmentation:
By System Type
- Chain Conveyor Systems
- Slat Conveyor Systems
- Belt Conveyor Systems
- Skate Conveyor Systems
- Roller Track Systems
- Automated Guided Vehicles (AGVs)
- Robotic Arms
By Truck Type
- Modified Trucks
- Non-Modified Trucks
By Loading Dock Type
- Flush Dock
- Enclosed Dock
- Sawtooth Dock
- Climate-Controlled Dock
- Air-Conditioned Dock
By Application / Industry
- Logistics and Warehousing
- Manufacturing
- Food and Beverages
- Automotive
- Retail
- Pharmaceutical
- Packaging
- Textile
- Construction
- Airports and Ports
By Technology
- Conveyor Systems
- Automated Guided Vehicles (AGVs)
- Robotic Arms
By Installation Type
- New Installations
- Retrofit Installations
By Solution
- Integrated Systems
- Standalone Systems
By Process
- Loading
- Unloading
By Component
- Sensors
- Controllers
- Software
- Motors
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Maintains Market Leadership Through Technology Integration and High Throughput Operations
North America holds the largest share of the Automated Truck Loading System Market, accounting for approximately 36% of global revenue. The region’s dominance is driven by widespread adoption of advanced logistics technologies, strong e-commerce growth, and investments in high-throughput distribution centers. Key players in the U.S. and Canada are automating warehouse operations to meet consumer demand for fast, reliable delivery. The prevalence of standardized infrastructure and trailer dimensions supports seamless implementation of automated systems. Companies in this region prioritize efficiency, safety, and labor cost reduction, which aligns well with the benefits offered by automated loading technologies. It remains a primary hub for innovation, pilot projects, and early adoption of AI-integrated logistics systems.
Europe Demonstrates Steady Growth Backed by Sustainability and Labor Regulation Pressures
Europe accounts for approximately 28% of the Automated Truck Loading System Market, with growth supported by regulatory pressure, environmental goals, and labor constraints. Countries like Germany, the Netherlands, and France are investing in warehouse automation to improve operational efficiency and reduce manual handling risks. Strong sustainability mandates encourage the adoption of energy-efficient logistics systems, including automated loading technologies. The region also benefits from a high level of industrial standardization, which facilitates the integration of automated systems across varied supply chains. It is experiencing consistent demand from sectors such as automotive, food and beverage, and chemicals, where precision and speed are critical. Continued investment in smart logistics and green infrastructure is expected to support long-term market expansion.
Asia-Pacific Emerges as the Fastest-Growing Region Due to Infrastructure Expansion and Industrialization
Asia-Pacific holds approximately 22% of the global market and is projected to register the highest CAGR over the forecast period. Rapid industrialization, rising labor costs, and large-scale investments in smart warehousing are fueling automation adoption across China, India, Japan, and Southeast Asia. Governments and private enterprises are modernizing logistics infrastructure to support urbanization, e-commerce, and export-driven economies. The Automated Truck Loading System Market in this region is gaining momentum as companies seek scalable, high-capacity systems to handle growing freight volumes. Local manufacturing capabilities and favorable investment policies are helping reduce system costs and accelerate deployment. It is positioned for long-term growth as regional supply chains increase their automation readiness.
Key Player Analysis:
- Dematic Corporation
- BEUMER Group GmbH & Co. KG
- HAVER & BOECKER OHG
- Joloda International Ltd (Joloda Hydraroll Limited)
- Actiw Oy
- Ancra Systems B.V.
- Asbreuk Service B.V.
- Cargo Floor B.V.
- GEBHARDT Fördertechnik GmbH
- Maschinenfabrik Möllers GmbH
- Secon Components S.L.
- VDL Systems B.V.
- Euroimpianti S.p.A.
- C&D Skilled Robotics Inc.
- ATLS Ltd
Competitive Analysis:
The Automated Truck Loading System Market is moderately consolidated, with key players competing on technological innovation, system integration, and global reach. Leading companies such as BEUMER Group, FLSmidth, Ancra Systems, Lodamaster, and Secon Components focus on developing high-speed, energy-efficient systems that meet the evolving needs of logistics, automotive, and manufacturing industries. It is defined by increasing demand for modular, scalable, and customizable solutions, encouraging firms to invest in research and development. Strategic partnerships with warehouse automation providers and system integrators are common, enabling broader deployment and regional expansion. Competition is intensifying as new entrants offer flexible, cost-effective alternatives for mid-sized operations. Companies with strong after-sales support and global service networks maintain a competitive edge by ensuring system uptime and operational continuity. The market favors players that can deliver end-to-end automation solutions aligned with digital transformation trends and sustainability objectives.
Recent Developments:
- In March 2025, Dematic Corporation announced the launch of its next-generation Automated Truck Loading System, featuring advanced AI-driven load optimization and real-time integration with warehouse management systems. This new product aims to reduce truck loading times by up to 40% and enhance operational flexibility for high-volume distribution centers.
Market Concentration & Characteristics:
The Automated Truck Loading System Market shows moderate concentration, with a mix of global leaders and regional players competing in specialized segments. It is characterized by high entry barriers due to the capital-intensive nature of system design, engineering complexity, and integration requirements. The market favors companies with strong automation expertise, proprietary technologies, and established client relationships in logistics and manufacturing. Demand centers around customized, high-throughput solutions that offer operational efficiency, reliability, and compatibility with existing infrastructure. Standardization, energy efficiency, and digital connectivity are key differentiators in purchasing decisions. Long sales cycles, tailored project execution, and the need for technical support define the operational landscape. Vendors capable of offering scalable, service-oriented solutions maintain a strategic advantage.
Report Coverage:
The research report offers an in-depth analysis based on By System Type, By Truck Type, By Loading Dock Type, By Application / Industry, By Technology, By Installation Type, By Solution, By Process, By Component and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will grow steadily as logistics firms prioritize automation to improve throughput and reduce loading time.
- E-commerce expansion will drive adoption in fulfillment centers and high-volume distribution hubs.
- AI and IoT integration will enhance system intelligence, enabling predictive maintenance and real-time optimization.
- Standardization of dock and trailer dimensions will support easier deployment across global logistics networks.
- Energy-efficient systems will gain preference as companies align with sustainability and ESG goals.
- Emerging markets will offer growth opportunities due to infrastructure modernization and rising labor costs.
- Modular and customizable systems will expand market access among mid-sized and decentralized operations.
- Strategic partnerships with warehouse automation providers will support end-to-end logistics integration.
- Regulatory focus on workplace safety will continue to incentivize investment in automated loading technologies.
- Product innovation will accelerate as vendors compete to deliver flexible, high-speed, and compact solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Labor Shortages and Rising Wage Costs
Persistent labor shortages and increasing wage rates in developed economies are making manual truck loading unsustainable, prompting logistics providers to invest in automated systems to ensure consistent performance and reduce operational risks.
E-Commerce Expansion and Just-in-Time Delivery
The rapid growth of e-commerce and the adoption of just-in-time delivery models are increasing shipment frequency and compressing delivery timelines, driving demand for automated truck loading systems to reduce dwell time and maximize throughput.
Integration of AI, Robotics, and IoT
Technological advancements in AI-driven sorting, robotics, and IoT-enabled platforms are enhancing the intelligence and efficiency of automated truck loading systems, enabling real-time tracking, predictive maintenance, and data-driven optimization.
Workplace Safety and Regulatory Compliance
Stricter occupational safety standards and the need to reduce workplace injuries are encouraging organizations to automate high-risk manual loading tasks, supporting compliance and lowering liability and compensation costs.
Standardization and Scalability of Logistics Infrastructure
The trend toward standardized dock layouts and trailer dimensions is making it easier to deploy and scale automated loading systems across large logistics networks, supporting broader adoption and operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automated Truck Loading System Market?
What factors are driving the growth of the Automated Truck Loading System Market?
What are the key segments within the Automated Truck Loading System Market?
Who are the major players in the Automated Truck Loading System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Truck Type
- 1.2.1 Modified Trucks
- 1.2.2 Non-Modified Trucks
- 1.3 By System Type
- 1.3.1 Chain Conveyor Systems
- 1.3.2 Slat Conveyor Systems
- 1.3.3 Belt Conveyor Systems
- 1.3.4 Skate Conveyor Systems
- 1.3.5 Roller Track Systems
- 1.3.6 Automated Guided Vehicles (AGVs)
- 1.3.7 Robotic Arms
- 1.4 By Installation Type
- 1.4.1 New Installations
- 1.4.2 Retrofit Installations
- 1.5 By Application / Industry
- 1.5.1 Logistics and Warehousing
- 1.5.2 Manufacturing
- 1.5.3 Food and Beverages
- 1.5.4 Automotive
- 1.5.5 Retail
- 1.5.6 Pharmaceutical
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,955.00 million → 2032: USD 7,540.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automated Truck Loading System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automated Truck Loading System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automated Truck Loading System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automated Truck Loading System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automated Truck Loading System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automated Truck Loading System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automated Truck Loading System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automated Truck Loading System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,955.00 million → 2032: USD 7,540.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automated Truck Loading System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Truck Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Modified Trucks
- 12.3.7.2 Non-Modified Trucks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By System Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chain Conveyor Systems
- 12.4.7.2 Slat Conveyor Systems
- 12.4.7.3 Belt Conveyor Systems
- 12.4.7.4 Skate Conveyor Systems
- 12.4.7.5 Roller Track Systems
- 12.4.7.6 Automated Guided Vehicles (AGVs)
- 12.4.7.7 Robotic Arms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Installation Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 New Installations
- 12.5.7.2 Retrofit Installations
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application / Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Logistics and Warehousing
- 12.6.7.2 Manufacturing
- 12.6.7.3 Food and Beverages
- 12.6.7.4 Automotive
- 12.6.7.5 Retail
- 12.6.7.6 Pharmaceutical
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automated Truck Loading System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automated Truck Loading System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automated Truck Loading System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automated Truck Loading System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dematic Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BEUMER Group GmbH & Co. KG
- 18.4 Joloda International Ltd (Joloda Hydraroll Limited)
- 18.5 Actiw Oy
- 18.6 Ancra Systems B.V.
- 18.7 Cargo Floor B.V.
- 18.8 GEBHARDT Fördertechnik GmbH
- 18.9 Maschinenfabrik Möllers GmbH
- 18.10 Secon Components S.L.
- 18.11 VDL Systems B.V.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

