
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Chassis Systems Market Size 2024 | USD 89,610 million |
| Automotive Chassis Systems Market, CAGR | 5.09% |
| Automotive Chassis Systems Market Size 2032 | USD 133,305.4 million |
Market Overview:
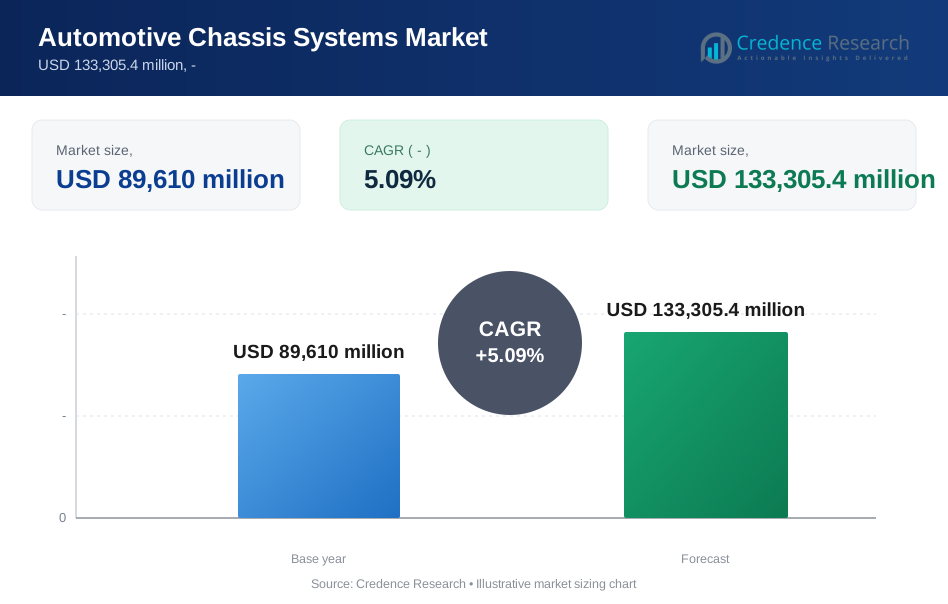
The Automotive Chassis Systems Market is projected to grow significantly, reaching an estimated market size of USD 89,610 million in 2024 and expanding to approximately USD 133,305.4 million by 2032, with a compound annual growth rate (CAGR) of 5.09% over the forecast period. Automotive chassis systems are integral to vehicle structure, providing support, stability, and overall safety. The demand for chassis systems is fueled by the growing automotive industry, the shift towards electric and autonomous vehicles, and the need for lightweight, efficient, and durable solutions that enhance vehicle performance and fuel efficiency.
Key drivers of the automotive chassis systems market include rising demand for lightweight materials and improved fuel efficiency, driven by stringent emission regulations and evolving consumer preferences. The increasing adoption of electric and hybrid vehicles has accelerated the demand for advanced chassis systems to support battery and electric drivetrain configurations. For instance, automakers are incorporating aluminum and composite materials into chassis components to reduce vehicle weight and enhance energy efficiency. Additionally, technological advancements such as adaptive and modular chassis designs enable improved handling, stability, and passenger comfort, further boosting market growth. The rise of autonomous and connected vehicles also emphasizes the need for sophisticated chassis systems capable of integrating sensors and advanced driver assistance systems (ADAS).
Asia-Pacific holds the largest share of the automotive chassis systems market, driven by robust automotive production and demand in countries like China, Japan, and India. The region's dominance is supported by increasing investments in electric mobility and the growing adoption of lightweight chassis solutions. North America follows, with significant demand for advanced chassis technologies driven by consumer preference for high-performance vehicles and stringent regulatory norms for emissions and safety. Europe is a key market, with leading automotive manufacturers emphasizing lightweighting and technological innovations to meet stringent emission standards. Latin America, the Middle East, and Africa are also experiencing steady growth, supported by rising vehicle demand and improving automotive infrastructure.
Market Drivers:
Demand for Lightweight and Fuel-Efficient Vehicles:
Stringent emission regulations and evolving consumer preferences for fuel-efficient vehicles drive the demand for lightweight chassis systems in the automotive industry. Governments worldwide, such as the European Union, have imposed stricter CO₂ emission targets to combat climate change. To meet these requirements, automakers increasingly incorporate lightweight materials like aluminum, magnesium alloys, and composites into chassis components. For example, the U.S. Department of Energy reported that reducing vehicle weight by 10% can improve fuel efficiency by 6-8%. Leading manufacturers have responded by developing chassis solutions that balance strength and weight reduction, supporting both performance and regulatory compliance.
Growth of Electric and Hybrid Vehicles:
The rapid growth of electric and hybrid vehicles has accelerated demand for advanced automotive chassis systems that accommodate new drivetrain configurations. For instance, according to the International Energy Agency (IEA), the global stock of electric vehicles surpassed 10 million units in 2022, marking a significant rise in demand. Electric vehicles (EVs) often require specialized chassis designs to support battery packs, optimize weight distribution, and enhance vehicle stability. For instance, Tesla’s innovative chassis design integrates the battery as part of the vehicle's structure, contributing to improved performance and energy efficiency.
Technological Advancements in Adaptive and Modular Chassis Designs:
Advancements in adaptive and modular chassis systems are transforming vehicle performance, safety, and comfort. Adaptive chassis technologies, such as adjustable suspension systems, enhance ride quality and handling based on driving conditions. A study by the German Federal Ministry of Transport highlighted that vehicles equipped with adaptive suspension systems show up to a 15% reduction in braking distance. Modular chassis platforms enable automakers to streamline production by offering flexible configurations for different vehicle models, reducing costs and enhancing scalability across product lines.
Rise of Autonomous and Connected Vehicles
The development of autonomous and connected vehicles has increased the demand for sophisticated chassis systems capable of integrating sensors and advanced driver assistance systems (ADAS). For instance, The National Highway Traffic Safety Administration (NHTSA) in the U.S. emphasizes the importance of ADAS technologies to reduce accidents and improve safety. Automotive manufacturers are designing chassis systems that accommodate these technologies, ensuring seamless integration and enhanced safety, stability, and responsiveness in autonomous driving scenarios.
Market Trends:
Integration of Advanced Driver-Assistance Systems (ADAS):
Another prominent trend in the automotive chassis systems market is the integration of Advanced Driver-Assistance Systems (ADAS). As the automotive industry moves towards increased automation, chassis systems are being designed to accommodate various ADAS features, such as adaptive cruise control and lane-keeping assistance. According to a report from the Society of Automotive Engineers (SAE), the market for ADAS is expected to grow by 15% annually over the next five years. This increase necessitates the development of more sophisticated chassis systems that can support these advanced technologies, ultimately enhancing vehicle safety and performance.
Emphasis on Electric Vehicle (EV) Platforms:
The rise of electric vehicles (EVs) is significantly influencing the automotive chassis systems market. Automotive manufacturers are increasingly developing dedicated chassis platforms specifically designed for electric drivetrains. For example, Tesla's Model 3 features a platform that integrates the battery pack into the chassis, enhancing rigidity and lowering the center of gravity. The International Energy Agency (IEA) projects that the global EV stock will reach 145 million by 2030, prompting a shift in chassis design to accommodate the unique requirements of electric vehicles, such as weight distribution and battery placement.
Adoption of Modular Chassis Designs:
The trend towards modular chassis designs is gaining traction in the automotive industry, allowing manufacturers to create versatile platforms that can be adapted for various vehicle types. Modular designs enable automakers to streamline production processes, reduce costs, and increase flexibility in responding to market demands. A study by McKinsey & Company suggests that companies adopting modular architectures can reduce development time by up to 30%. This approach not only enhances efficiency in manufacturing but also facilitates the rapid introduction of new models, enabling automakers to stay competitive in a fast-evolving market.
Market Challenges Analysis:
High Costs of Advanced Materials and Technologies:
One of the major restraints in the automotive chassis systems market is the high cost associated with the adoption of advanced materials and technologies. Lightweight materials such as aluminum, magnesium, and carbon composites offer superior performance but come at a premium. This presents a challenge for automakers, particularly when aiming to produce cost-effective vehicles for mass-market consumers. The U.S. Department of Energy has highlighted that reducing vehicle weight with advanced materials can significantly increase manufacturing costs, potentially impacting affordability for end-users. The balance between cost and performance remains a complex issue for manufacturers.
Stringent Regulatory Compliance Requirements:
Automotive chassis systems must adhere to stringent regulatory standards governing vehicle safety, emissions, and crashworthiness. Government bodies such as the European Union (EU) and the National Highway Traffic Safety Administration (NHTSA) in the U.S. enforce rigorous testing and certification protocols. Meeting these regulatory requirements can be complex and time-consuming, adding to development costs and delaying time-to-market for new chassis technologies. Failure to comply can result in hefty fines, recalls, or restrictions on vehicle sales, making compliance a critical consideration for market participants.
Complexity of Electric and Autonomous Vehicle Integration:
The growing adoption of electric and autonomous vehicles poses a challenge for chassis system integration. Electric vehicles (EVs) require chassis systems that can accommodate large battery packs without compromising structural integrity or performance. Autonomous vehicles demand chassis systems that seamlessly integrate advanced sensors, control units, and software for safety and stability. According to the International Energy Agency (IEA), the complexity of integrating these components increases the design and engineering burden on manufacturers. This complexity can hinder rapid adoption, necessitating continuous innovation and adaptation to meet evolving market needs.
Supply Chain Disruptions and Raw Material Shortages:
Global supply chain disruptions and raw material shortages, exacerbated by geopolitical tensions and the COVID-19 pandemic, have impacted the automotive industry, including chassis systems production. Government authorities, such as the World Trade Organization (WTO), have acknowledged these challenges, emphasizing the need for resilient supply chains to mitigate risks and ensure consistent material availability. This disruption poses challenges for maintaining production schedules and cost control.
Market Segmentation Analysis:
By Type
The automotive chassis systems market is segmented by type into ladder frame, monocoque, and modular chassis systems. The monocoque chassis, known for its lightweight and integrated design, dominates the market, offering superior fuel efficiency, stability, and crashworthiness. It is widely used in passenger vehicles, particularly compact and sedan models. Ladder frame chassis, characterized by their strength and durability, are predominantly used in heavy-duty vehicles such as trucks and SUVs. The modular chassis design, gaining traction due to its flexibility and scalability, allows manufacturers to streamline production for multiple vehicle platforms, enhancing efficiency.
By Technology
By technology, the market is divided into traditional chassis systems and advanced technologies, including adaptive and smart chassis systems. Adaptive chassis technologies, such as adjustable suspension and electronic stability control, improve ride comfort, safety, and vehicle handling. Smart chassis systems integrate sensors and electronic controls, enabling real-time adjustments to driving conditions and enhancing autonomous driving capabilities. As automotive technology evolves, the demand for intelligent and responsive chassis systems continues to rise.
By End User
The market segmentation by end user includes passenger vehicles, commercial vehicles, and electric vehicles (EVs). Passenger vehicles account for a significant share, driven by high consumer demand for comfort, safety, and performance. Commercial vehicles, including trucks and buses, rely on robust chassis systems for heavy-duty operations. Electric vehicles are emerging as a key segment, with growing demand for specialized chassis systems optimized for battery integration, weight distribution, and structural integrity, supporting the electrification trend in the automotive industry.
Segmentation:
By Component- Suspension Ball Joints
- Cross Axis Joints
- Tie Rods
- Stabilizer Links
- Control Arms
- Knuckles and Hubs
- Backbone Chassis
- Ladder Chassis
- Monocoque Chassis
- Modular Chassis
- Others
- Aluminum Alloy
- Mild Steel
- High Speed Steel
- Others (Carbon Fibre Composite, Etc.)
- BEV
- PHEV
- HEV
- Passenger Cars
-
- Hatchback
- Sedan
- Utility Vehicles
-
- Light Commercial Vehicles
- Heavy Duty Trucks
- Buses and Coaches
By Regions
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the automotive chassis systems market, accounting for approximately 40% of global demand. The region’s dominance is driven by robust automotive production, high vehicle sales, and increasing demand for electric and hybrid vehicles. China is a key player, with its strong automotive manufacturing base and government initiatives promoting electric mobility, including subsidies and infrastructure development. Japan, known for its technological innovation, emphasizes lightweighting and advanced chassis designs to enhance vehicle performance and fuel efficiency. India’s growing automotive market, supported by increasing disposable incomes and infrastructure development, also contributes significantly to regional growth. Asia-Pacific’s focus on adopting lightweight and advanced chassis systems to meet emission standards further supports market expansion.
North America
North America accounts for approximately 25% of the market share, driven by high demand for advanced and performance-oriented vehicles. The United States is a major contributor, supported by significant investments in automotive innovation, the presence of leading automotive manufacturers, and stringent emission regulations imposed by agencies like the Environmental Protection Agency (EPA). The region is witnessing increased adoption of lightweight materials and smart chassis technologies, driven by consumer preference for fuel-efficient and safe vehicles. Canada is also experiencing steady growth, supported by strong demand for trucks, SUVs, and electric vehicles.
Europe
Europe represents around 20% of the global automotive chassis systems market. The region’s growth is fueled by stringent regulatory standards on emissions and safety, compelling manufacturers to adopt advanced chassis systems and lightweight materials. Countries such as Germany, the United Kingdom, and France are key contributors, known for their focus on innovation, luxury vehicles, and electric mobility. Germany, in particular, leads in chassis system development, supported by a strong automotive industry and significant investments in R&D. The European Union’s push for carbon neutrality and clean transportation further accelerates demand for advanced chassis technologies in the region.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively hold around 15% of the market share. In Latin America, countries like Brazil and Mexico are investing in automotive manufacturing and infrastructure development, driving demand for robust chassis systems. The Middle East and Africa region is experiencing steady growth, supported by rising vehicle demand, infrastructure projects, and government initiatives promoting economic diversification. While these regions face challenges such as economic volatility and supply chain constraints, increasing investments in automotive infrastructure present opportunities for market expansion. The focus on durable and adaptable chassis systems in harsh operating conditions further supports growth across these regions.
Key Player Analysis:
- ZF Friedrichshafen AG
- Magna International Inc.
- Continental AG
- Aisin Seiki Co., Ltd.
- American Axle & Manufacturing Holdings, Inc.
- Hyundai Mobis Co., Ltd.
- Schaeffler AG
- KLT Automotive & Tubular Products Ltd.
- F-TECH INC.
- CIE Automotive
Competitive Analysis:
The automotive chassis systems market is characterized by intense competition among established global players and regional specialists. Major companies such as ZF Friedrichshafen AG, Magna International Inc., and Continental AG lead the market, leveraging their strong product portfolios, technological expertise, and extensive global networks. These market leaders focus on innovation in lightweight materials, modular chassis designs, and smart technologies to meet the evolving needs of the automotive industry, including electric and autonomous vehicles. Emerging players and specialized firms emphasize niche solutions, cost efficiency, and customization to differentiate themselves in a dynamic market landscape. The competitive dynamics are shaped by the push for improved vehicle safety, enhanced fuel efficiency, and compliance with stringent regulatory standards. Strategic partnerships, mergers and acquisitions, and continuous R&D investments are key strategies adopted by market participants to strengthen their positions and address the growing demand for advanced, adaptive chassis solutions.
Recent Developments:
- In 2023, ZF Friedrichshafen AG unveiled its new modular chassis system designed for electric vehicles, which focuses on scalability and adaptability for various vehicle types. This innovative platform integrates advanced safety features and supports both conventional and electrified drivetrains, emphasizing ZF's commitment to enhancing vehicle performance and sustainability. Additionally, the company announced a partnership with a leading automaker to develop an advanced driver-assistance system (ADAS) that leverages artificial intelligence for improved vehicle safety and efficiency.
- In 2022, Magna International Inc. launched its next-generation electric vehicle (EV) chassis designed to accommodate various battery configurations. This modular platform allows manufacturers to easily modify the chassis for different EV models, significantly reducing development time and costs. Furthermore, in early 2023, Magna introduced a lightweight chassis solution that utilizes advanced materials and manufacturing techniques, resulting in a 20% weight reduction compared to traditional chassis systems, thereby enhancing the overall efficiency of EVs and hybrid vehicles.
- Continental AG made strides in 2023 by introducing a new smart chassis technology that integrates advanced sensors and control systems to improve vehicle handling and safety. This system is designed to enhance driver assistance features, offering real-time data analysis to optimize performance in various driving conditions. Additionally, Continental announced a partnership with a major automotive manufacturer to co-develop a comprehensive chassis control system that integrates both hardware and software solutions, reinforcing the importance of digitalization in modern automotive systems.
- In 2024, Aisin Seiki Co., Ltd. launched a cutting-edge chassis system that prioritizes integration with hybrid and electric vehicle architectures. This system features an adaptive suspension technology that adjusts to driving conditions in real-time, significantly improving ride comfort and handling. Aisin also announced its commitment to sustainability by integrating recycled materials into its chassis designs, aligning with the industry's shift towards more environmentally friendly practices.
Market Concentration & Characteristics:
The automotive chassis systems market exhibits a moderate to high degree of market concentration, characterized by the dominance of established global players alongside a range of regional and niche competitors. Leading companies such as ZF Friedrichshafen AG, Magna International Inc., and Continental AG drive innovation through extensive R&D, focusing on lightweight materials, modular designs, and smart chassis technologies to meet evolving automotive trends, including electric and autonomous vehicles. These companies maintain strong competitive positions through strategic partnerships, diversified product offerings, and global distribution networks. Regional players and specialized firms compete by offering tailored solutions, cost-effective manufacturing, and technological advancements, particularly in emerging markets. The market is shaped by stringent regulatory standards on emissions and safety, driving the adoption of advanced, adaptable, and compliant chassis systems. The ongoing focus on vehicle performance, efficiency, and safety ensures continuous innovation and dynamic competition across the market.
Report Coverage:
The research report offers an in-depth analysis based on Component, Chassis Type, Chassis Material, and Vehicle Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The automotive chassis systems market is expected to see significant growth due to increasing demand for lightweight materials that enhance fuel efficiency and vehicle performance.
- Electric and hybrid vehicle adoption will drive the development of specialized chassis systems designed to support battery integration and optimize weight distribution.
- Advancements in adaptive and smart chassis technologies will improve safety, handling, and ride comfort through real-time data-driven adjustments.
- The shift towards autonomous and connected vehicles will create demand for chassis systems that can seamlessly integrate sensors and advanced driver assistance systems (ADAS).
- Regulatory pressures related to emissions reduction and vehicle safety standards will push manufacturers to innovate and adopt compliant chassis designs.
- Modular chassis platforms will gain traction, enabling manufacturers to offer flexible configurations across multiple vehicle models and reduce production costs.
- Increasing investments in R&D by major players will lead to innovations in materials, structures, and chassis technologies, fostering market competitiveness.
- The Asia-Pacific region is expected to lead market growth, supported by strong automotive production, rising EV adoption, and favorable government policies.
- Collaborative efforts between automakers, suppliers, and technology firms will drive innovation and accelerate the deployment of next-generation chassis systems.
- Growing consumer demand for performance-oriented and technologically advanced vehicles will shape the development of high-end chassis solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Automotive Chassis Systems Market?
What factors are driving the growth of the Automotive Chassis Systems Market?
What are some challenges faced by the Automotive Chassis Systems Market?
Which segment is leading the market share?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Chassis Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Chassis Systems Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 89,610 million → forecast year: USD 133,305.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Chassis Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Chassis Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Chassis Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Chassis Systems Market Drivers
- 3.3 Automotive Chassis Systems Market Restraints & Challenges
- 3.4 Automotive Chassis Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Chassis Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Chassis Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Chassis Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Chassis Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Chassis Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Chassis Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Chassis Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Chassis Systems Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Chassis Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Chassis Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Chassis Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Chassis Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Chassis Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Chassis Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Chassis Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Chassis Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Chassis Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Chassis Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Chassis Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
