
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Motors Market Size 2024 | USD41,650 million |
| Automotive Motors Market, CAGR | 3.88% |
| Automotive Motors Market Size 2032 | USD56,477 million |
Market Overview
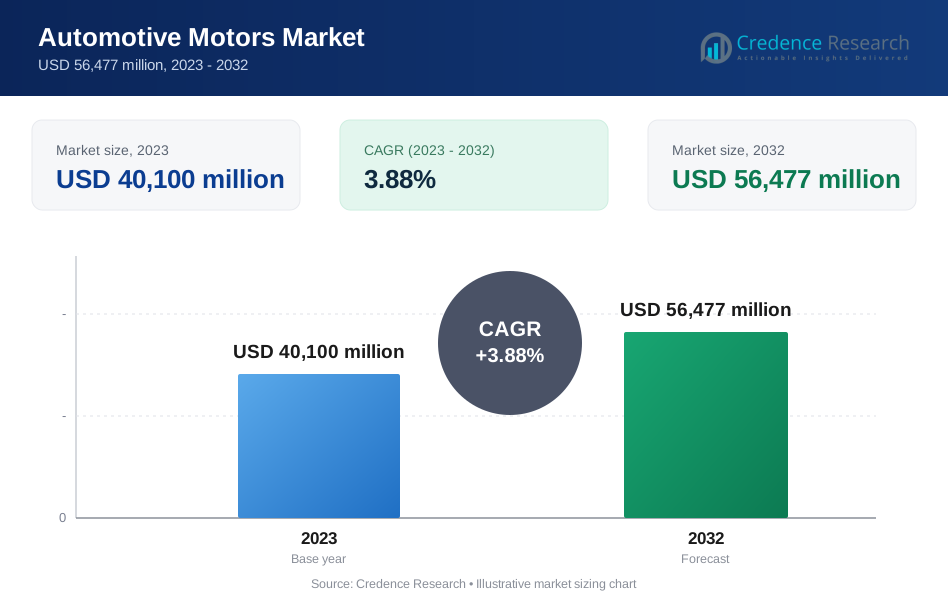
The Global Automotive Motors Market is projected to grow from USD41,650 million in 2024 to an estimated USD56,477 million based on 2032, with a compound annual growth rate (CAGR) of 3.88% from 2025 to 2032.
Key drivers fueling the automotive motors market include the electrification of vehicle systems and the shift toward electric mobility. Trends such as increased use of brushless DC motors, enhanced focus on energy efficiency, and the adoption of advanced driver-assistance systems (ADAS) are shaping market demand. Automakers are increasingly integrating multiple motor-driven functionalities to reduce mechanical linkages, enhance vehicle performance, and optimize fuel consumption. Additionally, regulatory mandates focused on fuel economy and emission reductions continue to influence motor development strategies.
Geographically, Asia-Pacific leads the automotive motors market due to high vehicle production volumes in China, Japan, South Korea, and India. The region benefits from a robust automotive manufacturing ecosystem and rising consumer demand for passenger and electric vehicles. North America and Europe also hold substantial shares, driven by technological advancements and premium vehicle offerings. Key players in the market include Robert Bosch GmbH, Denso Corporation, Continental AG, Nidec Corporation, and Mitsubishi Electric Corporation.
Market Insights
- The Global Automotive Motors Market is projected to grow from USD41,650 million in 2024 to USD56,477 million by 2032, registering a CAGR of 3.88% from 2025 to 2032.
- Rising adoption of electric vehicles and demand for advanced comfort, safety, and infotainment systems are fueling the need for high-efficiency automotive motors.
- Increasing integration of ADAS features and regulatory focus on emission reduction are accelerating innovation in compact, energy-efficient motor technologies.
- Fluctuating raw material costs and supply chain disruptions are impacting production efficiency and profitability across the motor manufacturing sector.
- Design complexity, limited thermal management solutions, and challenges in integrating multiple systems into compact spaces hinder motor performance optimization.
- Asia-Pacific leads the global market with a 46.2% share in 2024, supported by high vehicle production in China, India, Japan, and South Korea.
- North America and Europe follow due to their strong EV adoption, premium vehicle demand, and continuous investment in smart automotive technologies.
Market Drivers
Surging Demand for Electric and Hybrid Vehicles Accelerates Motor Deployment
The Global Automotive Motors Market is witnessing strong momentum due to the growing adoption of electric and hybrid vehicles. Automakers are investing heavily in electrification to meet emission regulations and sustainability goals. Electric vehicles require multiple motors for propulsion, steering, HVAC systems, and battery cooling. This widespread motor usage drives higher demand across vehicle segments. Consumers are shifting preferences toward cleaner mobility, pushing OEMs to redesign vehicles with motor-driven components. Governments worldwide are offering incentives for EV adoption, which further stimulates the need for compact and efficient automotive motors. The rising share of electric and hybrid vehicles is set to remain a dominant factor driving long-term market expansion.
- For instance, China registered 8.1 million new electric vehicle sales in 2023
Increasing Integration of Comfort and Convenience Features in Passenger Cars
The integration of comfort-oriented features such as power-adjustable seats, automatic windows, sunroofs, and electronically controlled mirrors boosts motor demand in passenger vehicles. Consumers expect higher levels of convenience and in-vehicle automation, which necessitates multiple small electric motors across different car systems. The Global Automotive Motors Market benefits directly from this shift toward enhanced user experience in both premium and mid-range vehicles. OEMs are focusing on differentiating offerings by embedding smart motor-controlled features. The expanding demand for personalized driving comfort encourages suppliers to innovate in motor design and control systems. This trend aligns with rising income levels and changing lifestyle preferences in emerging economies.
- For instance, the U.S. market has seen a surge in demand for steering-mounted controls, heads-up displays, and advanced infotainment systems, contributing to increased motor adoption.
Regulatory Push for Fuel Efficiency and Emission Reduction Strengthens Motor Innovation
Stringent regulations related to vehicle emissions and fuel efficiency influence the adoption of energy-efficient motors. Governments are enforcing performance standards that require automakers to reduce mechanical loads and improve energy use. The Global Automotive Motors Market responds to these challenges through lightweight, high-torque, and digitally controlled motors. Motor technologies that reduce overall power consumption and support hybrid powertrains gain preference. Regulatory frameworks across Europe, the U.S., and parts of Asia are driving investments in sustainable automotive technologies. Compliance with these norms makes motor innovation essential for maintaining competitive positioning.
Advancements in Motor Control Electronics and Smart Integration Support Growth
Technological progress in motor control electronics allows better synchronization, higher efficiency, and integration with vehicle software platforms. The Global Automotive Motors Market is evolving with the adoption of brushless motors, sensorless control, and intelligent feedback systems. These technologies improve reliability and system diagnostics while reducing maintenance costs. Vehicle manufacturers are adopting smart integration strategies to simplify wiring architecture and centralize control systems. This transformation enables more precise motor operations and seamless communication with electronic control units (ECUs). Innovations in control systems continue to unlock new applications and operational efficiencies across vehicle platforms.
Market Trends
Shift Toward Brushless DC Motors Enhances Performance and Reliability
The Global Automotive Motors Market is experiencing a shift from conventional brushed motors to brushless DC motors (BLDC). This transition stems from the growing need for higher efficiency, longer lifespan, and reduced maintenance in vehicle systems. BLDC motors offer better thermal performance, less friction, and quieter operation, which improve the overall driving experience. Automakers are increasingly using them in electric power steering, HVAC systems, and powertrain components. Their compact size and high torque-to-weight ratio make them suitable for space-constrained automotive applications. It supports the industry's push for compact and efficient vehicle designs.
- For instance, Nidec Corporation has developed high-efficiency BLDC motors for electric power steering and HVAC applications, improving vehicle performance.
Integration of Advanced Driver Assistance Systems Drives Motor Demand
The rapid integration of advanced driver assistance systems (ADAS) is contributing to the rising number of motors used per vehicle. Features such as adaptive cruise control, lane-keeping assistance, and automated parking require precise motion control. The Global Automotive Motors Market benefits from this trend, with motors being embedded into sensors, actuators, and control modules. Vehicle automation relies heavily on motor responsiveness and accuracy. It is creating demand for high-precision, sensor-integrated motors that meet stringent safety and performance standards. The expansion of ADAS applications across vehicle segments continues to elevate motor innovation.
- For instance, Tesla’s camera-based ADAS system optimizes motor responsiveness for adaptive cruise control and emergency braking.
Growth in Vehicle Electrification Expands Applications of Auxiliary Motors
The expansion of electrification in powertrains is increasing the use of auxiliary motors for secondary systems such as battery cooling, regenerative braking, and electric air conditioning compressors. The Global Automotive Motors Market is adapting to meet these functional requirements through specialized motor designs. It is leading to the development of application-specific motors optimized for energy use and performance. These auxiliary systems play a crucial role in enhancing EV efficiency and passenger comfort. Automakers are focusing on balancing energy distribution across systems, further supporting motor-based innovations. The rising complexity of EV architectures adds to the demand for reliable and efficie motors.
Digitalization and Smart Motor Control Shape Future Developments
Smart motor control technologies are gaining traction, allowing real-time diagnostics, energy monitoring, and predictive maintenance. The Global Automotive Motors Market is evolving with digital solutions that optimize motor performance across various vehicle subsystems. Manufacturers are embedding motors with sensors and communication protocols to enable seamless integration with vehicle control units. It improves responsiveness and supports over-the-air updates for software-defined functions. The growing role of digital platforms in automotive electronics drives collaboration between motor suppliers and software developers. These advancements are shaping a more connected and intelligent automotive ecosystem.
Market Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions Impact Production Costs
Fluctuating prices of raw materials such as copper, aluminum, and rare earth metals pose a major challenge for the Global Automotive Motors Market. These materials are essential for motor winding and magnet systems, making their cost directly impact overall motor pricing. Supply chain disruptions caused by geopolitical tensions, trade restrictions, and natural disasters increase procurement risks for manufacturers. It leads to delayed production schedules and higher operational expenses. The lack of stable supply agreements with raw material vendors further complicates inventory management. These factors restrict price competitiveness and profit margins across the value chain.
- For instance, automakers sourcing rare earth magnets for electric motors have faced supply shortages, leading to production delays and increased costs.
Design Complexity and Heat Management Constraints Limit Motor Efficiency
The rising demand for compact and multi-functional motors brings engineering challenges related to design complexity and thermal management. The Global Automotive Motors Market must address space limitations within vehicle systems while maintaining high torque and speed requirements. It increases the difficulty of optimizing motor layouts and controlling heat dissipation. Overheating can reduce motor efficiency, shorten lifespan, and degrade performance. Integration with electronic control units demands greater precision and protection from electromagnetic interference. These technical constraints slow down the deployment of advanced motors in high-performance applications.
Market Opportunities
Rising Electric Vehicle Adoption Opens New Avenues for Motor Innovation
The growing global shift toward electric vehicles creates significant opportunities for the Global Automotive Motors Market. EVs require a higher number of motors per vehicle to operate propulsion, cooling systems, battery management, and auxiliary functions. This surge in motor applications allows manufacturers to diversify their product lines and develop specialized solutions. It encourages innovation in energy-efficient, compact, and high-performance motors tailored for electric mobility. Governments supporting EV infrastructure and emission-free transportation drive further demand. The transition to EVs offers long-term growth potential across both developed and emerging markets.
Expansion of Smart and Autonomous Vehicle Technologies Increases Motor Integration
The rapid development of smart and autonomous vehicles creates demand for intelligent, sensor-integrated motors. The Global Automotive Motors Market benefits from new applications in ADAS, automated control systems, and vehicle-to-everything (V2X) technologies. These vehicles rely on precision motor functions for real-time responsiveness and system coordination. It opens opportunities for partnerships between motor manufacturers and electronics or software firms. Advanced features such as remote diagnostics and predictive maintenance expand the role of motors beyond mechanical support. This trend aligns with the future of mobility, where integrated, adaptive systems define vehicle performance.
Market Segmentation Analysis
By Motor Type
The Global Automotive Motors Market, based on motor type, includes brushed DC motors, brushless DC motors, stepper motors, and traction motors. Brushless DC motors are gaining strong traction due to their higher efficiency, reduced maintenance, and longer operational life compared to brushed variants. Stepper motors are widely used in precision control applications such as air conditioning systems and instrument clusters. Traction motors are critical in electric vehicles, driving demand in line with the electrification trend. Brushed DC motors still serve in cost-sensitive applications but face declining preference.
By Sales Channel
Based on the sales channel, the market divides into OEM and aftermarket. OEMs dominate the market due to direct integration of motors during vehicle assembly. OEM preference for quality assurance and custom specifications strengthens this segment’s position. The aftermarket segment sees steady growth due to the need for replacement and upgrades in older vehicles. It provides opportunities for specialized and high-performance motor solutions.
By Application
Based on application, the market segments into safety, comfort, and performance. Comfort dominates due to widespread use of motors in power windows, seats, HVAC systems, and infotainment. The safety segment includes applications in ABS and advanced driver-assistance systems, while performance focuses on propulsion and transmission. It reflects growing integration of smart and energy-efficient motors across all functional areas.
By Vehicle Type
By vehicle type, the Global Automotive Motors Market is categorized into passenger cars and commercial vehicles. Passenger cars lead in volume due to high production and greater demand for comfort and infotainment features. Commercial vehicles focus on durable, high-torque motors for performance and utility functions. It reflects different motor usage priorities across vehicle categories.
Segments
Based on Motor Type
- Brushed DC Motor
- Brushless DC Motor
- Stepper Motor
- Traction Motor
Based on Sales Channel
- OEM
- Aftermarket
Based on Application
- Safety
- Comfort
- Performance
Based on Vehicle Type
- Passenger Cars
- Commercial Vehicles
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia Pacific Automotive Motors Market
Asia Pacific holds the largest share of the Global Automotive Motors Market, accounting for 46.2% in 2024. The region benefits from high vehicle production volumes in China, Japan, South Korea, and India. Strong demand for passenger vehicles, expanding electric vehicle adoption, and rising income levels drive market growth. Major OEMs and component suppliers maintain extensive manufacturing operations across the region. It encourages local sourcing and cost-efficient production of automotive motors. Government incentives supporting EV adoption further enhance regional demand.
North America Automotive Motors Market
North America captures 23.5% of the Global Automotive Motors Market in 2024, driven by high adoption of advanced vehicle technologies. The U.S. leads the region with strong demand for electric and hybrid vehicles, supported by regulatory frameworks and consumer preferences. Automakers focus on integrating high-performance motors in ADAS, infotainment, and energy-efficient systems. It creates opportunities for innovation in motor control and reliability. The presence of established automotive and technology companies fosters development of smart motor solutions.
Europe Automotive Motors Market
Europe holds 19.3% of the market share in 2024, with strong regulatory support for electrification and sustainability. The region leads in the adoption of emission-free mobility, encouraging use of electric motors in both primary and auxiliary applications. Germany, France, and the UK dominate production and consumption. The Global Automotive Motors Market in Europe gains from strict CO₂ emission targets and public investment in EV infrastructure. It influences OEMs to adopt energy-efficient, compact, and durable motors across vehicle platforms.
Latin America Automotive Motors Market
Latin America holds a modest share of 5.1% in 2024, but shows potential for future growth. Increasing urbanization, rising vehicle ownership, and growing demand for compact vehicles fuel motor usage. Brazil and Mexico lead regional production and sales. The market focuses on cost-effective motors for comfort and safety applications. It sees gradual adoption of motors in hybrid and electric vehicle segments as regulatory support improves.
Middle East and Africa Automotive Motors Market
The Middle East and Africa account for 3.2% of the Global Automotive Motors Market in 2024. The market benefits from rising investments in infrastructure, logistics, and industrial transportation. Growing demand for commercial vehicles increases the need for performance-driven motors. Regional governments support automotive assembly initiatives and EV introduction in urban areas. It creates moderate opportunities for OEMs and motor suppliers to expand in underserved markets.
Key players
- Siemens
- Robert Bosch GmbH
- Continental AG
- DENSO CORPORATION
- Mitsubishi Electric Corporation
- MAHLE GmbH
- NIDEC CORPORATION
- Johnson Electric Holdings Limited
- BorgWarner Inc.
- Valeo S.A.
Competitive Analysis
The Global Automotive Motors Market features intense competition with companies focusing on technological innovation, efficiency, and customization. Key players such as Robert Bosch GmbH, DENSO CORPORATION, and Mitsubishi Electric Corporation lead through diversified product portfolios and global manufacturing networks. These firms invest in advanced motor technologies like brushless DC motors and integrated control systems. It allows them to meet the rising demand for electric mobility and ADAS functionalities. Siemens and NIDEC CORPORATION leverage their expertise in industrial automation to strengthen their automotive segment. Emerging trends in electrification and digitalization push companies to form strategic partnerships and expand R\&D capabilities. Market leaders focus on enhancing durability, performance, and energy savings to retain competitive advantage.
Recent Developments
- In May 2025, Siemens participated in the Automotive Testing Expo 2025 in Stuttgart, showcasing its innovations in automotive manufacturing and testing.
- In April 2025, Continental AG announced its Automotive group sector would be renamed Aumovio, emphasizing its pivot toward software-defined vehicles.
- In May 2025, Mitsubishi Electric Corporation confirmed plans to launch a battery-electric vehicle in North America by summer 2026.
- In May 2025, NIDEC CORPORATION broke ground on a third building at its Neemrana factory to produce automotive motor systems.
- In May 2025, Valeo S.A. announced it was ahead of schedule on a €150 million cost-reduction initiative.
Market Concentration and Characteristics
The Global Automotive Motors Market shows moderate to high market concentration, with a few major players holding significant shares due to their global presence, technological expertise, and large-scale production capabilities. It features a mix of established multinational companies and regional manufacturers catering to OEM and aftermarket needs. The market is characterized by continuous innovation, high entry barriers, and a strong emphasis on energy efficiency, miniaturization, and integration with vehicle electronics. Product differentiation through motor performance, durability, and smart control features defines competitive positioning. Demand for customization and compliance with emission and efficiency standards further shapes product development. The market relies heavily on long-term supplier-OEM partnerships and rigorous quality certifications.
Report Coverage
The research report offers an in-depth analysis based on Motor Type, Sales Channel, Application, Vehicle Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Electric vehicle adoption will increase the demand for traction motors and auxiliary systems, encouraging advanced motor designs tailored for energy efficiency and compact performance.
- The market will favor brushless DC motors due to their superior efficiency, durability, and ability to integrate with smart electronic systems for seamless control.
- Smart motor technologies with real-time monitoring and diagnostics will support predictive maintenance and vehicle system optimization across future automotive platforms.
- Wider integration of ADAS and autonomous driving features will raise the demand for high-precision, sensor-integrated motors capable of ensuring accurate and reliable functionality.
- Motor manufacturers will focus on close collaboration with OEMs to develop custom motor solutions aligned with evolving platform-specific design and performance requirements.
- Countries in Southeast Asia, Latin America, and the Middle East will present strong growth potential as they expand automotive production and EV infrastructure.
- Manufacturers will prioritize sustainable materials, energy-efficient designs, and recyclable motor components to align with global carbon neutrality and green mobility goals.
- Digitalization of vehicle systems will lead to tighter motor integration with control units, enabling coordinated system responses and software upgrades over the air.
- Aging vehicle fleets in mature markets will create steady demand for high-quality, energy-efficient motors in the aftermarket segment focused on repair and upgrades.
- Thermal control will remain a key focus, with manufacturers developing new cooling technologies to support high-performance motor use in EVs and hybrid systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Electrification of Vehicles
The shift toward electric and hybrid vehicles is driving demand for automotive motors, as these vehicles require multiple motors for propulsion, auxiliary systems, and advanced features. Automakers are investing in electrification to meet emission regulations and consumer demand for cleaner mobility.
Integration of Comfort and Convenience Features
Increasing consumer expectations for comfort-oriented features such as power-adjustable seats, automatic windows, and advanced infotainment systems is boosting the use of motors in passenger vehicles. This trend is especially prominent in both premium and mid-range segments.
Regulatory Push for Fuel Efficiency and Emission Reduction
Stringent global regulations on vehicle emissions and fuel economy are compelling automakers to adopt energy-efficient, lightweight, and digitally controlled motors. Compliance with these standards is accelerating innovation and adoption of advanced motor technologies.
Growth of Advanced Driver Assistance Systems (ADAS)
The proliferation of ADAS features like adaptive cruise control, lane-keeping assistance, and automated parking is increasing the number of motors required per vehicle. These systems rely on precise, sensor-integrated motors for accurate and reliable operation.
Technological Advancements in Motor Control
Progress in motor control electronics, including the adoption of brushless DC motors and smart integration with vehicle ECUs, is enhancing motor efficiency, reliability, and diagnostics. This enables automakers to optimize vehicle performance and reduce maintenance costs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Automotive Motors Market in 2023, and what is its forecast for 2032?
What is driving the growth of the automotive motors market?
Which region dominates the automotive motors market and why?
Who are the key players in the Global Automotive Motors Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Motor Type
- 1.2.1 Brushed DC Motor
- 1.2.2 Brushless DC Motor
- 1.2.3 Stepper Motor
- 1.2.4 Traction Motor
- 1.3 By Application
- 1.3.1 Safety
- 1.3.2 Comfort
- 1.3.3 Performance
- 1.4 By Vehicle Type
- 1.4.1 Passenger Cars
- 1.4.2 Commercial Vehicles
- 1.5 By Sales Channel
- 1.5.1 OEM
- 1.5.2 Aftermarket
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 40,100 million → 2032: USD 56,477 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Motors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Motors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Motors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Motors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Motors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Motors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Motors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Motors Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 40,100 million → 2032: USD 56,477 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Motors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Motor Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Brushed DC Motor
- 12.3.7.2 Brushless DC Motor
- 12.3.7.3 Stepper Motor
- 12.3.7.4 Traction Motor
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Safety
- 12.4.7.2 Comfort
- 12.4.7.3 Performance
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Cars
- 12.5.7.2 Commercial Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 OEM
- 12.6.7.2 Aftermarket
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Motors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Motors Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Motors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Motors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Robert Bosch GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DENSO CORPORATION
- 18.4 Continental AG
- 18.5 NIDEC CORPORATION
- 18.6 Mitsubishi Electric Corporation
- 18.7 Siemens
- 18.8 MAHLE GmbH
- 18.9 Johnson Electric Holdings Limited
- 18.10 BorgWarner Inc.
- 18.11 Valeo S.A.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

