
Market Overview
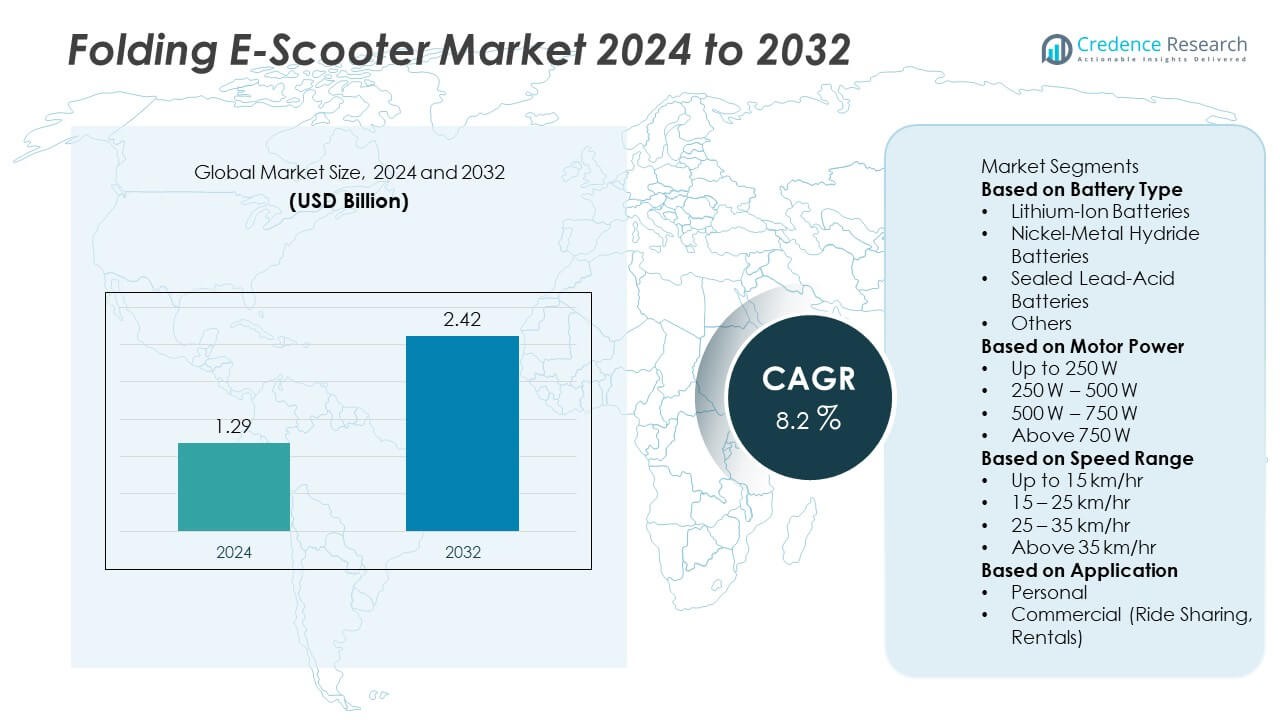
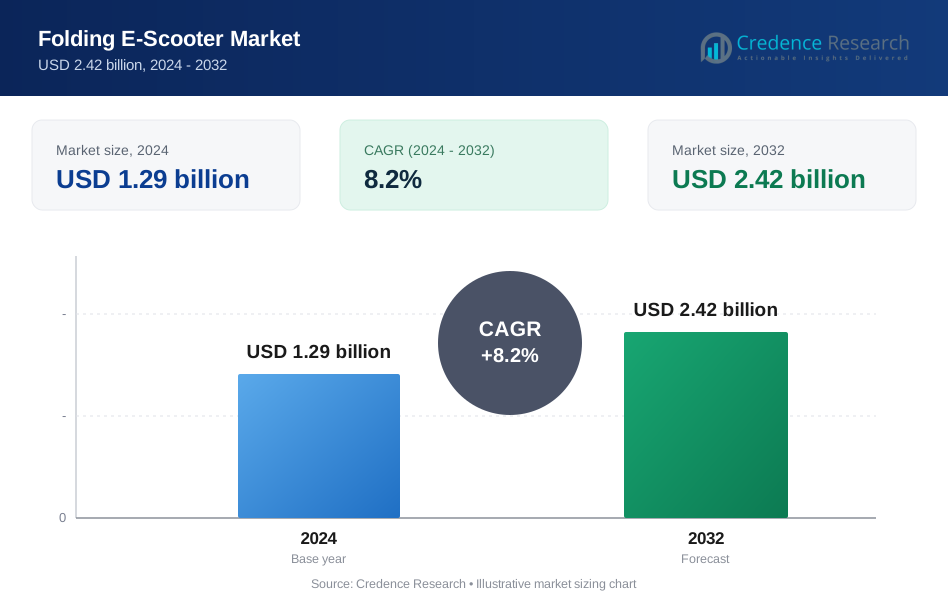
The Folding E-Scooter Market was valued at USD 1.29 billion in 2024 and is projected to reach USD 2.42 billion by 2032, growing at a CAGR of 8.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Folding E-Scooter Market Size 2024 | USD 1.29 Billion |
| Folding E-Scooter Market, CAGR | 8.2% |
| Folding E-Scooter Market Size 2032 | USD 2.42 Billion |
The Folding E-Scooter Market is led by major companies including Xiaomi Corporation, Segway-Ninebot, Razor USA LLC, Turboant, Glion, Megawheels, Swagtron, Unagi Scooters, GoTrax, and EcoReco. These manufacturers emphasize innovation in design, lightweight materials, and improved battery performance to meet rising urban commuting needs. North America dominated the market with a 35% share in 2024, supported by strong adoption of personal mobility devices and growing e-scooter sharing networks. Europe followed with 32%, driven by sustainability policies and widespread acceptance of electric transportation. Asia-Pacific held 27% share, emerging as the fastest-growing region due to large-scale production and government incentives for green mobility adoption.
Market Insights
- The Folding E-Scooter Market was valued at USD 1.29 billion in 2024 and is projected to reach USD 2.42 billion by 2032, growing at a CAGR of 8.2%.
- Rising demand for compact, eco-friendly urban mobility solutions and increasing government incentives for electric vehicles are driving market growth.
- Integration of smart connectivity features, lightweight materials, and improved lithium-ion battery technology are key trends shaping product innovation.
- Leading players such as Xiaomi Corporation, Segway-Ninebot, Razor USA LLC, and Unagi Scooters focus on expanding product portfolios and forming partnerships with shared mobility platforms.
- North America led the market with 35% share in 2024, followed by Europe with 32% and Asia-Pacific with 27%, while the 250 W–500 W motor power segment dominated with 47% share, driven by its efficiency and suitability for daily urban commuting.
Market Segmentation Analysis:
By Battery Type
Lithium-ion batteries dominated the Folding E-Scooter Market with a 63% share in 2024. Their higher energy density, faster charging, and longer lifespan make them ideal for lightweight and portable scooters. Growing demand for sustainable and high-performance battery solutions supports their use in both personal and commercial scooters. Nickel-metal hydride and sealed lead-acid batteries remain secondary due to higher weight and lower efficiency. Advancements in lithium battery technology and declining production costs continue to drive this segment’s dominance in electric mobility applications.
- For instance, Segway-Ninebot's Max G2 model employed a 551 Wh battery that recharges in approximately 6 hours with its built-in charger. An external 5A fast charger, which is sold separately, can halve the charge time. The scooter's battery management system is designed to promote longevity.
By Motor Power
The 250 W – 500 W motor power segment held a 47% share in 2024, making it the leading category in the Folding E-Scooter Market. These models balance performance, portability, and affordability, ideal for urban commuters seeking efficient short-distance travel. They offer moderate speed, good climbing ability, and energy efficiency suited for daily use. Models above 500 W are gaining traction in premium and shared mobility segments, while low-power models serve entry-level users. Increasing urban traffic congestion and the need for compact transport drive this segment’s expansion.
- For instance, the Unagi Model One Voyager uses dual 250 W motors delivering a combined peak output of 1,000 W and a top speed of 32 km/h (20 mph). The TurboAnt M10 Lite employs a 350 W brushless motor enabling ascent on 15% gradients and reaching a top speed of 26 km/h (16 mph).
By Speed Range
The 25–35 km/hr speed range dominated the market with a 42% share in 2024. This category offers the best balance between performance, safety, and battery efficiency for city commutes. It meets regulatory limits in most urban regions while offering sufficient speed for short and mid-distance travel. The segment benefits from strong consumer preference for reliable and comfortable rides. Higher-speed models above 35 km/hr are seeing gradual adoption in specialized commercial and recreational uses, supported by improvements in motor control, braking systems, and safety standards.
Key Growth Drivers
Rising Urban Commuting Demand
The growing need for compact, eco-friendly, and cost-efficient commuting solutions is a major driver of the Folding E-Scooter Market. Urban populations are increasingly adopting foldable electric scooters for short-distance travel due to traffic congestion and limited parking space. Their portability and low maintenance make them ideal for city environments. Governments promoting electric mobility and shared transportation systems further strengthen market adoption across developed and emerging regions.
- For instance, GoTrax introduced its Apex LE model weighing 14.5 kg, enabling daily commuters to integrate micro-mobility with public transport systems efficiently.
Technological Advancements in Battery and Motor Systems
Continuous improvements in lithium-ion battery efficiency and compact motor design are boosting the performance of folding e-scooters. These advancements have increased mileage, reduced charging time, and enhanced scooter durability. Lightweight frames and regenerative braking systems also contribute to longer operating life and better user convenience. Manufacturers are investing in integrating smart connectivity features such as Bluetooth tracking and app-based controls to attract tech-savvy urban consumers.
- For instance, Xiaomi's Electric Scooter 5 Max uses a regenerative braking system and features a motor with a maximum power output of 1,000 W. While the system can be configured through the Xiaomi Home app to recover energy, the manufacturer does not specify an exact percentage of energy recovery.
Environmental Regulations and Green Mobility Initiatives
Global efforts to reduce carbon emissions are fueling demand for electric two-wheelers, including folding e-scooters. Governments are introducing incentives, tax benefits, and infrastructure support for electric mobility adoption. Urban policies favoring low-emission zones and sustainable transportation have increased consumer preference for e-scooters over conventional fuel vehicles. The rising environmental awareness among younger commuters continues to accelerate the market’s shift toward clean, efficient urban transport options.
Key Trends & Opportunities
Integration of Smart and Connected Technologies
Smart folding e-scooters equipped with IoT features, GPS tracking, and mobile app connectivity are gaining traction. These systems allow users to monitor performance metrics, battery status, and navigation in real time. Fleet operators and shared mobility providers are leveraging these technologies for remote management and maintenance. The growing demand for connected mobility and digital convenience presents a major opportunity for manufacturers to enhance customer experience and brand differentiation.
- For instance, Segway-Ninebot integrates its proprietary Segway App with Bluetooth, enabling features such as speed tracking, riding statistics, and diagnostics. Unagi Scooters utilize OTA (Over-the-Air) firmware updates through its Unagi App, providing remote software updates and fault detection.
Growth of Shared Mobility and Last-Mile Delivery Applications
The increasing adoption of folding e-scooters in ride-sharing and last-mile delivery services is creating new market opportunities. Their portability and low operating cost make them ideal for dense urban environments. Delivery companies and micromobility startups are deploying compact e-scooter fleets to enhance service efficiency and reduce emissions. The trend is further supported by partnerships between e-scooter manufacturers and mobility platforms seeking sustainable last-mile transport solutions.
- For instance, Lime operates over 200,000 e-scooters across 280 cities worldwide, supported by its fleet of swappable-battery models developed with Segway. The company reported completing 500 million rides using its shared micromobility fleet, reducing CO₂ emissions by approximately 90,000 metric tons through electric last-mile operations.
Key Challenges
Safety and Durability Concerns
Safety issues related to battery overheating, braking performance, and limited visibility remain key concerns for users. Frequent wear and tear in folding mechanisms and tires also affect long-term reliability. Manufacturers are working to enhance structural integrity and incorporate advanced safety systems. However, lack of standardized safety regulations across regions continues to challenge market growth and consumer confidence.
Infrastructure Limitations and Charging Availability
Limited charging infrastructure in urban areas hinders large-scale adoption of folding e-scooters. Many cities still lack dedicated parking and charging stations, reducing convenience for commuters. Inconsistent electricity access in developing regions further restricts growth. Expanding fast-charging networks and integrating portable battery systems are critical to overcoming this challenge and ensuring sustained market development.
Regional Analysis
North America
North America held the largest share of 35% in the Folding E-Scooter Market in 2024. The region’s growth is driven by increasing adoption of eco-friendly personal mobility solutions and supportive government policies promoting electric vehicles. The United States dominates due to strong urban commuting demand, high purchasing power, and expanding e-scooter rental networks. Leading manufacturers are introducing lightweight and connected models tailored for city travel. Investments in charging infrastructure and sustainable transport initiatives are further strengthening market penetration across metropolitan areas such as New York, Los Angeles, and Toronto.
Europe
Europe accounted for 32% of the Folding E-Scooter Market in 2024, supported by stringent emission regulations and widespread electric mobility adoption. Countries such as Germany, France, and the United Kingdom are leading users, driven by dense urban populations and strong environmental awareness. The presence of advanced manufacturing facilities and smart city projects boosts the deployment of folding e-scooters in shared mobility programs. Government subsidies for low-emission vehicles and dedicated cycling lanes continue to encourage e-scooter commuting, positioning Europe as a major hub for sustainable urban transportation development.
Asia-Pacific
Asia-Pacific captured a 27% share of the global Folding E-Scooter Market in 2024 and is projected to grow fastest through 2032. Rapid urbanization, rising fuel costs, and increasing demand for affordable mobility solutions drive adoption. China, Japan, and India dominate regional growth, supported by large-scale production, growing e-commerce penetration, and government incentives for electric vehicles. Expanding urban infrastructure and the availability of compact, low-cost models strengthen market expansion. Asia-Pacific’s dominance in battery manufacturing and component supply also provides a competitive edge in global production and distribution.
Latin America
Latin America accounted for a 4% share of the Folding E-Scooter Market in 2024. The region’s growth is driven by increasing urban congestion and rising awareness of eco-friendly mobility options. Brazil and Mexico lead demand due to expanding ride-sharing services and growing interest in sustainable personal transport. However, limited charging infrastructure and high import costs hinder large-scale adoption. Governments are promoting electric vehicle incentives to reduce emissions, which is expected to enhance market opportunities in the coming years, especially within urban centers with improving road networks.
Middle East & Africa
The Middle East & Africa held a 2% share of the Folding E-Scooter Market in 2024. Growth is primarily fueled by smart city projects and government-led sustainability initiatives in GCC countries. The UAE and Saudi Arabia are early adopters, with strong investments in urban mobility innovation and e-transport infrastructure. Rising youth populations and growing awareness of personal electric vehicles are supporting gradual adoption. In Africa, market penetration remains low due to affordability and infrastructure limitations, but increasing interest in micro-mobility and renewable transport solutions is driving early development.
Market Segmentations:
By Battery Type
- Lithium-Ion Batteries
- Nickel-Metal Hydride Batteries
- Sealed Lead-Acid Batteries
- Others
By Motor Power
- Up to 250 W
- 250 W – 500 W
- 500 W – 750 W
- Above 750 W
By Speed Range
- Up to 15 km/hr
- 15 – 25 km/hr
- 25 – 35 km/hr
- Above 35 km/hr
By Application
- Personal
- Commercial (Ride Sharing, Rentals)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Folding E-Scooter Market features key players such as Xiaomi Corporation, Segway-Ninebot, Razor USA LLC, Turboant, Glion, Megawheels, Swagtron, Unagi Scooters, GoTrax, and EcoReco. These companies focus on innovation, lightweight design, and enhanced battery efficiency to meet rising urban mobility demands. Market leaders are investing in advanced lithium-ion batteries, smart connectivity, and foldable frame technologies to improve portability and performance. Strategic partnerships with ride-sharing platforms and retail distributors help expand market reach globally. North American and European manufacturers emphasize quality and compliance with safety standards, while Asia-Pacific players dominate production through cost-effective manufacturing. Continuous R&D in compact motor systems, IoT integration, and sustainability-driven materials is shaping competition and driving differentiation in this rapidly evolving micro-mobility market.
Key Player Analysis
- Xiaomi Corporation
- Segway-Ninebot
- Razor USA LLC
- Turboant
- Glion
- Megawheels
- Swagtron
- Unagi Scooters
- GoTrax
- EcoReco
Recent Developments
- In March 2025, Segway-Ninebot launched the Ninebot Max G3 featuring RideyLONG battery optimization and enhanced safety locking. The model’s presale began on March 6 with full release on March 25, marking its latest folding-scooter upgrade.
- In January 2024, Cambridge-based Riley Scooter launched a new RS3 e-scooter in the United States. It is considered the world’s first-ever compact and foldable e-scooter.
- In October 2023, Unagi Scooter opened its first flagship showroom in New York City, offering customers a hands-on experience with its folding e-scooter models and emphasizing its direct-to-consumer retail strategy.
Report Coverage
The research report offers an in-depth analysis based on Battery Type, Motor Power, Speed Range, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for folding e-scooters will continue to rise with growing urbanization and traffic congestion.
- Advancements in battery technology will enhance range, charging speed, and overall performance.
- Lightweight and compact designs will gain preference among daily commuters.
- Integration of IoT and smart connectivity will improve safety and user convenience.
- Shared mobility and rental services will expand adoption in major cities.
- Asia-Pacific will experience the fastest growth due to mass production and affordability.
- Governments will strengthen regulations supporting electric mobility and green transport.
- Manufacturers will focus on sustainability through recyclable materials and energy-efficient systems.
- Online retail and direct-to-consumer sales channels will boost market accessibility.
- Continuous innovation in foldable frame technology and motor efficiency will drive competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Folding E-Scooter Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Folding E-Scooter Market projected to grow between 2025 and 2032?
Which Folding E-Scooter Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Folding E-Scooter Market?
Who are the leading companies in the Folding E-Scooter Market?
Which region commanded the largest share of the Folding E-Scooter Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.29 billion → 2032: USD 2.42 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Folding E-Scooter Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Folding E-Scooter Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Folding E-Scooter Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Folding E-Scooter Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Folding E-Scooter Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Folding E-Scooter Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Folding E-Scooter Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Folding E-Scooter Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.29 billion → 2032: USD 2.42 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Folding E-Scooter Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Folding E-Scooter Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Folding E-Scooter Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Folding E-Scooter Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

