
Market Overview
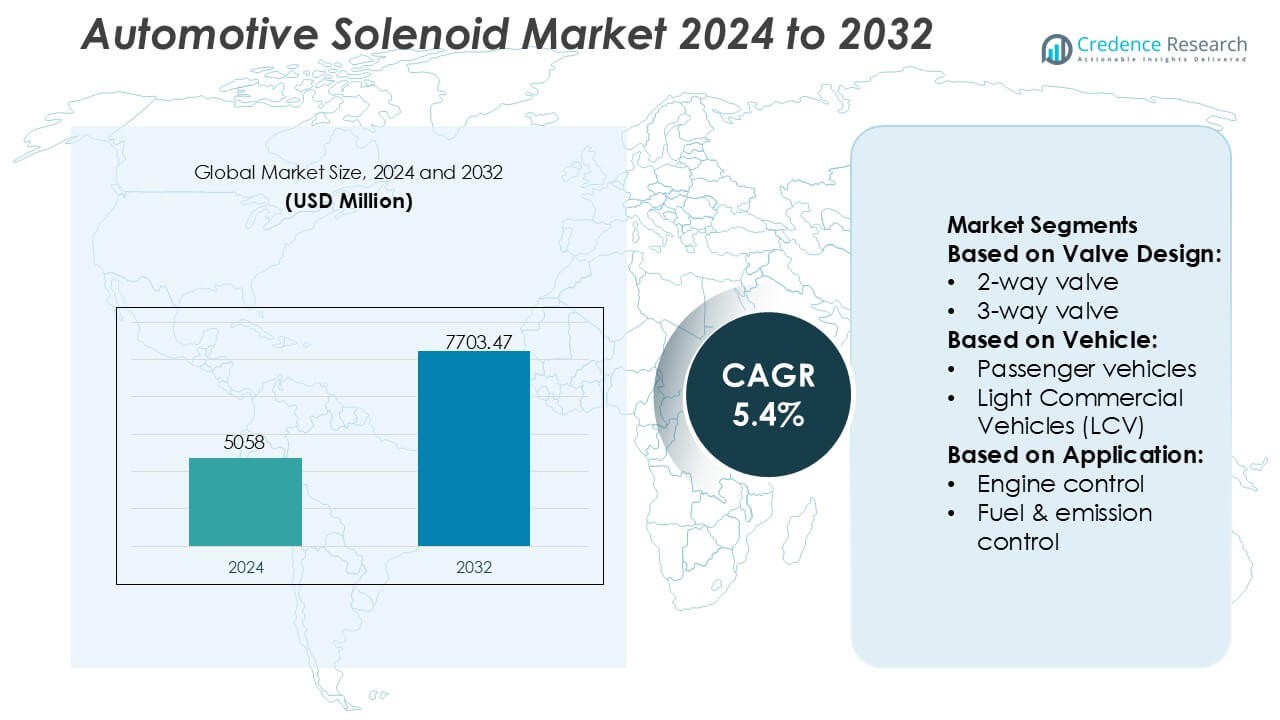
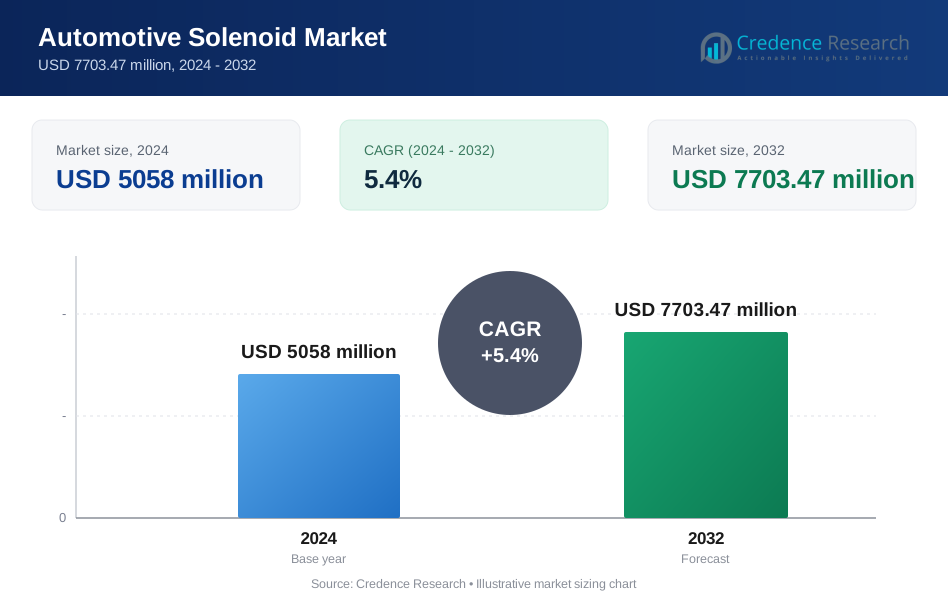
Automotive Solenoid Market size was valued USD 5058 million in 2024 and is anticipated to reach USD 7703.47 million by 2032, at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Solenoid Market Size 2024 | USD 5058 Million |
| Automotive Solenoid Market, CAGR | 5.4% |
| Automotive Solenoid Market Size 2032 | USD 7703.47 Million |
The Automotive Solenoid Market is shaped by a strong mix of global manufacturers whose portfolios span engine control, transmission actuation, braking systems, and EV thermal management solutions. Key participants include Curtiss Wright Corporation, Danfoss Industries Ltd, SMC Corporation, AirTAC International Group, Emerson Electric Co., Anshan Solenoid Valve Co. Ltd, IMI Process Automation, CEME Group, Parker Hannifin Corporation, and KANEKO SANGYO Co. Ltd, each advancing miniaturized, high-efficiency solenoid technologies to meet evolving OEM requirements. North America leads the market with an exact 34% share, supported by rapid adoption of advanced powertrains, strong regulatory compliance needs, and expanding electrification initiatives across regional automotive platforms.
Market Insights
- The Automotive Solenoid Market reached USD 5058 million in 2024 and is projected to hit USD 7703.47 million by 2032 at a 5.4% CAGR, reflecting stable demand across engine control, transmission, braking, and EV thermal systems.
- Rising adoption of electrified and turbocharged powertrains drives the need for high-efficiency solenoids that support precise fluid, pressure, and airflow control in modern vehicle architectures.
- Advancements in miniaturization, low-power actuation, and durable coil materials strengthen competition as leading players enhance portfolios for EV, hybrid, and automated transmission applications.
- Cost pressures, high-temperature performance limitations, and complex OEM validation requirements restrain growth, especially for solenoids operating in extreme under-hood environments.
- North America leads with a 34% share, while 2-way valves hold the dominant segment share at 41%, supported by widespread deployment in fuel, emission, and cooling circuits across passenger and light commercial vehicle platforms.
Market Segmentation Analysis:
By Valve Design
The 2-way valve segment dominates the Automotive Solenoid Market with an exact 41% share, supported by its broad compatibility with fuel circuits, engine actuators, and thermal management systems. Automakers prefer 2-way designs due to their compact geometry, fast switching response, and lower integration cost across combustion and hybrid platforms. Demand rises further as OEMs expand electronically controlled fuel delivery and cooling subsystems, increasing the need for high-cycle solenoids with enhanced sealing performance. Growing electrification also reinforces adoption as battery and inverter cooling loops rely on efficient 2-way flow-control architectures.
- For instance, Curtiss-Wright Corporation’s solenoids and solenoid valves are designed for high-reliability, safety-critical applications within the aerospace, defense, and nuclear power industries. These components are engineered and tested to meet stringent military and industry standards, such as those within MIL-STD-810, and can be built for continuous duty in demanding environments like engine bleed air systems or nuclear plant safety applications.
By Vehicle
Passenger vehicles lead the market with an exact 57% share, driven by high production volumes and rapid incorporation of electronically controlled subsystems. Solenoid demand strengthens as passenger models integrate advanced emission systems, active safety technologies, automated transmissions, and intelligent HVAC controls. Expanding hybrid and mild-hybrid variants further increase solenoid density per vehicle, particularly for turbo bypass control, vacuum switching, and thermal regulation components. Continuous platform upgrades across compact, mid-size, and premium segments reinforce the dominance of passenger vehicles in both OEM and replacement channels.
- For instance, Danfoss produces high-performance solenoid valves for industrial refrigeration applications, such as the EVR series (e.g., EVR 15, 032L1228), which utilize robust designs to achieve a maximum working pressure of approximately 45.2 bar (4,520 kPa).
By Application
Engine control emerges as the dominant application with an exact 33% share, propelled by stringent global emission regulations and OEM focus on combustion optimization. Modern engines rely extensively on solenoids for variable valve timing, turbocharger wastegate actuation, exhaust gas recirculation, and precise fuel modulation. Increasing adoption of downsized turbocharged engines intensifies the requirement for high-temperature, fast-response solenoids capable of supporting real-time calibration strategies. Even with rising electrification, hybrid powertrains preserve engine-control solenoid demand due to continued reliance on complex thermal, air-management, and fuel-handling subsystems.
Key Growth Drivers
- Rising Electrification and Advanced Powertrain Adoption
Electrification accelerates solenoid demand as hybrid and plug-in hybrid vehicles incorporate multiple electronically controlled actuators for thermal regulation, battery cooling, brake vacuum creation, and transmission modulation. Automakers integrate high-cycle solenoids to support downsized turbocharged engines that require precise boost control and exhaust management. Regulatory pressure to reduce emissions strengthens the use of solenoids in EGR, purge, and valve-timing systems. As electrified platforms expand globally, OEMs rely on compact, energy-efficient solenoids that maintain reliability under high temperature and vibration stress.
- For instance, SMC Corporation produces highly efficient direct-acting 5-port solenoid valves, such as those in the JSY series, which achieve low coil power consumption of approximately 0.4 watts (standard type, with an optional power-saving circuit reaching 0.1 W) and are rated for a long service life exceeding 55 million switching cycles (B10 reliability data).
- Increasing Integration of Safety and Comfort Systems
Modern vehicles incorporate advanced braking, ADAS, and comfort-enhancing systems that depend on rapid-response solenoid valves. Electronic stability control, anti-lock braking, seat-adjustment assemblies, active suspension, and automated door-locking systems use solenoids to ensure accurate and repeatable actuation. Growth in premium and mid-segment passenger vehicles expands solenoid content per vehicle across body control, HVAC regulation, and driver-assist modules. As OEMs enhance automation and comfort features, solenoids play a critical role in enabling precise mechanical responses within compact electronic architectures.
- For instance, AirTAC International Group specifies that its 4V and 2V electropneumatic solenoid valve platforms deliver response times as low as 50 milliseconds, operate reliably across pressure ranges from 150 kPa to 800 kPa, and achieve endurance ratings above 50 million switching cycles.
- Expansion of Emission-Control and Fuel-Efficiency Technologies
Global emissions regulations encourage automakers to adopt solenoid-based solutions that optimize combustion and reduce evaporative losses. Engine management systems increasingly use solenoids in variable valve timing, fuel vapor purge, NOx reduction, and exhaust after-treatment circuits. These components deliver fast modulation, tight sealing, and high thermal endurance, supporting OEM efforts to meet regulatory thresholds. Increasing adoption of GDI and turbocharged engines drives further usage in wastegate actuators, pressure-control circuits, and air path management, reinforcing solenoids as critical components in efficiency-focused powertrain designs.
Key Trends & Opportunities
- Growing Adoption of Smart and Miniaturized Solenoid Technologies
Manufacturers develop compact, lightweight solenoids with high force density, extended cycle life, and lower power consumption to meet the evolving needs of electrified vehicles. Integration of embedded sensors enables real-time diagnostics, predictive maintenance, and improved control accuracy. Miniaturization supports dense packaging in EV battery systems, ADAS modules, and multi-function mechatronic units. As OEMs shift toward space-efficient E/E architectures, suppliers offering intelligent solenoid solutions gain opportunities in next-generation thermal, braking, and transmission platforms.
- For instance, Emerson's high-performance ASCO solenoid valves are engineered across various product series to meet specific industrial needs. The ASCO Series 188 miniature solenoid valves achieve power consumption as low as 1.0 to 1.3 watts for DC versions and offer response times under 10 milliseconds for pneumatic applications.
- Expansion of EV Thermal Management and Battery Safety Applications
Electric vehicles require complex thermal and coolant distribution loops, creating new opportunities for solenoids that manage refrigerant flow, coolant routing, and heat-pump switching. High-pressure, fast-switching solenoids support battery protection systems, inverter cooling, and motor thermal regulation. Growth in fast-charging infrastructure further increases demand for precision flow-control components in battery conditioning systems. As EV manufacturers enhance thermal efficiency and safety, specialized solenoids designed for non-flammable fluids, high-voltage isolation, and silent operation gain strategic relevance.
- For instance, IMI Process Automation’s ICO3S Direct-Acting Hydraulic Solenoid Poppet Valve is rated for continuous operation at pressures up to 350 bar (or up to 700 bar in other variants) with a typical flow capacity of approximately 6 to 14 liters per minute (L/min), and supports multiple coil voltage options tailored to specific control environments.
- Increasing Use of Modular and Multi-Function Actuation Units
Automakers transition toward modular actuation systems that combine multiple solenoid functions into unified units to improve reliability, reduce weight, and simplify assembly. Multi-function solenoid blocks support modern transmission control systems, brake boosters, and body electronics. Suppliers offering integrated modules gain competitive advantage as OEMs adopt zonal architectures and reduce wiring complexity. This shift also drives opportunities for solenoids with improved electromagnetic efficiency, adaptive force profiles, and compatibility with software-based calibration strategies.
Key Challenges
- Performance Degradation Under High Thermal and Mechanical Stress
Automotive solenoids operate in demanding environments where extreme heat, vibration, fuel exposure, and pressure fluctuations can impair functionality. High-temperature zones in turbocharged engines accelerate material fatigue and shorten service life. Ensuring coil insulation stability, magnetic strength retention, and sealing integrity becomes a major engineering challenge. OEMs face increasing responsibility to validate long-cycle durability while maintaining compact designs. These constraints pressure manufacturers to adopt advanced alloys, high-temperature polymers, and enhanced electromagnetic designs to ensure reliability.
- Cost Pressures Amid Rapid Technological Advancements
Automakers seek high-performance solenoids while maintaining strict cost targets, creating tension between material quality and affordability. Electrification and ADAS expansion increase solenoid count per vehicle, amplifying procurement cost sensitivity. Suppliers must invest in precision manufacturing, automation, and advanced testing while keeping unit costs low to stay competitive. Fluctuating raw material prices and global supply chain disruptions add further constraints. This challenge intensifies as OEMs demand smarter, smaller, and more efficient solenoids without significant cost escalation.
Regional Analysis
North America
North America leads the Automotive Solenoid Market with an exact 34% share, supported by strong adoption of advanced powertrain systems, stringent emission regulations, and high penetration of safety-enhanced vehicle platforms. OEMs in the region integrate solenoids extensively in engine optimization, EV thermal management, and ADAS-related actuation systems. The presence of established automotive manufacturers and technology suppliers accelerates product innovation, particularly in high-temperature, fast-response solenoid designs. Increasing EV production in the United States and Canada enhances demand for compact, energy-efficient solenoids used in battery cooling, braking, and electronic transmission modules.
Europe
Europe holds an exact 29% share, driven by its strong regulatory framework for emission control and rapid expansion of electrified mobility. Automakers in Germany, France, and the U.K. deploy high-density solenoid architectures in turbocharged engines, DSG and DCT transmissions, and advanced exhaust after-treatment systems. Rising EV adoption increases the requirement for precision solenoids supporting coolant routing, cabin heat pumps, and regenerative braking functions. The region’s established Tier-1 supplier ecosystem strengthens innovation in lightweight and thermally stable solenoid materials. Continuous investment in sustainable automotive technologies further elevates Europe’s position in high-efficiency solenoid integration.
Asia-Pacific
Asia-Pacific accounts for an exact 31% share, driven by high vehicle production in China, Japan, South Korea, and India. Expanding manufacturing capacity, rising adoption of compact passenger cars, and fast growth of hybrid and electric models sustain strong solenoid demand. OEMs deploy solenoids across engine control, transmission management, HVAC, and emission systems to meet tightening regional fuel-efficiency regulations. Cost-effective component production and large-scale automotive exports strengthen APAC’s market leadership. Local suppliers increasingly adopt miniaturized and high-flow solenoid technologies, supporting applications in turbo engines, automated gearboxes, and advanced thermal systems in EV platforms.
Latin America
Latin America captures an exact 4% share, supported by steady growth in passenger and light commercial vehicle production in Brazil, Mexico, and Argentina. Demand for automotive solenoids increases as regional automakers enhance emission-control systems and adopt electronically controlled transmissions and braking technologies. The aftermarket also contributes significantly due to the region’s aging vehicle fleet, driving replacement of fuel, purge, and brake-related solenoids. Although technology penetration remains moderate compared to mature markets, rising investments from global OEMs and tightening emission norms create opportunities for advanced solenoids with improved durability and cost-efficient designs.
Middle East & Africa
The Middle East & Africa region holds an exact 2% share, shaped by modest yet growing adoption of electronically controlled vehicle systems. Demand is supported by increasing sales of SUVs, pickups, and light commercial vehicles across Gulf countries and South Africa. Solenoid usage expands as manufacturers incorporate improved fuel-management, HVAC, and braking systems to meet evolving safety and efficiency standards. Harsh operating environments drive preference for high-temperature, corrosion-resistant solenoids. Although automotive manufacturing remains limited, rising vehicle imports and maintenance needs strengthen the aftermarket’s contribution to solenoid consumption across the region.
Market Segmentations:
By Valve Design:
- 2-way valve
- 3-way valve
By Vehicle:
- Passenger vehicles
- Light Commercial Vehicles (LCV)
By Application:
- Engine control
- Fuel & emission control
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Automotive Solenoid Market features a diverse mix of global manufacturers and specialized regional suppliers, including Curtiss Wright Corporation, Danfoss Industries Ltd, SMC Corporation, AirTAC International Group, Emerson Electric Co., Anshan Solenoid Valve Co. Ltd, IMI Process Automation, CEME Group, Parker Hannifin Corporation, and KANEKO SANGYO Co. Ltd. the Automotive Solenoid Market is shaped by a mix of global technology manufacturers and specialized component suppliers that focus on developing high-precision, durable, and energy-efficient actuation systems for modern vehicle architectures. Companies strengthen their positions by investing in advanced electromagnetic design, high-temperature insulation materials, and miniaturized valve structures that meet the needs of turbocharged engines, hybrid powertrains, and EV thermal systems. Continuous innovation in fast-response actuators, smart diagnostic capabilities, and integrated mechatronic modules enhances system reliability and supports OEM efforts to meet stringent emission, safety, and efficiency standards. Additionally, expanded automation in manufacturing and greater emphasis on quality control enable suppliers to deliver consistent performance while scaling production for global automotive platforms.
Key Player Analysis
- Curtiss Wright Corporation
- Danfoss Industries Ltd
- SMC Corporation
- AirTAC International Group
- Emerson Electric Co.
- Anshan Solenoid Valve Co. Ltd
- IMI Process Automation
- CEME Group
- Parker Hannifin Corporation
- KANEKO SANGYO Co. Ltd
Recent Developments
- In January 2025, Emerson partnered with Laramie Energy to deploy ASCO zero-emissions electric dump valves, drastically cutting energy use by 98.75% and stopping methane venting to meet tough environmental rules, boosting production by stabilizing pressure. This innovation, using ultra-low power valves, helps oil and gas producers comply with EPA mandates, reducing operating costs and improving efficiency.
- In October 2024, Solero Technologies (backed by Atar Capital) announced the agreement to buy Kendrion's EU & US automotive business, with the acquisition completing significantly boosting Solero's global footprint and sustainable product offerings, adding transmission solenoids and engine components to their portfolio.
- In January 2024, Nidec Power Train Systems announced the first-ever solenoid valve designed for diagnosing blow-by gas leaks in engines, a key innovation to meet tough OBD-II standards (like CARB's) requiring better detection of gases escaping past piston rings, helping engines run cleaner and meet emissions rules.
Report Coverage
The research report offers an in-depth analysis based on Valve Design, Vehicle, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as hybrid and electric vehicles increase solenoid adoption for thermal, braking, and coolant flow control.
- Automakers will integrate more compact and energy-efficient solenoids to support advanced powertrain downsizing.
- Intelligent solenoids with embedded sensors will gain traction for real-time diagnostics and predictive maintenance.
- Demand will rise for high-temperature, corrosion-resistant solenoids used in turbocharged and high-pressure engine systems.
- EV battery protection and heat-pump systems will create new opportunities for specialized solenoid designs.
- Suppliers will adopt advanced manufacturing automation to improve precision and reduce defect rates.
- Modular solenoid assemblies will grow as OEMs transition to zonal vehicle architectures.
- Regulatory pressure on emissions will continue to increase solenoid deployment in fuel and exhaust systems.
- Asia-Pacific will strengthen its role as a key production hub for cost-efficient solenoid manufacturing.
- Collaboration between solenoid suppliers and OEM engineering teams will accelerate platform-specific innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automotive Solenoid Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Solenoid Market projected to grow between 2024 and 2032?
Which Automotive Solenoid Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Solenoid Market?
Who are the leading companies in the Automotive Solenoid Market?
Which region commanded the largest share of the Automotive Solenoid Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Solenoid Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Solenoid Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5058 million → 2032: USD 7703.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Solenoid Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Solenoid Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Solenoid Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Solenoid Market Drivers
- 3.3 Automotive Solenoid Market Restraints & Challenges
- 3.4 Automotive Solenoid Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Solenoid Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Solenoid Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Solenoid category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Solenoid Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Solenoid Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Solenoid market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Solenoid Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Solenoid Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Solenoid Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Solenoid (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Solenoid Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Solenoid Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Solenoid Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Solenoid Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Solenoid Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Solenoid Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Solenoid Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Solenoid Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Solenoid Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
