
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Steel Market Size 2023 | USD 126,379.5 Million |
| Automotive Steel Market, CAGR | 2.72% |
| Automotive Steel Market Size 2032 | USD 156,669.46 Million |
Market Overview
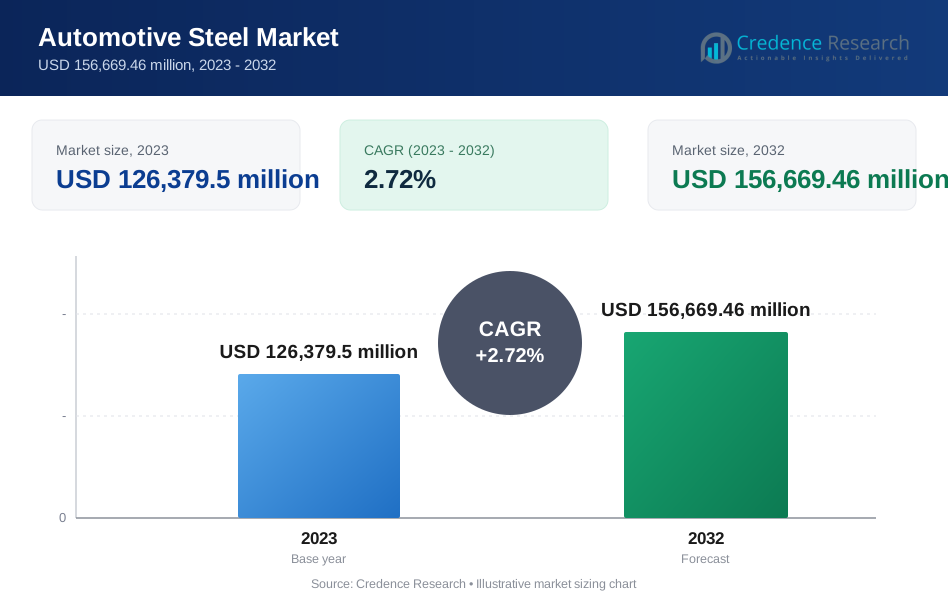
The Automotive Steel Market is projected to grow from USD 126,379.5 million in 2023 to an estimated USD 156,669.46 million by 2032, with a compound annual growth rate (CAGR) of 2.72% from 2024 to 2032. This steady growth is driven by increasing vehicle production worldwide, especially in emerging economies.
Several market drivers and trends are shaping the Automotive Steel Market. The rise in demand for electric and hybrid vehicles, combined with stringent environmental regulations, is pushing automakers to use advanced high-strength steel (AHSS). Additionally, the increased focus on vehicle weight reduction to improve fuel efficiency and reduce emissions has further fueled the use of steel in automotive applications. Trends such as the adoption of new steel production technologies and advancements in steel grades are also contributing to market expansion.
Geographically, Asia-Pacific dominates the automotive steel market, driven by significant automotive production in countries like China, Japan, and India. North America and Europe also hold substantial shares, driven by stringent fuel efficiency regulations and the growing adoption of lightweight materials in the automotive sector. Key players in the Automotive Steel Market include ArcelorMittal, Nippon Steel Corporation, POSCO, Thyssenkrupp AG, and Tata Steel. These companies continuously invest in research and development to produce innovative steel products, strengthen their market presence, and meet the evolving needs of the automotive industry.
Market Drivers
Growing Demand for High-Strength Steel in Lightweight Vehicle Manufacturing
One of the most significant drivers of the Automotive Steel Market is the rising demand for high-strength steel (HSS) and advanced high-strength steel (AHSS). Automotive manufacturers increasingly prioritize vehicle designs that offer enhanced fuel efficiency, without compromising on safety. To achieve this, they rely on lightweight materials, such as HSS and AHSS, which deliver the required strength and rigidity while reducing overall vehicle weight. AHSS is engineered to meet stringent safety standards while maintaining a lower density, which allows for reduced weight. This makes it ideal for structural applications, body panels, and critical safety components in modern vehicles.The growing focus on vehicle weight reduction is linked to broader regulatory pressures and environmental concerns. As governments worldwide implement stringent fuel efficiency standards and emissions regulations, automakers are required to adapt their designs to meet these evolving requirements. AHSS has become the preferred material for many automotive companies because it allows for a more sustainable vehicle architecture. For instance, according to Tata Steel, incorporating AHSS in automobiles can reduce vehicle weight by 35.0-40.0% compared to traditional steel, leading to a substantial reduction of four tons of greenhouse gases over a five-passenger family car's lifespan.
Technological Advancements in Steel Production
Technological advancements in steel production methods have significantly impacted the Automotive Steel Market. Innovations such as hot stamping, laser welding, and continuous casting have improved the properties of steel, making it more adaptable for a wider range of automotive applications. These technologies help manufacturers produce steel grades that offer higher strength, greater formability, and improved corrosion resistance, all of which are crucial for modern vehicle manufacturing.The development of third-generation AHSS, which combines enhanced formability and ductility with high tensile strength, represents a breakthrough in steel production. This new generation of steel offers automakers additional opportunities for vehicle weight reduction while maintaining safety and performance. Additionally, these advanced steel grades support increased design flexibility, enabling manufacturers to incorporate complex geometries and intricate structural elements that improve crashworthiness and passenger protection. For instance, ArcelorMittal's Usibor and Ductibor series are specifically designed for automotive safety components, offering exceptional strength and ductility for critical safety parts in vehicles.
Rise in Electric Vehicle (EV) Production and Adoption
The rapid growth of the electric vehicle (EV) market is another critical driver of the Automotive Steel Market. EV manufacturers are actively seeking materials that provide a balance between weight reduction, durability, and cost-effectiveness. Steel remains an essential material in EV manufacturing, particularly for chassis and safety components, due to its high strength-to-weight ratio and recyclability. While aluminum and other lightweight materials are sometimes used to reduce weight, steel continues to offer unmatched cost advantages, making it an attractive choice for EV manufacturers looking to scale production.The shift toward EVs also aligns with environmental and regulatory trends, as more countries implement policies to phase out internal combustion engines in favor of zero-emission vehicles. This shift has led automakers to explore steel grades optimized for EV applications, such as battery enclosures that ensure impact resistance, thermal stability, and crash protection. For instance, electric car sales reached almost 14 million new registrations globally in 2023, bringing their total number on the roads to 40 million. This trend is expected to continue, with electric cars potentially accounting for more than one in five cars sold worldwide in 2024.
Increased Focus on Sustainability and Recycling
Sustainability is becoming a pivotal factor in material selection for automakers, and steel’s recyclability gives it a competitive edge in the automotive sector. Steel is one of the most recycled materials globally, and its ability to be recycled without any loss of quality makes it a preferred choice for environmentally conscious manufacturers. The automotive industry’s increased focus on circular economy principles has prompted automakers to seek materials that align with sustainability goals, reduce environmental impacts, and meet customer expectations for greener products. Automotive steel producers are responding to these demands by developing and promoting eco-friendly production processes that reduce greenhouse gas emissions, conserve energy, and minimize waste. For example, companies like ArcelorMittal and Tata Steel have implemented initiatives to lower carbon emissions through advanced production techniques and renewable energy integration. Additionally, by incorporating more recycled content into their steel products, automotive steel manufacturers are enabling automakers to achieve higher sustainability standards. This focus on environmentally friendly practices is expected to boost the demand for automotive steel, as manufacturers increasingly seek materials that align with their sustainability objectives.
Market Trends
Increasing Adoption of Advanced High-Strength Steel (AHSS) for Lightweighting and Enhanced Safety
A prominent trend in the Automotive Steel Market is the growing adoption of advanced high-strength steel (AHSS) in vehicle manufacturing. As automakers strive to meet stringent regulatory standards for fuel efficiency and emissions, they are increasingly focused on lightweighting strategies to reduce vehicle weight without compromising safety. AHSS offers an ideal solution by providing a high strength-to-weight ratio that allows manufacturers to reduce the overall weight of vehicles while maintaining structural integrity. For instance, the use of Advanced High-Strength Steel (AHSS) can reduce a vehicle's structural weight by as much as 25% and cut total life cycle CO2 emissions by up to 15% more than any other automotive material.Additionally, AHSS enables the production of safer vehicles, as it offers improved energy absorption and resistance to deformation in the event of a collision. This material is particularly advantageous for structural components like door beams, bumpers, and pillars, where safety is critical. With the continued emphasis on both fuel efficiency and passenger safety, the adoption of AHSS is expected to expand, driving innovation and further advancements in steel grades and processing technologies within the automotive industry.
Focus on Sustainability through Recycling and Eco-Friendly Production Methods
Sustainability has become a significant focus for the Automotive Steel Market, reflecting broader industry and consumer demands for environmentally responsible products. Steel is highly recyclable, and automotive manufacturers are increasingly prioritizing materials that support circular economy principles and reduce carbon footprints. For instance, recycling steel saves 72% of the energy needed for primary production, equivalent to 4,697 kWh per tonne. This significant energy saving contributes to the overall sustainability of steel in automotive applications.In response, steel producers are developing eco-friendly production methods, such as electric arc furnace (EAF) technology, which uses less energy and emits fewer greenhouse gases compared to traditional blast furnace methods. Leading steel manufacturers are also investing in renewable energy sources and implementing carbon capture technologies to minimize emissions associated with steel production. Furthermore, automakers are seeking steel products with higher recycled content, as this aligns with their sustainability objectives and enhances the appeal of their vehicles among environmentally conscious consumers. The emphasis on sustainability within the automotive sector not only drives demand for recycled steel but also spurs ongoing innovation in green steel production techniques, positioning steel as a sustainable material choice for the future of automotive manufacturing.
Market Restraints and Challenges
Competition from Alternative Lightweight Materials
One of the primary challenges for the Automotive Steel Market is the growing competition from alternative lightweight materials such as aluminum, carbon fiber, and composites. As automakers strive to meet increasingly stringent fuel efficiency and emissions standards, they are exploring these materials for their superior lightweighting properties. Aluminum, for instance, is nearly one-third the weight of steel and is being adopted in vehicle parts such as body panels and structural components. Although advanced high-strength steel (AHSS) offers a compelling balance of strength and weight, aluminum and composites continue to gain traction due to their excellent strength-to-weight ratios and corrosion resistance. Additionally, as production technologies for these materials advance, their costs are gradually decreasing, making them more viable for mass production. The growing adoption of these alternatives poses a significant restraint on the Automotive Steel Market, pressuring steel manufacturers to enhance the performance, durability, and cost-effectiveness of their offerings to maintain market share.
Volatility in Raw Material Prices and Supply Chain Disruptions
The Automotive Steel Market faces ongoing challenges related to raw material price volatility and supply chain disruptions. Steel production relies heavily on raw materials like iron ore, coal, and scrap metal, the prices of which are subject to fluctuations due to geopolitical tensions, trade policies, and global demand-supply imbalances. This price volatility directly impacts production costs, which can, in turn, affect pricing strategies and profitability for automotive steel producers. Moreover, recent global supply chain disruptions, exacerbated by the COVID-19 pandemic, have underscored the vulnerability of steel manufacturers to delays and shortages in critical raw materials. These disruptions can hinder the timely delivery of steel to automotive manufacturers, affecting production schedules and operational efficiencies. As the automotive industry continues to recover from these disruptions, steel manufacturers are challenged to navigate supply chain uncertainties and manage cost pressures, both of which can limit their ability to scale production and maintain steady growth in the market.
Market Segmentation Analysis
By Process
The Basic Oxygen Furnace (BOF) and Electric Arc Furnace (EAF) processes play crucial roles in the automotive steel market, each offering distinct advantages. BOF, one of the most widely used methods, efficiently produces large volumes of steel by oxidizing carbon and other impurities in molten iron, making it ideal for high-volume automotive production. However, it is energy-intensive and emits significant carbon dioxide, leading to environmental concerns and prompting regulatory pressures to reduce emissions. In contrast, the EAF process has gained popularity due to its environmental benefits, using electric arcs to melt scrap metal, which results in lower carbon emissions and allows for greater recycled content. This makes EAF more sustainable, aligning with the automotive industry’s increasing focus on eco-friendly materials. Additionally, EAF’s flexibility supports the production of various steel grades, including advanced high-strength steel (AHSS), essential for modern vehicle designs. As sustainability becomes a key driver, EAF is expected to see growth, particularly in regions with stringent emissions regulations.
By Vehicle type
In the Automotive Steel Market, passenger vehicles represent the largest segment, driven by high production volumes and a strong demand for materials that combine safety, durability, and fuel efficiency, leading to increased adoption of advanced high-strength steel (AHSS) to meet safety and emissions standards. Light commercial vehicles (LCVs), including pickup trucks and vans, also contribute significantly to the market, relying on steel for its durability and ability to support heavier payloads while enhancing fuel efficiency through weight management. Heavy commercial vehicles (HCVs), such as trucks and buses, require the robustness of steel for load-bearing components and chassis structures, ensuring structural integrity and stability under demanding conditions. While two-wheeler vehicles represent a smaller market segment, they still rely on steel for frames, exhausts, and suspension systems, particularly in regions like Asia-Pacific, where affordability and durability are essential factors in motorcycle and scooter production.
Segments
By Process
- Basic Oxygen Furnace (BOF)
- Electric Arc Furnace (EAF)
By Vehicle
- Passenger Vehicles
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Twowheeler Vehicles
Market, Product By Application
- Low Strength Steel
- Conventional HSS
- Advanced High Strength Steel (AHSS)
- Others
Market, By Application
- Body Structure
- Power Train
- Suspension
- Others
Market, By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Latin America
- Brazil
- Mexico
- Middle East & Africa
- South Africa
- Saudi Arabia
Regional Analysis
Asia-Pacific (45%):
Asia-Pacific dominates the Automotive Steel Market, accounting for approximately 45% of the global market share. This region's leadership is largely due to the high volume of vehicle production in countries like China, Japan, India, and South Korea. China, as the world’s largest automotive producer, significantly influences demand for automotive steel, while Japan and South Korea are renowned for their advanced automotive technologies and high-quality vehicle exports. Additionally, the region’s strong demand for two-wheeler vehicles further drives steel consumption. The growing middle class in emerging economies, coupled with increasing urbanization, has led to rising automotive sales, contributing to the substantial market share held by Asia-Pacific. The region’s regulatory focus on fuel efficiency and emissions is also boosting the adoption of advanced high-strength steel (AHSS) in vehicles, aligning with global trends toward lighter, more fuel-efficient vehicles.
North America (20%):
North America holds around 20% of the Automotive Steel Market, driven by a robust automotive industry and high consumer demand for passenger vehicles, SUVs, and light trucks. The United States is the primary contributor to this market share, with strong domestic automotive production and a focus on technological advancements. In North America, automakers are increasingly incorporating AHSS and other advanced steel grades to meet stringent fuel efficiency and safety standards. Furthermore, the rising adoption of electric vehicles (EVs) in the U.S. and Canada has created a growing need for lightweight materials, including automotive steel, to optimize EV performance and battery efficiency. The region’s emphasis on sustainability and recycling is expected to continue driving demand for steel in automotive applications.
Key players
- ArcelorMittal
- TATA Steel
- China Steel Corporation
- Hyundai Steel
- United States Steel Corporation
- JSW Group
- POSCO
- Nippon Steel & Sumitomo Metal Corporation
- JFE Steel Corporation
- NUCOR Corporation
- Jindal Steel & Power
- Grow Ever Steel
- HBIS Group
- Outokumpu OYJ
- Kobe Steel
Competitive Analysis
The Automotive Steel Market is highly competitive, with key players striving to strengthen their market positions through technological advancements, strategic mergers and acquisitions, and geographic expansion. ArcelorMittal, TATA Steel, and POSCO are leading the market due to their expansive product portfolios, global presence, and focus on advanced high-strength steel (AHSS) to meet evolving automotive industry demands. Companies such as Nippon Steel & Sumitomo Metal Corporation and JFE Steel Corporation are investing in research and development to enhance the quality and performance of automotive steel, particularly to support the growing electric vehicle (EV) sector. Meanwhile, regional players like HBIS Group and Jindal Steel & Power are expanding their capabilities to address increasing domestic demand. The emphasis on sustainability and recycling has also led companies like NUCOR Corporation and Outokumpu OYJ to integrate eco-friendly production methods, positioning them favorably among environmentally conscious automakers. This dynamic competitive landscape fosters continuous innovation and adaptation across the industry.
Recent Developments
- In September 2023, ArcelorMittal partnered with LISI AUTOMOTIVE to produce low carbon-emissions steel to enhance sustainability in the automotive manufacturing process.
- In November 2023, TATA Steel successfully merged with five businesses including TATA Steel Mining Limited and TATA Steel Long Products Limited.
- In August 2023, China Steel Corporation placed a large order to ramp up electrical steel production, focusing on high-strength and thin high-grade electrical steel for electric vehicles.
- In October 2023, Hyundai Steel participated in Steel & Metal Korea (SMK) 2023 to promote its carbon-neutral roadmap and eco-friendly strategies.
- In December 2023, Nippon Steel Corporation acquired United States Steel Corporation for approximately $14.9 billion.
- In October 2024, JSW Group and MG Motor India established a joint venture called JSW MG Motor India Pvt Ltd, planning to launch their first car and scale production capacity.
- In October 2023, POSCO completed construction of a new plant for automotive steel plates in Tangshan, China, with an annual production capacity of 450,000 tons.
- In ficant investments in production capabilities for automotive flat steel.
- In February 2023, JFE Steel Corporation formed a joint venture with JSW Steel to establish a grain-oriented electrical steel manufacturing facility in India.
- In June 2024, Nucor Corporation announced an acquisition of Rytec Corporation, a manufacturer of high-performance commercial doors, valued at $565 million.
- In October 2023, a joint venture project for producing high-strength and ultra-thin automotive sheets began operation in Tangshan, China.
- In June 2023, Outokumpu started a collaboration with thyssenkrupp Materials Processing Europe and Boysen Group to help decarbonize the automotive industry through the introduction of Circle Green stainless steel.
- In August 2024, Kobe Steel is forming a joint venture with Baowu Aluminum Technology Co., Ltd. to manufacture and sell aluminum panels for automotive manufacturers in China.
Market Concentration and Characteristics
The Automotive Steel Market is moderately concentrated, with a few large global players, such as ArcelorMittal, TATA Steel, and POSCO, holding significant market shares due to their extensive production capacities, broad geographic reach, and advanced technological capabilities. These key players, along with regional leaders like JFE Steel Corporation and Nippon Steel, shape the competitive landscape by focusing on high-quality, advanced high-strength steel (AHSS) products that meet the automotive industry's evolving demands for lightweight, durable, and cost-effective materials. Market characteristics include a strong emphasis on sustainability, with increasing investments in eco-friendly production processes and recycling initiatives to address regulatory pressures and consumer preferences for greener products. The market also exhibits ongoing innovation, as manufacturers continuously develop new steel grades to align with advancements in vehicle design and the growth of electric vehicles.
Report Coverage
The research report offers an in-depth analysis based on Process, Vehicle, Product By Application, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Advanced high-strength steel (AHSS) will continue to see high demand as automakers prioritize lightweighting and safety to meet stringent fuel efficiency and emissions standards globally.
- As electric vehicle (EV) adoption grows, manufacturers will increasingly utilize automotive steel for battery enclosures and lightweight structural components that enhance performance and range.
- The market will place greater emphasis on sustainable production practices, with companies investing in low-emission technologies, renewable energy, and increased recycling to meet environmental regulations.
- Innovations in steel production, such as improved hot stamping and new alloy formulations, will enhance the properties of automotive steel, enabling better strength-to-weight ratios and corrosion resistance.
- Asia-Pacific will remain a dominant market, driven by high automotive production volumes, rapid urbanization, and increased vehicle demand in countries like China and India.
- As circular economy principles gain traction, manufacturers will increase the use of recycled steel in production, reducing waste and lowering costs while maintaining quality.
- Despite steel's advantages, materials like aluminum and carbon fiber will continue to challenge the market, prompting steelmakers to innovate to retain their competitiveness in automotive applications.
- The development of autonomous vehicles will drive demand for specialized steel components that provide added structural support for new design frameworks and sensor integration.
- Major players are expected to pursue carbon-neutral goals by investing in green steel technologies and energy-efficient processes, aligning with broader industry sustainability goals.
- To enhance their competitive positions, steel manufacturers will likely engage in mergers and acquisitions, enabling access to advanced technologies, expanded production capacities, and entry into new geographic markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for High-Strength Steel in Lightweight Vehicle Manufacturing
Automotive manufacturers are increasingly adopting high-strength and advanced high-strength steel (AHSS) to reduce vehicle weight and improve fuel efficiency while maintaining safety standards. This shift is driven by regulatory pressures for lower emissions and the need for cost-effective lightweighting solutions.
Technological Advancements in Steel Production
Innovations such as hot stamping, laser welding, and the development of third-generation AHSS have enhanced the strength, formability, and corrosion resistance of automotive steel. These advancements enable automakers to design safer, lighter vehicles and support the integration of complex structural components.
Rise in Electric Vehicle (EV) Production and Adoption
The rapid expansion of the electric vehicle market is increasing demand for steel in battery enclosures and chassis components, as manufacturers seek materials that balance weight, durability, and cost. Steel's recyclability and strength-to-weight ratio make it a preferred choice for EV applications.
Increased Focus on Sustainability and Recycling
Automotive steel producers are investing in eco-friendly production processes and increasing recycled content to meet automakers' sustainability goals. Steel's high recyclability and the industry's move toward circular economy principles are boosting its appeal in automotive manufacturing.
Stringent Environmental and Fuel Efficiency Regulations
Global regulations mandating lower vehicle emissions and higher fuel efficiency are compelling automakers to use advanced steel grades that enable lighter, more efficient vehicles. This regulatory environment is accelerating the adoption of innovative steel solutions across the automotive sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Automotive Steel Market in 2023, and what is its projected growth by 2032?
What factors are driving the demand for automotive steel?
Why is advanced high-strength steel (AHSS) important in the automotive industry?
Which region holds the largest share in the Automotive Steel Market?
How is sustainability influencing the Automotive Steel Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Process
- 1.2.1 Basic Oxygen Furnace (BOF)
- 1.2.2 Electric Arc Furnace (EAF)
- 1.3 By Vehicle
- 1.3.1 Passenger Vehicles
- 1.3.2 Light Commercial Vehicles
- 1.3.3 Heavy Commercial Vehicles
- 1.3.4 Twowheeler Vehicles
- 1.4 By Application
- 1.4.1 Body Structure
- 1.4.2 Power Train
- 1.4.3 Suspension
- 1.4.4 Others
- 1.5 By Product By Application
- 1.5.1 Low Strength Steel
- 1.5.2 Conventional HSS
- 1.5.3 Advanced High Strength Steel (AHSS)
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 126,379.5 million → 2032: USD 156,669.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Steel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Steel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Steel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Steel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Steel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Steel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Steel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Steel Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 126,379.5 million → 2032: USD 156,669.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Steel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Process - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Basic Oxygen Furnace (BOF)
- 12.3.7.2 Electric Arc Furnace (EAF)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Vehicles
- 12.4.7.2 Light Commercial Vehicles
- 12.4.7.3 Heavy Commercial Vehicles
- 12.4.7.4 Twowheeler Vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Body Structure
- 12.5.7.2 Power Train
- 12.5.7.3 Suspension
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Low Strength Steel
- 12.6.7.2 Conventional HSS
- 12.6.7.3 Advanced High Strength Steel (AHSS)
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Steel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Steel Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Steel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Steel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ArcelorMittal
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 TATA Steel
- 18.4 POSCO
- 18.5 Nippon Steel Corporation
- 18.6 JFE Steel Corporation
- 18.7 Hyundai Steel
- 18.8 United States Steel Corporation
- 18.9 China Steel Corporation
- 18.10 JSW Group
- 18.11 NUCOR Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

