
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aviation MRO Software Market Size 2024 | USD 7,412 million |
| Aviation MRO Software Market, CAGR | 4.1% |
| Aviation MRO Software Market Size 2032 | USD 10,222 million |
Market Overview
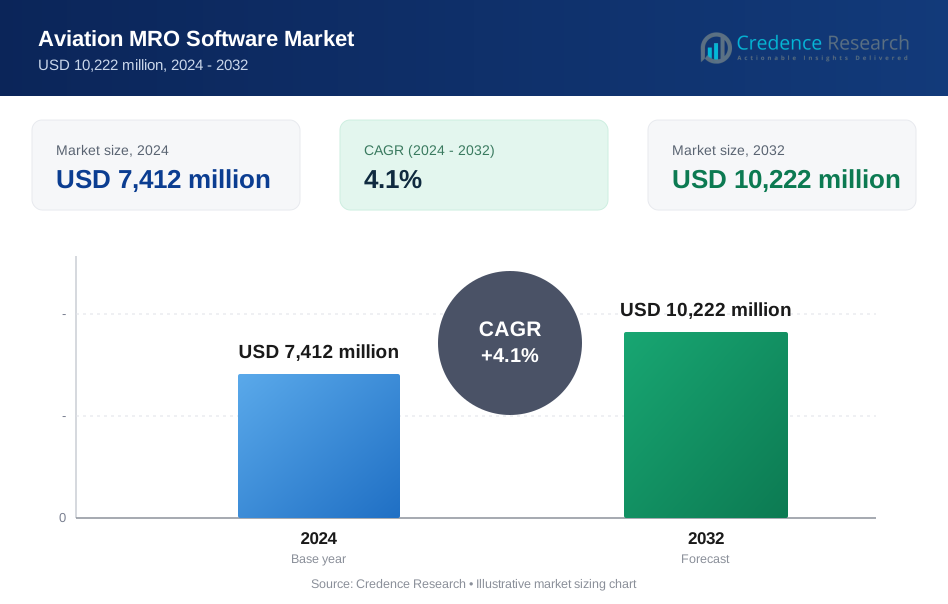
The Global Aviation MRO Software Market is projected to grow from USD 7,412 million in 2024 to an estimated USD 10,222 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.1% from 2025 to 2032.
Key drivers influencing the Aviation MRO Software Market include the growing demand for efficient asset management and regulatory compliance. Airlines and MRO service providers focus on reducing downtime and operational costs through predictive maintenance and automation features. Trends such as the integration of advanced analytics, cloud-based platforms, and Internet of Things (IoT) technologies enhance real-time data accessibility and decision-making capabilities. These innovations improve operational efficiency and safety, further fueling market adoption.
Geographically, North America holds a dominant position due to the presence of major airline operators and advanced technological infrastructure. Europe follows closely, supported by stringent aviation safety regulations and investments in digital transformation. The Asia-Pacific region is expected to witness the fastest growth, driven by increasing air travel demand and modernization of maintenance facilities in emerging economies. Leading key players in the market include IBM Corporation, Honeywell International Inc., Ramco Systems, and IFS AB, all of which focus on product innovation and strategic partnerships to strengthen their market presence globally.
Market Insights
- The Aviation MRO Software Market is projected to grow steadily from USD 7,412 million in 2024 to USD 10,222 million by 2032, at a CAGR of 4.1%.
- Increasing air traffic and expanding commercial and military aircraft fleets drive demand for optimized maintenance and repair operations.
- Growing need for efficient asset management and strict regulatory compliance significantly fuel market adoption.
- Integration of advanced analytics, cloud platforms, and IoT enhances real-time decision-making and operational efficiency.
- Challenges include complexity in integrating new software with legacy systems and concerns over data security.
- North America dominates the market with a strong airline presence and technological infrastructure.
- Asia-Pacific shows the fastest regional growth, supported by rising air travel and modernization of maintenance facilities.
Market Drivers
Increasing Demand for Operational Efficiency and Cost Reduction in Aviation Maintenance
The Global Aviation MRO Software Market benefits significantly from the rising demand for operational efficiency and cost control in aircraft maintenance processes. Airlines and MRO providers seek software solutions that optimize maintenance schedules, minimize aircraft downtime, and reduce labor and material expenses. Predictive maintenance tools help identify potential failures before they occur, preventing costly repairs and flight delays. Efficient inventory management within these platforms reduces excess stock and streamlines spare parts availability. It supports better resource allocation, which translates into lower operational costs and improved profitability. Growing competition among airlines to enhance service reliability further fuels demand for such advanced software. This drive for efficiency remains a primary growth catalyst for the market.
- For instance, companies using modern MRO software have automated up to 90,000 routine parts purchases annually and accelerated maintenance turnaround times by 10 days per event, demonstrating tangible gains in operational efficiency and cost savings
Adoption of Advanced Technologies Enhancing Predictive Maintenance Capabilities
Technological advancements drive significant growth in the Aviation MRO Software Market through enhanced predictive maintenance and analytics capabilities. Integration of artificial intelligence (AI), machine learning, and Internet of Things (IoT) enables real-time monitoring of aircraft components and systems. These technologies help detect anomalies and forecast maintenance needs with higher accuracy. Cloud-based platforms facilitate seamless data sharing among stakeholders, improving collaboration and decision-making. It enables faster response times and reduces aircraft grounding periods. The shift toward digital transformation within the aviation sector accelerates adoption of such sophisticated software solutions. Investment in research and development ensures continual innovation and improved performance of MRO software.
- For instance, predictive maintenance platforms such as Veryon Reliability have been deployed across more than 4,100 aircraft in over 20 fleet types, achieving 95% predictive accuracy in parts forecasting and reducing repeat defects by 30,000 annually for a single regional airline
Regulatory Compliance and Safety Standards Driving Software Integration
Strict regulatory frameworks and aviation safety standards necessitate comprehensive maintenance documentation and traceability. The Global Aviation MRO Software Market grows due to increasing pressure on airlines and MRO providers to comply with these regulations. It offers automated tracking of maintenance activities, audit trails, and reporting features that enhance transparency and accountability. Meeting compliance requirements helps avoid penalties and supports certification processes. Governments and international aviation bodies continuously update guidelines, which forces operators to adopt adaptable software solutions. This regulatory environment pushes industry participants to invest heavily in MRO software for maintaining compliance and safety.
Expansion of Global Air Travel and Fleet Growth Supporting Market Demand
Rapid growth in global air travel and expansion of commercial and military aircraft fleets contribute to rising demand for Aviation MRO Software. Increasing passenger volumes require efficient maintenance solutions to ensure aircraft availability and safety. Emerging markets in Asia-Pacific and Latin America show substantial investments in fleet modernization and infrastructure upgrades. It enables operators to manage larger, more complex fleets with the help of advanced software tools. The growth in regional low-cost carriers also increases reliance on MRO software to maintain cost-effective operations. These market dynamics sustain continuous demand and expansion opportunities for Aviation MRO Software providers worldwide.
Market Trend
Rising Adoption of Cloud-Based Platforms Enhancing Flexibility and Scalability
The Global Aviation MRO Software Market experiences a strong shift toward cloud-based solutions, driven by the need for greater flexibility and scalability. Cloud platforms allow users to access real-time data from multiple locations, supporting decentralized maintenance operations. It enables seamless updates and integration with other enterprise systems without heavy infrastructure investments. Companies benefit from reduced IT costs and improved data security through managed cloud services. The demand for subscription-based models also increases, providing cost-effective access to advanced features. This trend supports faster deployment and easier scalability to accommodate fluctuating business needs. Cloud adoption remains a key factor reshaping MRO software usage globally.
- For instance, EmpowerMX, a cloud-based MRO software provider, launched its touch-free electronic task card (ETC) in 2020, enabling operators to digitally complete maintenance tasks without paper. This mobile-ready solution was rapidly adopted by MRO service providers to support post-pandemic operations and demonstrates the scale of cloud-based innovation in the sector
Integration of Artificial Intelligence and Machine Learning for Predictive Analytics
Artificial intelligence (AI) and machine learning (ML) integration gain momentum within the Aviation MRO Software Market, enhancing predictive maintenance and decision-making processes. These technologies analyze vast amounts of historical and real-time data to identify patterns and predict potential failures accurately. It reduces unplanned maintenance and optimizes asset utilization by forecasting component life cycles. AI-powered automation streamlines routine tasks, improving workforce efficiency. The trend accelerates digital transformation initiatives within airlines and MRO service providers. Continuous improvements in algorithms and computing power fuel further adoption of AI and ML in maintenance management.
- For instance, Delta Air Lines manages over 5,000 daily flights and uses AI algorithms to analyze data from aircraft sensors and maintenance records. This predictive maintenance program has allowed Delta to significantly reduce unplanned maintenance activities and improve operational reliability across its global fleet
Growing Focus on Mobile and IoT-Enabled Solutions for Real-Time Monitoring
Mobile applications and Internet of Things (IoT) devices increasingly integrate with Aviation MRO Software to provide real-time monitoring and remote diagnostics. The Global Aviation MRO Software Market benefits from these technologies by enhancing data collection accuracy and immediacy. Maintenance crews gain instant access to critical information via mobile devices, enabling faster response and repair. IoT sensors track aircraft conditions continuously, transmitting data directly to MRO platforms for analysis. It improves transparency and helps maintain regulatory compliance through detailed records. The mobility trend empowers operators to improve maintenance workflows and reduce aircraft turnaround times effectively.
Emphasis on Cybersecurity Measures to Protect Sensitive Data
With growing digitalization, cybersecurity becomes a vital focus within the Aviation MRO Software Market. Protecting sensitive operational and maintenance data from cyber threats remains a top priority for airlines and MRO providers. It involves implementing multi-layered security protocols, including encryption, secure access controls, and threat detection systems. Vendors invest in robust cybersecurity frameworks to ensure compliance with industry standards and build customer trust. The rise in cyberattacks on critical infrastructure reinforces the need for advanced security solutions integrated into MRO software. Strengthening cybersecurity capabilities remains essential to supporting the industry's digital growth safely.
Market Challenges
Complexity of Integration with Legacy Systems Hindering Seamless Software Deployment
The Global Aviation MRO Software Market faces challenges due to the complexity of integrating new software with existing legacy systems. Many airlines and MRO providers operate diverse and outdated IT infrastructures that complicate smooth implementation. It requires significant customization and technical expertise to ensure compatibility without disrupting ongoing operations. The integration process often demands considerable time and financial investment, which can delay software adoption. Resistance from staff accustomed to traditional methods also slows digital transformation efforts. This challenge limits the pace at which advanced MRO solutions can be deployed across the industry. Overcoming legacy system barriers remains critical for widespread market growth.
- For instance, during the migration of Air Algérie’s MRO database from a legacy IT management system to the AMOS platform, Swiss Aviation Software’s data integration team reported the need to process and validate data from more than 30 different legacy software programs, requiring hundreds of hours from engineers to ensure a safe and accurate transition
Concerns Over Data Security and Regulatory Compliance Restricting Market Expansion
Data security concerns pose a significant challenge to the Aviation MRO Software Market amid increasing cyber threats targeting critical aviation infrastructure. Operators hesitate to adopt cloud-based and digital solutions due to fears of data breaches and unauthorized access. It necessitates strict adherence to regulatory requirements governing data protection and privacy, which vary across regions. Meeting these complex compliance standards demands continuous updates and audits, adding operational burdens. Smaller MRO providers may struggle with the costs and expertise required for robust cybersecurity measures. These factors constrain rapid market penetration and adoption of innovative software technologies. Ensuring secure and compliant solutions is essential to address these challenges effectively.
Market Opportunities
Expansion into Emerging Markets with Growing Aviation Infrastructure and Fleet Modernization
The Global Aviation MRO Software Market holds significant opportunity in emerging regions where aviation infrastructure and fleets are rapidly expanding. Countries in Asia-Pacific, Latin America, and the Middle East invest heavily in modernizing airports and increasing aircraft deliveries. It enables software providers to tap into new customer bases seeking efficient maintenance management solutions. Growing low-cost carriers and regional airlines in these markets further drive demand for cost-effective, scalable MRO software. Tailoring offerings to local regulatory requirements and language preferences can enhance adoption rates. This regional expansion supports long-term market growth and diversification. Capturing these emerging markets remains a strategic focus for industry players.
Leveraging Advanced Technologies to Develop Next-Generation Predictive Maintenance Solutions
The Aviation MRO Software Market presents opportunities to leverage advancements in artificial intelligence, machine learning, and big data analytics for next-generation predictive maintenance tools. It allows providers to offer highly accurate failure predictions and optimized maintenance schedules, improving aircraft availability and safety. Integration with augmented reality (AR) and virtual reality (VR) for technician training and remote assistance creates added value. These innovations can reduce costs and improve operational efficiency for airlines and MRO service providers. Collaborating with technology firms and investing in R\&D will accelerate development and adoption of cutting-edge software. Continuous innovation remains key to capitalizing on evolving customer needs and market potential.
Market Segmentation Analysis
By Solution
The Global Aviation MRO Software Market segments solutions into Software and Services categories. Software includes Enterprise Resource Planning (ERP) solutions, Point solutions, and Suites that cater to varied maintenance and operational needs. Services cover Deployment & Integration and Consulting, supporting seamless implementation and optimization of software platforms. ERP solutions dominate due to their comprehensive capabilities in managing complex aviation maintenance processes. Point solutions address specific tasks, while Suites offer integrated features. Services remain essential for ensuring software effectiveness and adapting solutions to client requirements. This segmentation reflects the diverse software offerings shaping market demand.
- For instance, a recent industry survey found that over 2,800 airlines and MRO providers worldwide had implemented ERP solutions for aviation maintenance, while more than 1,400 organizations reported using point solutions for specific operational needs.
By Function
The market segments functions into Maintenance Management, Operations Management, Business Management, and others. Maintenance Management covers Line, Base, Engine, and Fleet maintenance, focusing on core repair and upkeep activities. Operations Management includes Training, Safety & Quality Assurance, Supply Chain Management, and Engineering & Continuing Airworthiness Management Organization (CAMO). Business Management incorporates Accounts & Finance, Sales & Marketing, and Human Resources. Electronic Flightbag & Logbook Management also forms a critical functional segment. It addresses varied operational requirements, enabling comprehensive management across aviation workflows. Functional diversity supports tailored software adoption by different users.
- For instance, according to a 2024 aviation technology report, more than 3,500 aviation organizations globally use digital Maintenance Management modules, and over 2,000 have adopted Operations Management software for training and safety functions.
By Point of Sale
The Global Aviation MRO Software Market divides sales into Subscription and Ownership models. Subscription offers flexible, scalable access with lower upfront costs, appealing to airlines and MRO providers seeking operational agility. Ownership involves outright software purchases, preferred by organizations emphasizing long-term control and customization. Subscription models show faster growth due to cloud adoption and evolving business needs. This segmentation highlights changing procurement preferences influencing market dynamics.
By Deployment Type
Deployment types include On-premise and Cloud solutions. On-premise remains relevant for operators requiring direct control over data and infrastructure, often preferred by larger, established players. Cloud deployment gains traction for its scalability, cost efficiency, and remote accessibility. It supports real-time data sharing and collaborative maintenance management across geographically dispersed teams. Growth in cloud adoption drives innovation and market expansion. The choice of deployment depends on organizational priorities and regulatory constraints.
By End-use
End-use segments encompass Airline Operators, Maintenance, Repair, and Overhaul (MRO) providers, and Original Equipment Manufacturers (OEMs). Airline Operators demand software that optimizes fleet maintenance and operational efficiency. MROs focus on specialized maintenance services requiring robust software for complex workflows. OEMs leverage MRO software for asset tracking and aftermarket support. Each end-user group influences product development and market strategies. The diverse end-use landscape fuels sustained market growth.
Segments
Based on Solution
- Software
- Enterprise Resource Planning (ERP) Solution
- Point Solution
- Suite
- Services
- Deployment & Integration
- Consulting
Based on Function
- Maintenance Management
- Line Maintenance
- Base Maintenance
- Engine Maintenance
- Fleet Maintenance
- Operations Management
- Training, Safety & Quality Assurance
- Supply Chain Management
- Engineering & Continuing Airworthiness Management Organization (CAMO)
- Others
- Business Management
- Accounts & Finance
- Sales & Marketing
- Human Resources
- Electronic Flightbag & Logbook Management
Based on Point of Sale
- Subscription
- Ownership
Based on Deployment Type
- On-premise
- Cloud
Based on End-use
- Airline Operators
- MROs
- OEMs
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Aviation MRO Software Market
The North America region holds the largest share in the Aviation MRO Software Market, accounting for approximately 35% of the global market. The presence of major airline operators, advanced technological infrastructure, and stringent regulatory standards drive this dominance. It benefits from early adoption of innovative software solutions focused on predictive maintenance and operational efficiency. Strong investments in digital transformation and robust IT ecosystems further support market growth. The United States remains the key contributor due to its expansive aviation sector and leading MRO service providers. Growing demand for cloud-based and AI-enabled platforms continues to propel the region’s market expansion.
Europe Aviation MRO Software Market
Europe accounts for around 28% of the global Aviation MRO Software Market, supported by strict aviation safety regulations and environmental standards. Operators in this region prioritize compliance, driving adoption of software that ensures accurate maintenance documentation and traceability. It leverages cloud and AI technologies to enhance operational reliability and safety. Key markets include the United Kingdom, Germany, and France, where ongoing fleet modernization and digital transformation projects stimulate demand. Collaboration between regulatory bodies and technology vendors strengthens software adoption. The region exhibits consistent growth supported by innovation and regulatory pressure.
Asia-Pacific Aviation MRO Software Market
The Asia-Pacific region holds approximately 22% of the Aviation MRO Software Market, representing the fastest-growing regional segment. Rising air traffic volumes, expanding commercial fleets, and infrastructure development fuel demand for efficient MRO software. It attracts investments from both international and local software providers targeting emerging markets like China, India, and Southeast Asia. Increasing low-cost carrier operations and government initiatives to modernize aviation maintenance further support market growth. Cloud adoption and mobile-enabled solutions gain popularity among operators. This dynamic environment creates significant opportunities for market expansion.
Middle East & Africa Aviation MRO Software Market
The Middle East & Africa region contributes about 10% to the global Aviation MRO Software Market, driven by strategic investments in aviation infrastructure and fleet expansion. Countries such as the UAE and Saudi Arabia invest heavily in airport modernization and airline growth. It offers opportunities for software providers focusing on integrated maintenance and operational management solutions. The region benefits from growing international connectivity and rising passenger traffic. Emerging digital initiatives and partnerships with global technology firms boost software adoption. Market growth depends on continued infrastructure development and regulatory enhancements.
Latin America Aviation MRO Software Market
Latin America accounts for nearly 5% of the Aviation MRO Software Market, with increasing demand tied to fleet modernization and regional airline expansion. Operators focus on adopting advanced maintenance software to improve efficiency and comply with evolving regulations. It faces challenges related to infrastructure limitations and lower digital maturity compared to other regions. However, growing air travel and investments in aviation technology create opportunities for market penetration. Brazil and Mexico remain key markets driving regional growth. The potential for software adoption increases alongside industry modernization.
Key players
- AeroSoft Systems Inc. (Canada)
- ATP Inc. (U.S.)
- Aviation Intertec Services Inc. (Canada)
- CAMP Systems International Inc. (U.S.)
- Communications Software (Airline Systems) Limited (U.K.)
- GE Aviation (U.S.)
- HCL Technologies Limited (India)
- IBM Corporation (U.S.)
- IBS Software Pvt. Ltd. (India)
- IFS AB (Sweden)
- Jet Support Services Inc. (U.S.)
- Lufthansa Technik AG (Germany)
- Oracle Corporation (U.S.)
- Ramco Systems Limited (India)
- Rusada Group SA (Switzerland)
- SAP SE (Germany)
- Swiss AviationSoftware Ltd. (Switzerland)
- The Boeing Company (U.S.
Competitive Analysis
The Aviation MRO Software Market features intense competition among global technology providers and specialized aviation firms. Leading companies focus on innovation, enhancing software capabilities with AI, cloud computing, and predictive analytics to differentiate their offerings. It faces competition from both established players with extensive aviation expertise and emerging technology firms bringing digital transformation solutions. Strategic partnerships, mergers, and acquisitions remain common strategies to expand market share and geographic reach. Companies invest heavily in R\&D to address evolving regulatory requirements and customer demands for integrated, scalable platforms. The market’s competitive landscape encourages continuous product improvement and customization to suit diverse airline and MRO provider needs. Strong customer support and after-sales services also influence buyer preferences in this highly dynamic market.
Recent Developments
- In September 2024, Ramco Systems Limited launched Aviation Software 6.0, an AI-powered solution featuring enhanced automation and specialized engine MRO modules designed to transform maintenance and engineering workflows.
- In February 2025, GE Aviation (GE Aerospace) began deploying an AI-enabled inspection tool for aircraft engines to improve accuracy and consistency during maintenance inspections.
Market Concentration and Characteristics
The Aviation MRO Software Market exhibits a moderately concentrated structure, dominated by a mix of large multinational corporations and specialized niche providers. It features key players with strong technological capabilities and extensive industry experience, enabling them to deliver comprehensive solutions across diverse aviation segments. The market’s characteristics include continuous innovation, driven by increasing demand for digitalization, predictive maintenance, and cloud-based platforms. It experiences steady consolidation through partnerships and acquisitions to enhance product portfolios and geographic presence. Customer preference for integrated, customizable software with robust support services influences market dynamics. The competitive intensity encourages vendors to focus on scalability, security, and compliance features, addressing complex operational requirements. This balance between established firms and agile newcomers defines the market’s evolving landscape and growth potential.
Report Coverage
The research report offers an in-depth analysis based on Solution, Function, Point of Sale, Deployment Type, End-use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Aviation MRO Software Market is anticipated to expand from USD 8.13 billion in 2025 to USD 11.68 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.3% during the forecast period.
- Cloud-based MRO software solutions are gaining traction due to their scalability, cost-effectiveness, and real-time data access, facilitating efficient maintenance operations across geographically dispersed teams.
- The incorporation of artificial intelligence (AI), machine learning (ML), and Internet of Things (IoT) technologies into MRO software enhances predictive maintenance capabilities, leading to reduced downtime and optimized asset utilization.
- Stringent aviation safety regulations drive the adoption of MRO software solutions that ensure compliance through automated tracking of maintenance activities, audit trails, and reporting features.
- Subscription-based MRO software models are becoming more prevalent, offering flexibility and lower upfront costs for airlines and MRO providers, thereby accelerating software adoption.
- Emerging markets, particularly in the Asia-Pacific region, are experiencing rapid growth in air travel and fleet expansion, driving the demand for advanced MRO software solutions to manage maintenance operations efficiently.
- With the increasing digitalization of MRO operations, there is a heightened focus on implementing robust cybersecurity measures to protect sensitive data and ensure the integrity of maintenance processes.
- The market is witnessing consolidation through mergers and acquisitions, as well as strategic partnerships among software providers, airlines, and MRO service providers, aiming to enhance service offerings and expand market reach.
- MRO software solutions are increasingly being customized to meet the specific needs of different end-users, including airline operators, MROs, and OEMs, ensuring tailored functionalities and improved user experience
- Sustainability initiatives within the aviation industry are encouraging the development of MRO software solutions that support eco-friendly practices, such as reducing carbon emissions and optimizing fuel consumption
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Operational Efficiency and Cost Reduction
Airlines and MRO providers are increasingly adopting MRO software to optimize maintenance schedules, minimize aircraft downtime, and reduce labor and material costs, directly improving profitability and competitiveness.
Adoption of Advanced Technologies for Predictive Maintenance
Integration of AI, machine learning, and IoT into MRO software enables real-time monitoring and predictive analytics, allowing operators to anticipate failures, reduce unplanned maintenance, and extend asset life.
Stringent Regulatory Compliance and Safety Standards
Aviation authorities require comprehensive maintenance documentation and traceability, driving the adoption of MRO software that automates compliance, audit trails, and reporting to avoid penalties and support certification.
Expansion of Global Air Travel and Fleet Modernization
Rising passenger volumes and the growth of commercial and military aircraft fleets, especially in emerging markets, necessitate advanced software solutions to efficiently manage larger, more complex maintenance operations.
Shift Toward Cloud-Based and Subscription Models
The move to cloud-based platforms and subscription pricing provides scalability, real-time data access, and lower upfront costs, making advanced MRO software more accessible and attractive to a broader range of operators.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Aviation MRO Software Market in 2023, and what is its expected size by 2032?
What are the primary drivers fueling growth in the Aviation MRO Software Market?
Which regions dominate the Aviation MRO Software Market geographically?
Who are some key players in the Aviation MRO Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Airline Operators
- 1.2.2 MROs
- 1.2.3 OEMs
- 1.3 By Solution
- 1.3.1 Enterprise Resource Planning (ERP) Solution
- 1.3.2 Point Solution
- 1.3.3 Suite
- 1.3.4 Deployment & Integration
- 1.3.5 Consulting
- 1.4 By Point of Sale
- 1.4.1 Subscription
- 1.4.2 Ownership
- 1.5 By Deployment Type
- 1.5.1 On-premise
- 1.5.2 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,412 million → 2032: USD 10,222 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aviation MRO Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aviation MRO Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Aviation MRO Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Aviation MRO Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aviation MRO Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aviation MRO Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aviation MRO Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aviation MRO Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,412 million → 2032: USD 10,222 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aviation MRO Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Airline Operators
- 12.3.6.2 MROs
- 12.3.6.3 OEMs
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Enterprise Resource Planning (ERP) Solution
- 12.4.6.2 Point Solution
- 12.4.6.3 Suite
- 12.4.6.4 Deployment & Integration
- 12.4.6.5 Consulting
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Point of Sale - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Subscription
- 12.5.6.2 Ownership
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 On-premise
- 12.6.6.2 Cloud
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aviation MRO Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aviation MRO Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aviation MRO Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aviation MRO Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 Ramco Systems Limited
- 18.5 IFS AB
- 18.6 GE Aviation
- 18.7 Oracle Corporation
- 18.8 Lufthansa Technik AG
- 18.9 Swiss AviationSoftware Ltd.
- 18.10 SAP SE
- 18.11 ATP Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

