
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Body Worn Temperature Sensors Market Size 2024 | USD 76.4 Million |
| Body Worn Temperature Sensors Market, CAGR | 24.02% |
| Body Worn Temperature Sensors Market Size 2032 | USD 427.58 Million |
Market Overview
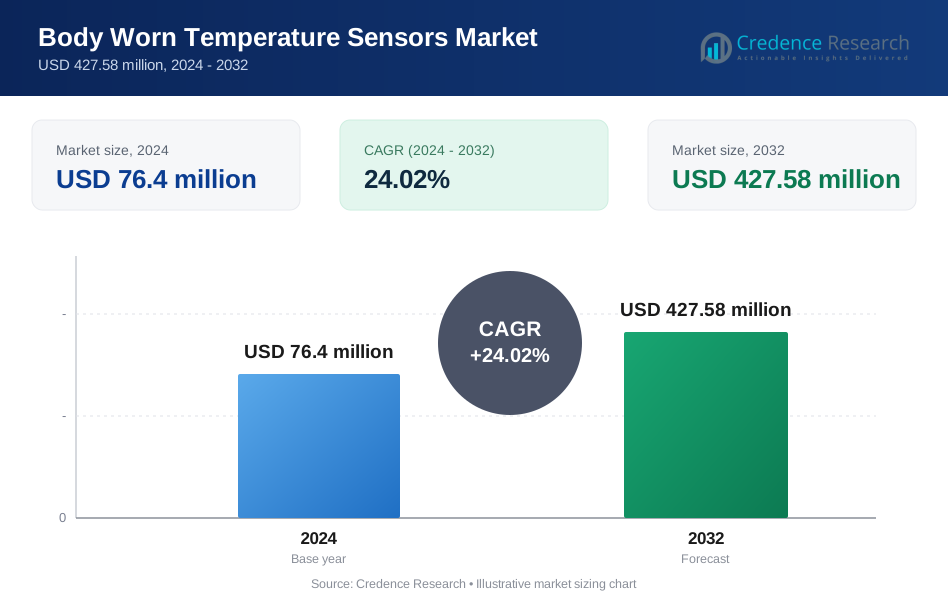
The market for body-worn temperature sensors is projected to grow significantly from USD 76.4 million in 2024 to USD 427.58 million by 2032, reflecting a compound annual growth rate (CAGR) of 24.02%.
The body-worn temperature sensors market is driven by the increasing demand for remote patient monitoring and the rise of telehealth services. Technological advancements, such as miniaturization and enhanced connectivity, enable these sensors to provide accurate real-time data, improving patient outcomes. Furthermore, the growing focus on personal health and wellness, coupled with the rising prevalence of chronic diseases, propels market growth. The trend toward wearable health technology, driven by consumer preferences for convenience and efficiency, also contributes significantly to the expansion of this market, fostering innovation and new product developments in the field.
The geographical analysis of the body-worn temperature sensors market reveals significant growth across regions, particularly in North America and Asia-Pacific. North America leads the market due to advanced healthcare infrastructure and high technology adoption rates. In contrast, Asia-Pacific experiences rapid expansion driven by rising health awareness and chronic disease prevalence. Key players in this market include Panasonic Corporation, Texas Instruments Inc., Infineon Technologies AG, and General Electric Company, which are at the forefront of innovation and development. Other notable companies, such as Sensirion AG and Siemens, are also contributing to the competitive landscape, enhancing product offerings and market presence.
Market Drivers
Advancements in Technology
Technological innovations are significantly driving the body-worn temperature sensors market. Miniaturization has led to the development of smaller, more discreet sensors that enhance comfort and wearability for users. Improved accuracy in temperature measurements results from advanced sensor technologies, ensuring reliable data collection. For instance, MIT researchers have developed a way to incorporate electronic sensors into stretchy fabrics, allowing them to create shirts or other garments that could be used to monitor vital signs such as temperature, respiration, and heart rate. Additionally, wireless connectivity allows for real-time data transmission, enabling remote monitoring and immediate access to critical health information. These technological advancements not only enhance user experience but also contribute to the effectiveness of health monitoring.
Rising Healthcare Needs
The increasing demand for remote patient monitoring highlights the growing relevance of body-worn temperature sensors in healthcare. These devices are particularly valuable for monitoring patients with chronic conditions or those recovering from illnesses, facilitating better management of their health. For instance, a pilot study demonstrated that wrist-worn sensors could continuously monitor core body temperature in a free-living setting, showing good correlation to reference measurements. Continuous temperature monitoring can aid in the early detection of potential health issues, allowing for timely intervention. Furthermore, real-time data empowers healthcare providers to make informed decisions regarding patient treatment, ultimately improving overall patient care and outcomes.
Growing Demand for Wearable Devices
The rising consumer adoption of wearable devices is further propelling the body-worn temperature sensors market. Health-conscious individuals increasingly seek fitness and wellness solutions that track various health metrics, including body temperature. Smartwatches and fitness bands often incorporate these temperature sensors, offering users a comprehensive view of their health. As consumer awareness of health and wellness continues to rise, the demand for wearable technology that includes temperature monitoring is expected to grow significantly.
Increasing Focus on Preventive Healthcare
A growing emphasis on preventive healthcare is driving the adoption of body-worn temperature sensors. These devices empower individuals to take a proactive approach to their health by facilitating continuous monitoring. Early detection and intervention through temperature data can help prevent serious health complications, leading to improved quality of life. Moreover, the applications of body-worn temperature sensors are expanding beyond healthcare, with potential uses in industrial safety, workplace wellness, and sports performance, further enhancing their market potential.
Market Trends
Miniaturization and Improved Accuracy
The body-worn temperature sensors market is witnessing significant advancements in technology, particularly concerning miniaturization and enhanced accuracy. Sensors are becoming increasingly compact and discreet, providing users with a comfortable experience while ensuring effective monitoring. For instance, advancements in wireless sensor networks and miniaturization of sensors have led to the emergence of body sensor networks (BSNs), which are now widely used in healthcare applications. This miniaturization trend not only improves wearability but also allows for integration into various types of wearable devices. Alongside size reduction, technological innovations have led to enhanced accuracy in temperature measurements, ensuring reliable and precise data collection. Wireless connectivity, utilizing Bluetooth and other technologies, enables real-time data transmission to smartphones or other devices, facilitating immediate access to health metrics. This seamless connectivity enhances user engagement and empowers individuals to monitor their health actively, marking a notable shift toward more proactive health management.
Integration with Wearable Devices and Expanding Applications
The integration of body-worn temperature sensors into smartwatches and fitness trackers is transforming the landscape of health monitoring. These wearable devices now track various health metrics, including body temperature, heart rate, and sleep patterns, catering to the increasing consumer demand for comprehensive health insights. As individuals seek to monitor their overall health and fitness, wearable technology becomes an essential tool in their daily lives. Furthermore, the applications of these sensors are expanding beyond traditional healthcare settings. In industrial environments, temperature sensors can monitor workers in hazardous conditions, enhancing safety and risk management. In the sports and fitness sectors, athletes utilize these sensors to track performance and prevent injuries, ensuring optimal training. Moreover, military and law enforcement agencies are adopting these technologies for health monitoring and situational awareness. The growing awareness among consumers regarding health and wellness underscores the importance of preventive care, leading to increased demand for body-worn temperature sensors as individuals aim to take a proactive approach to their health. As these technologies continue to evolve and integrate into everyday devices, they hold immense potential for improving health outcomes across various sectors.
Market Challenges Analysis
Accuracy and Reliability Challenges
The effectiveness of body-worn temperature sensors is significantly influenced by challenges related to accuracy and reliability. Environmental factors such as humidity, temperature fluctuations, and electromagnetic interference can adversely impact sensor readings, leading to potential inaccuracies. For instance, a study conducted by the National Institute of Standards and Technology (NIST) found that electromagnetic interference from common household devices can cause deviations in sensor readings. Additionally, individual variations in skin temperature and body composition can further complicate the accuracy of measurements, resulting in inconsistent data. To mitigate these issues, proper calibration of sensors is essential to ensure reliable performance. However, achieving accurate calibration can be a complex and time-consuming process. These accuracy challenges necessitate ongoing research and development efforts to enhance sensor technology and address the limitations posed by external and individual factors.
User Comfort and Regulatory Hurdles
User comfort and acceptance are critical barriers to the widespread adoption of body-worn temperature sensors. Many users report discomfort or find the sensors intrusive, which can deter them from consistent usage. Moreover, the limited battery life of some devices can hinder continuous monitoring, prompting users to recharge or replace batteries frequently. Data privacy concerns also play a significant role, as users may be hesitant to adopt these technologies due to fears about the security of their personal health information. Additionally, regulatory hurdles present challenges in the development and marketing of body-worn temperature sensors. Compliance with strict medical device regulations can be a time-consuming and costly process, particularly in ensuring adherence to data security standards. Furthermore, interoperability and standardization issues pose significant obstacles; compatibility problems between different sensors and devices can impede data sharing and analysis, while a lack of standardized protocols limits the potential for widespread integration. Together, these challenges highlight the need for continuous improvements in technology, consumer education, and regulatory frameworks to foster greater acceptance and effective implementation of body-worn temperature sensors in healthcare and beyond.
Market Segmentation Analysis:
By Type:
The body-worn temperature sensors market is segmented into various types, including biosensors, smartwatches, smart clothing, wearable patches, hand-worn terminals, and others. Biosensors are highly popular due to their ability to provide accurate and real-time monitoring of vital signs, including temperature. Smartwatches and smart clothing are also gaining traction, as they seamlessly integrate temperature sensors with other health-tracking features like heart rate and fitness metrics, offering users comprehensive wellness solutions. Wearable patches, known for their ease of use and comfort, are widely adopted in healthcare settings. Hand-worn terminals, though less common, are utilized in specific industrial and military applications where real-time monitoring is essential. Other emerging types include innovative wearable devices designed to enhance user comfort and adaptability across various sectors.
By Application The application of body-worn temperature sensors spans across multiple industries, including healthcare and medical, industrial and military, telecommunications, information technology, and others. In healthcare, these sensors are critical for remote patient monitoring, chronic disease management, and preventive care, driving significant demand in this segment. The industrial and military sectors leverage temperature sensors for worker safety and operational efficiency, particularly in hazardous environments. In telecommunications and information technology, these sensors are being integrated into devices to enhance user experience and monitor health parameters in real-time. Expanding applications in other sectors, such as sports and wellness, are also contributing to the growing adoption of body-worn temperature sensors, reflecting their versatility across diverse markets.
Segments:
Based on Type:
- Biosensors
- Smart Watch
- Smart Clothing
- Wearable Patches
- Hand worn Terminals
- Others
Based on Application:
- Healthcare and medical
- Industrial and Military
- Telecommunication
- Information Technology
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the body-worn temperature sensors market, accounting for approximately 35% of the total market share. The region's robust healthcare infrastructure, coupled with a high adoption rate of advanced medical technologies, drives the demand for innovative health monitoring solutions. For instance, the increasing adoption of smartwatches, fitness bands, and wearable medical monitoring devices in the United States and Canada has significantly contributed to market growth. Increased focus on remote patient monitoring, particularly in the wake of the COVID-19 pandemic, has further accelerated market growth in this region. Additionally, major players in the United States and Canada are investing heavily in research and development to enhance sensor accuracy and integration with wearable devices. The presence of well-established technology firms also fosters a competitive landscape that promotes innovation in body-worn temperature sensors, catering to both consumer and medical needs.
Asia-Pacific The Asia-Pacific region is experiencing rapid growth in the body-worn temperature sensors market, with a market share of approximately 30%. This growth can be attributed to the rising prevalence of chronic diseases and an increasing aging population, leading to a greater demand for effective health monitoring solutions. Countries like China, India, and Japan are at the forefront of this growth, driven by advancements in wearable technology and increasing health awareness among consumers. Additionally, the region's expanding healthcare sector and government initiatives promoting telehealth services further support market expansion. As manufacturers focus on developing cost-effective and user-friendly products, the Asia-Pacific region is expected to witness significant advancements in body-worn temperature sensors, contributing to its growing market share.
Key Player Analysis
- Dexter Research Center
- Infineon Technologies AG
- Sensirion AG Switzerland
- Siemens
- Measurement Specialties Inc.
- Panasonic Corporation
- Freescale Semiconductor Inc.
- Texas Instruments Inc.
- General Electric Company
- Heimann Sensor GmbH
Competitive Analysis
The competitive landscape of the body-worn temperature sensors market features several leading players, including Panasonic Corporation, Texas Instruments Inc., Infineon Technologies AG, General Electric Company, and Sensirion AG. These companies are heavily invested in research and development to enhance the accuracy and reliability of their products. Focus areas include miniaturization and integration with existing health monitoring systems, alongside improvements in wireless connectivity and energy efficiency. The emphasis on advanced sensor technology allows for high-precision temperature measurements suitable for various applications, including healthcare, fitness, and industrial use. As competition intensifies, many players are pursuing strategic partnerships and collaborations to enhance their market presence, expand product portfolios, and address the growing demand for innovative body-worn temperature monitoring solutions across multiple industries. This dynamic environment fosters innovation and encourages the development of user-friendly devices that cater to diverse consumer needs.
Recent Developments
- In June 2024, Infineon introduced the 600 V CoolMOS™ S7TA MOSFETs featuring an integrated high-precision temperature sensor.
- In August 2024, Sensirion launched their most cost-efficient temperature sensor to date, the STS4L, which is part of the STS4x temperature sensor series.
Market Concentration & Characteristics
The market concentration for body-worn temperature sensors is characterized by a mix of established players and emerging startups, creating a competitive yet dynamic landscape. While several leading companies dominate the market with significant market shares, the entry of new players enhances innovation and diversifies product offerings. Key characteristics of this market include rapid technological advancements, particularly in sensor accuracy, miniaturization, and wireless connectivity, which are essential for meeting consumer demands. The market is also marked by a strong focus on research and development, as companies strive to create user-friendly, integrated solutions that cater to various applications, from healthcare to fitness and industrial safety. Additionally, regulatory compliance and data security are critical considerations that influence product development and market strategies. As consumer awareness of health and wellness continues to rise, the demand for body-worn temperature sensors is expected to grow, further intensifying competition and market concentration in the coming years.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The body-worn temperature sensors market is expected to experience substantial growth driven by rising health awareness and the demand for remote monitoring solutions.
- Advancements in sensor technology will lead to improved accuracy and reliability, enhancing user confidence in these devices.
- Integration with smart devices and health apps will facilitate seamless data tracking and analysis for users.
- The trend toward telehealth and remote patient monitoring will significantly boost demand for body-worn sensors, especially in chronic disease management.
- Increased consumer interest in fitness and wellness will promote the adoption of wearable technology, including temperature sensors.
- Ongoing research and development will focus on miniaturization, making sensors more discreet and comfortable for everyday use.
- The market will likely see a rise in strategic partnerships and collaborations to drive innovation and expand product offerings.
- Regulatory compliance and data security measures will remain critical to building trust among consumers and healthcare providers.
- Emerging markets in Asia-Pacific will offer new growth opportunities due to increasing healthcare spending and technology adoption.
- The development of AI-driven analytics will enhance the capability of body-worn temperature sensors to provide actionable health insights.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Technology
Ongoing innovations such as miniaturization, improved sensor accuracy, and enhanced wireless connectivity are making body-worn temperature sensors more comfortable, reliable, and suitable for continuous health monitoring, thus expanding their adoption.
Rising Healthcare Needs
The increasing prevalence of chronic diseases and the need for remote patient monitoring are driving healthcare providers and patients to adopt body-worn temperature sensors for real-time, continuous health data, improving patient outcomes and enabling timely interventions.
Growing Demand for Wearable Devices
Consumer interest in fitness, wellness, and proactive health management is fueling the integration of temperature sensors into popular wearables like smartwatches and fitness bands, broadening the market’s reach beyond clinical settings.
Increasing Focus on Preventive Healthcare
A shift toward preventive healthcare is encouraging individuals and organizations to use body-worn temperature sensors for early detection of health anomalies, reducing the risk of severe complications and supporting workplace and athletic safety.
Expansion of Telehealth and Remote Monitoring
The rise of telehealth services and remote monitoring solutions, especially post-pandemic, has accelerated the adoption of body-worn temperature sensors as essential tools for continuous, remote patient assessment and care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Body Worn Temperature Sensors market?
What factors are driving the growth of the Body Worn Temperature Sensors?
What are the key segments within the Body Worn Temperature Sensors?
What are some challenges faced by the Body Worn Temperature Sensors?
Who are the major players in the Body Worn Temperature Sensors?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Biosensors
- 1.2.2 Smart Watch
- 1.2.3 Smart Clothing
- 1.2.4 Wearable Patches
- 1.2.5 Hand worn Terminals
- 1.2.6 Others
- 1.3 By Application
- 1.3.1 Healthcare and Medical
- 1.3.2 Industrial and Military
- 1.3.3 Telecommunication
- 1.3.4 Information Technology
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 76.4 million → 2032: USD 427.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Body Worn Temperature Sensors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Body Worn Temperature Sensors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Body Worn Temperature Sensors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Body Worn Temperature Sensors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Body Worn Temperature Sensors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Body Worn Temperature Sensors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Body Worn Temperature Sensors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Body Worn Temperature Sensors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 76.4 million → 2032: USD 427.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Body Worn Temperature Sensors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Biosensors
- 12.3.7.2 Smart Watch
- 12.3.7.3 Smart Clothing
- 12.3.7.4 Wearable Patches
- 12.3.7.5 Hand worn Terminals
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Healthcare and Medical
- 12.4.7.2 Industrial and Military
- 12.4.7.3 Telecommunication
- 12.4.7.4 Information Technology
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Body Worn Temperature Sensors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Body Worn Temperature Sensors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Body Worn Temperature Sensors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Body Worn Temperature Sensors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Panasonic Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Texas Instruments Inc.
- 18.4 Infineon Technologies AG
- 18.5 General Electric Company
- 18.6 Sensirion AG
- 18.7 Siemens
- 18.8 Dexter Research Center
- 18.9 Measurement Specialties Inc.
- 18.10 Freescale Semiconductor Inc.
- 18.11 Heimann Sensor GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

