
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Brazil Cardiovascular Devices Market Size 2024 | USD 2,029.76 million |
| Brazil Cardiovascular Devices Market , CAGR | 6.6% |
| Brazil Cardiovascular Devices Market Size 2032 | USD 3,604.54 million |
Market Overview
The Brazil Cardiovascular Devices Market is projected to grow from USD 2,029.76 million in 2024 to an estimated USD 3,604.54 million based on 2032, with a compound annual growth rate (CAGR) of 6.6% from 2025 to 2032. This growth reflects a rising burden of cardiovascular diseases (CVDs), increased healthcare expenditure, and greater demand for advanced diagnostic and therapeutic technologies.
Key drivers of the Brazil cardiovascular devices market include the rising prevalence of chronic heart conditions and the increasing adoption of minimally invasive procedures. Advances in medical technology, such as AI-integrated monitoring systems and next-generation imaging techniques, are enhancing the precision and efficacy of cardiovascular diagnostics and treatments. Furthermore, national initiatives promoting preventive healthcare and early screening are fostering awareness and driving demand for innovative cardiovascular solutions.
Geographically, the southeastern region of Brazil, which includes major urban centers like São Paulo and Rio de Janeiro, holds a dominant share due to its advanced healthcare infrastructure and high patient volumes. Northern and northeastern regions are gradually catching up through government-led healthcare expansion programs. Prominent market players in Brazil include Medtronic, Boston Scientific, Abbott Laboratories, GE Healthcare, and Siemens Healthineers, each contributing to technological innovation and product availability across the cardiovascular care spectrum.
Market Insights
- The Brazil cardiovascular devices market is projected to grow from USD2,029.76 million in 2024 to USD3,604.54 million by 2032, registering a CAGR of 6.6% from 2025 to 2032.
- The global cardiovascular devices market is projected to grow from USD 72,115.60 million in 2024 to USD 133,700.94 million by 2032, with a CAGR of 7.1% from 2025 to 2032, driven by increasing cardiovascular diseases and advancements in medical technology.
- An aging population and rising prevalence of lifestyle-related conditions such as hypertension, obesity, and diabetes are driving the demand for cardiovascular interventions.
- Innovations in minimally invasive procedures, AI-enabled monitoring systems, and next-gen imaging tools are enhancing the efficiency of cardiovascular diagnosis and treatment.
- Increased government support and private sector investment in healthcare infrastructure are expanding access to advanced cardiovascular care across Brazil.
- High device costs, limited reimbursement for advanced technologies, and uneven distribution of cardiac care facilities remain key barriers to market expansion.
- The Southeast region, led by São Paulo and Rio de Janeiro, accounts for the largest market share due to superior infrastructure and specialist availability.
- Northern and Northeastern regions are gradually improving cardiovascular care capacity, supported by public health initiatives and telemedicine integration.
Report Scope
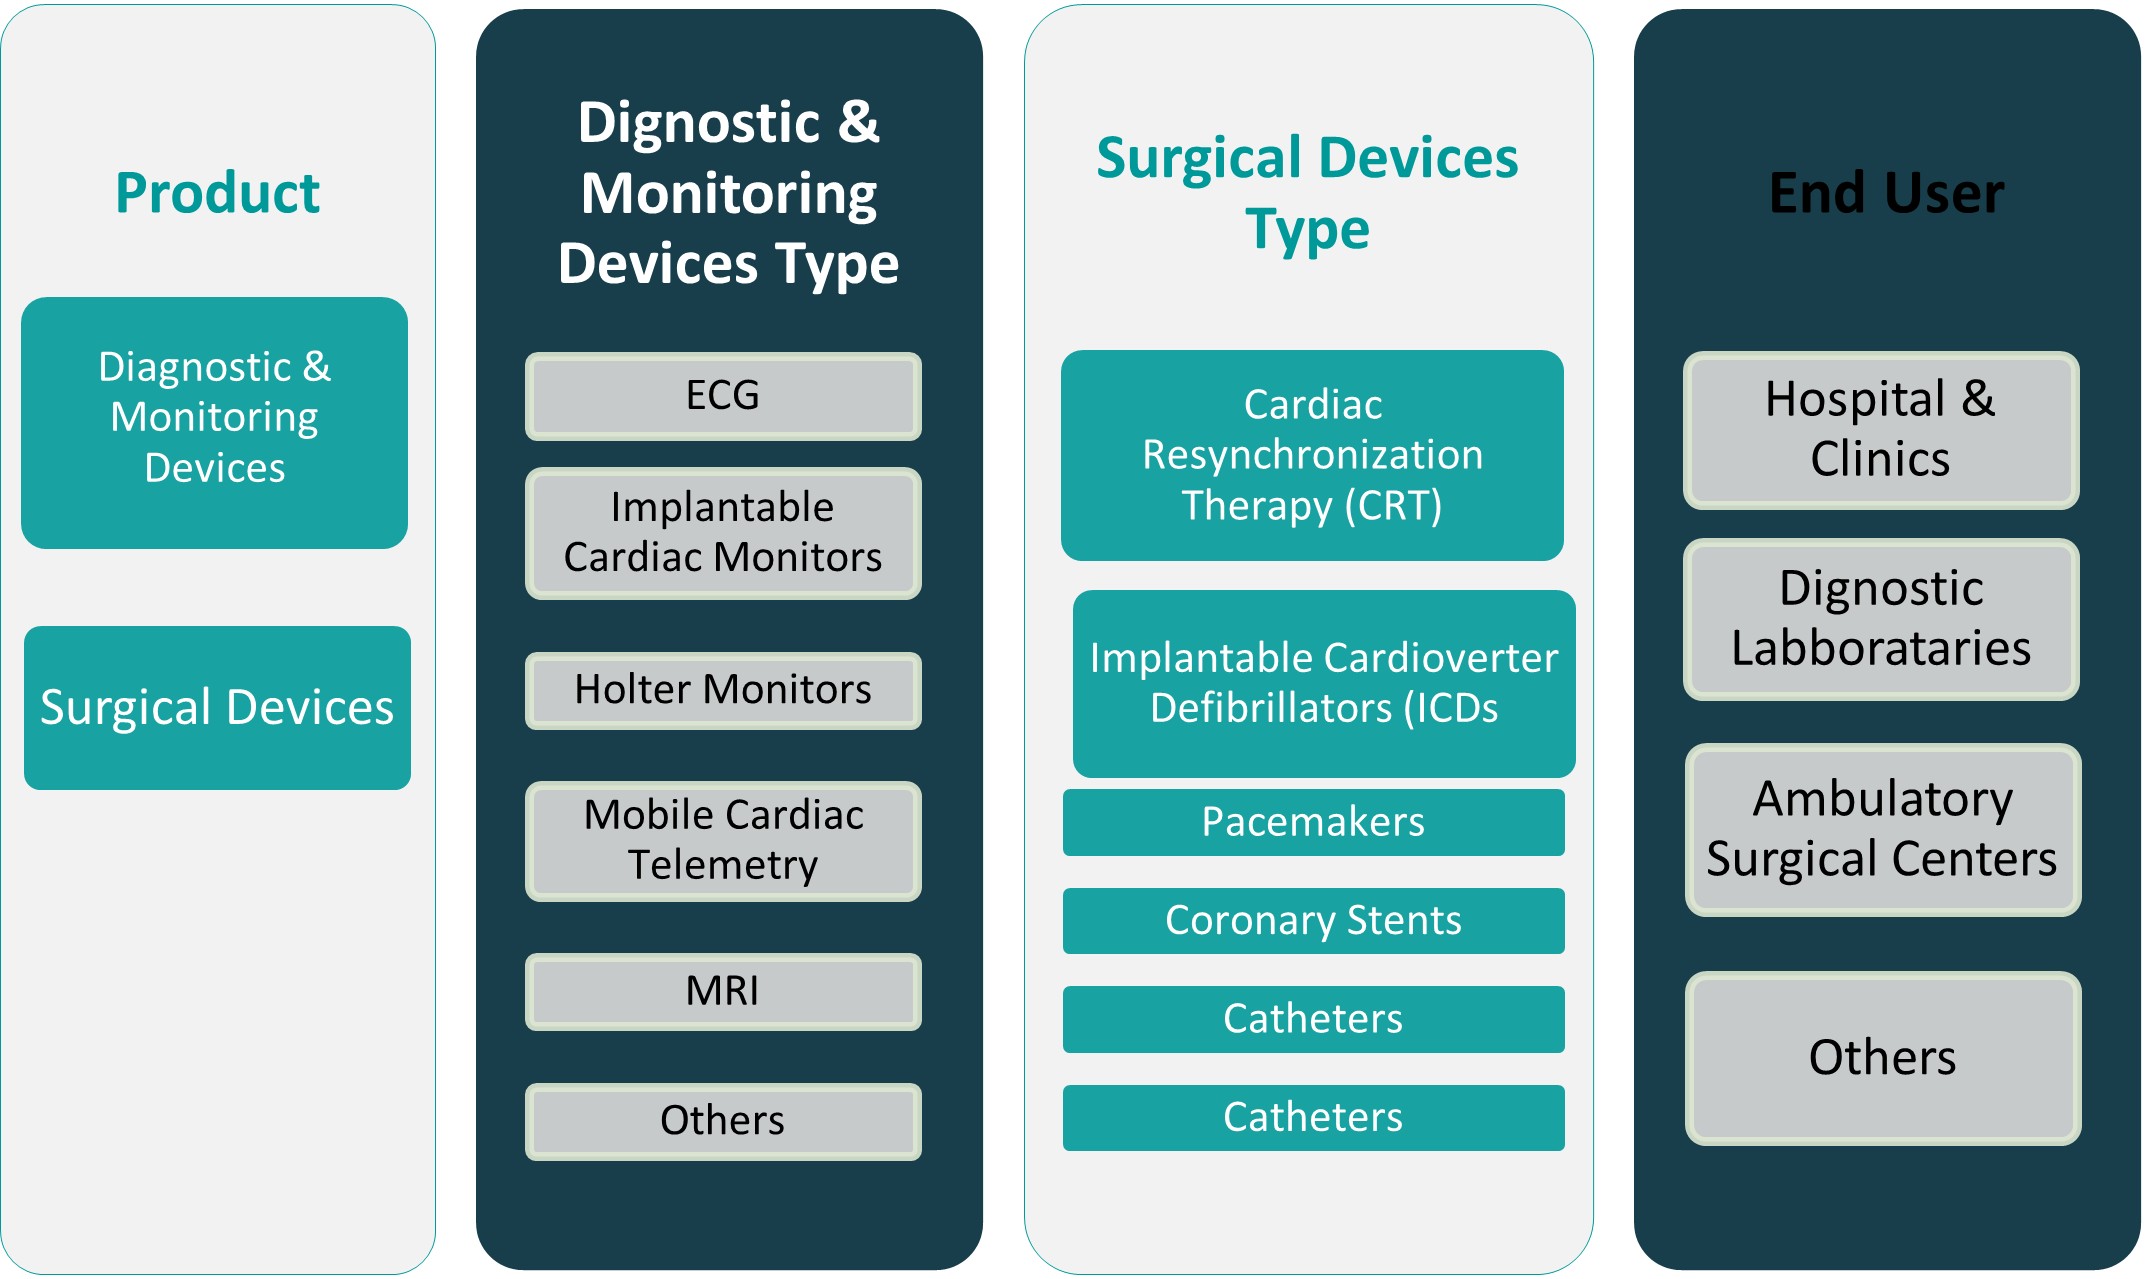
This report segments the Brazil Cardiovascular Devices Market as follows:
Market Drivers
Rising Prevalence of Cardiovascular Diseases and Lifestyle-Related Disorders
The most significant driver propelling the growth of the Brazil cardiovascular devices market is the rising incidence of cardiovascular diseases (CVDs), including coronary artery disease, heart failure, arrhythmias, and stroke. These conditions have become a major public health burden in Brazil, responsible for a substantial share of the country’s morbidity and mortality. For instance, according to the Brazilian Society of Cardiology, cardiovascular diseases accounted for approximately 400,000 deaths in Brazil in 2023, making them the leading cause of mortality in the country. Additionally, data from the World Heart Federation indicates that 31% of all deaths in Brazil are attributed to CVDs. Contributing to this trend are various modifiable lifestyle factors such as poor diet, physical inactivity, tobacco use, and excessive alcohol consumption, all of which are increasingly common among the Brazilian population. In addition, the growing prevalence of comorbidities like hypertension, diabetes, and obesity-especially among the aging demographic-further escalates the risk of cardiovascular events, thereby intensifying the demand for both interventional and diagnostic cardiovascular devices. As cardiovascular diseases require ongoing monitoring, surgical intervention, and rehabilitative support, the demand for devices such as implantable cardioverter defibrillators (ICDs), pacemakers, stents, and catheter-based therapies has seen a consistent uptick. This increasing disease burden is compelling hospitals, cardiology centers, and private practitioners to invest in technologically advanced and reliable cardiovascular devices, creating sustained market momentum.
Expanding Healthcare Infrastructure and Access to Advanced Medical Technologies
Brazil’s healthcare sector has undergone considerable transformation over the past decade, particularly with the expansion of both public and private healthcare infrastructure. The Unified Health System (SUS) has significantly improved access to basic and specialized medical services in urban and semi-urban areas. Investments by private hospitals and clinics in technologically advanced equipment have contributed to an enhanced quality of cardiac care across the country. For instance, tertiary care centers in metropolitan cities such as São Paulo, Rio de Janeiro, and Belo Horizonte are increasingly equipped with state-of-the-art diagnostic imaging systems, catheterization labs, electrophysiology units, and robotic-assisted surgical suites. Brazil has also seen advancements in AI-driven cardiac imaging, wearable ECG monitors, and remote patient monitoring devices, which are improving early detection and personalized treatment strategies. The adoption of minimally invasive cardiovascular procedures, including transcatheter heart valves and advanced stents, is reducing recovery times and improving patient outcomes. Alongside infrastructure development, there is a growing emphasis on physician training and education, which has further improved the proficiency and adoption of cardiovascular interventions. In addition, favorable reimbursement policies for certain cardiac procedures have made treatments more accessible to a larger segment of the population, contributing to increased utilization of cardiovascular devices.
Technological Advancements and Innovation in Cardiovascular Devices
Innovation in cardiovascular technology plays a pivotal role in shaping market dynamics in Brazil. The country has witnessed a notable increase in the adoption of minimally invasive and image-guided interventional procedures, which are preferred over conventional surgeries due to reduced hospital stays, lower procedural risks, and quicker recovery times. Breakthroughs in bioresorbable stents, leadless pacemakers, wearable cardiac monitors, and AI-powered diagnostic tools are revolutionizing the standard of care. These advanced devices enable real-time monitoring of heart rhythms, early detection of abnormalities, and personalized treatment planning, thus improving patient outcomes. Additionally, remote monitoring systems and telecardiology solutions are gaining traction, especially in underserved and rural areas where access to specialty care is limited. The availability of next-generation devices that offer improved efficacy, durability, and safety profiles is encouraging cardiologists to adopt cutting-edge solutions for complex conditions. The integration of digital health platforms and machine learning algorithms into diagnostic devices is further enhancing precision medicine and predictive analytics within the cardiovascular care domain in Brazil.
Supportive Government Initiatives and Growing Public Awareness
The Brazilian government and non-governmental organizations (NGOs) have initiated several programs aimed at reducing the incidence of cardiovascular diseases through preventive healthcare and public awareness campaigns. National policies promoting early screening, risk assessment, and lifestyle modification-such as campaigns for smoking cessation, healthy eating, and physical activity-are gaining ground. Government-backed programs also focus on increasing the availability of cardiovascular drugs and devices through subsidized pricing and public procurement. Furthermore, collaborative research initiatives with international medical device manufacturers are helping accelerate technology transfer and local production of devices, thereby reducing dependence on imports and lowering costs. Public awareness campaigns regarding the symptoms and risks of heart disease have led to a higher rate of early diagnosis and timely treatment, directly boosting the demand for cardiovascular diagnostic devices like ECG machines, portable ultrasounds, and Holter monitors. As the general population becomes more health-conscious and proactive in managing cardiac risk factors, the utilization of preventive and therapeutic cardiovascular devices is expected to rise substantially, reinforcing the long-term growth prospects of the market.
Market Trends
Surge in Minimally Invasive Cardiovascular Procedures
Minimally invasive cardiovascular procedures are witnessing a significant rise in adoption across Brazil due to their clinical efficacy, reduced recovery times, and cost-effectiveness. Hospitals and private cardiac centers increasingly prefer interventions such as percutaneous coronary interventions (PCI), transcatheter aortic valve replacements (TAVR), and electrophysiology-based ablations over traditional open-heart surgeries. These procedures require advanced imaging, catheterization, and device deployment technologies, thereby accelerating demand for high-precision cardiovascular devices. Patients, especially the elderly, are showing a preference for minimally invasive options due to lower procedural risk and shorter hospital stays. For instance, the Brazilian Registry of Adult Patients Undergoing Cardiovascular Surgery reported that 54.1% of patients underwent coronary artery bypass surgery, while 31.5% underwent valve surgery, highlighting the increasing preference for advanced interventions. Moreover, the Brazilian medical community continues to receive training in advanced interventional cardiology techniques, supported by collaborations with global manufacturers and academic institutions. This shift also aligns with the broader global trend toward value-based care, where outcomes and cost savings play a vital role. The introduction of next-generation stents, drug-eluting balloons, and leadless pacemakers further reinforces this trend. As the government and private sector continue investing in cath labs and hybrid operating rooms, the uptake of minimally invasive cardiovascular solutions is expected to grow steadily, reshaping the procedural landscape of cardiac care in Brazil. For instance, University Hospital São Paulo has expanded its interventional cardiology department, increasing access to minimally invasive procedures.
Integration of Digital Health and Remote Cardiac Monitoring Solutions
The integration of digital health technologies and remote cardiac monitoring is transforming cardiovascular care delivery in Brazil. With increasing mobile and internet penetration, coupled with rising patient awareness, there has been a notable shift toward telemedicine and wearable monitoring solutions. Devices such as smartwatches with ECG capabilities, remote Holter monitors, and wireless blood pressure monitors are gaining traction among both physicians and patients for real-time monitoring of cardiovascular parameters. These technologies enable early detection of arrhythmias, ischemic events, and heart failure symptoms, significantly reducing hospital readmissions and improving long-term patient outcomes. Hospitals are increasingly deploying centralized remote monitoring platforms that allow cardiologists to assess patients in real time and adjust treatment protocols accordingly. Additionally, integration with electronic health records (EHRs) and AI-driven analytics tools is streamlining diagnostics and enhancing predictive care. These systems are particularly beneficial in rural or underserved regions, where access to cardiology specialists is limited. The Brazilian government’s support for telehealth infrastructure and private sector investments in digital platforms are accelerating this trend. As the demand for personalized, preventive cardiac care rises, remote monitoring technologies are expected to become a cornerstone of Brazil’s cardiovascular health ecosystem.
Rising Local Manufacturing and Regulatory Streamlining for Medical Devices
Brazil is increasingly focusing on boosting domestic manufacturing of cardiovascular devices and streamlining its regulatory processes to reduce dependency on imports. Historically, the country relied heavily on imported cardiovascular products, resulting in higher costs and limited accessibility in remote regions. However, recent shifts in healthcare policy and industrial strategy are encouraging local production of essential medical devices such as stents, catheters, pacemakers, and diagnostic equipment. Regulatory reforms by the National Health Surveillance Agency (ANVISA) have made product approval and market entry more efficient, fostering innovation and accelerating time-to-market for both domestic and international manufacturers operating within Brazil. Moreover, tax incentives, public-private partnerships, and government support for technology transfer agreements are fostering collaboration between local companies and global medtech firms. This has not only led to cost reductions but also improved supply chain resilience. Increased localization is also allowing customization of products to better suit Brazilian patient demographics and care settings. As domestic manufacturers grow in capability and reputation, Brazil is poised to become a regional hub for cardiovascular device production, enhancing market competitiveness and improving access to life-saving technologies across all tiers of its healthcare system.
Emphasis on Preventive Cardiology and Early Diagnosis Tools
A growing focus on preventive cardiology and early-stage diagnosis is reshaping the cardiovascular devices market in Brazil. Healthcare providers are shifting their attention from reactive to proactive care, aiming to identify and manage cardiovascular risks before the onset of acute events. This transition is driving demand for non-invasive and portable diagnostic tools such as ECG machines, wearable heart rate monitors, ambulatory blood pressure monitors, and point-of-care ultrasound devices. These tools are increasingly deployed not only in hospitals but also in primary care clinics, pharmacies, and mobile health units, especially in underserved communities. Public health campaigns led by the Ministry of Health emphasize early screening for hypertension, diabetes, and hyperlipidemia, which are major precursors of cardiovascular disease. Simultaneously, private healthcare providers are launching wellness programs that incorporate cardiovascular risk assessments into routine check-ups. Moreover, medical device companies are introducing user-friendly diagnostic devices that cater to non-specialist users, facilitating wider adoption across Brazil’s fragmented healthcare system. This trend supports the broader agenda of reducing long-term healthcare costs and improving population health outcomes. As awareness continues to grow and technology becomes more accessible, preventive cardiology will remain a pivotal element in shaping the evolution of the cardiovascular devices market in Brazil.
Market Challenges
High Cost of Advanced Cardiovascular Devices and Limited Reimbursement Coverage
One of the most significant challenges hindering the growth of the Brazil cardiovascular devices market is the high cost associated with advanced medical technologies. Devices such as implantable cardioverter defibrillators (ICDs), transcatheter heart valves, and robotic-assisted surgical systems involve substantial capital investment, making them inaccessible for many public hospitals and lower-income patients. While Brazil’s Unified Health System (SUS) provides universal healthcare coverage, budget constraints often limit the inclusion and availability of high-end cardiovascular devices within public institutions. In the private sector, where access to advanced treatments is more prevalent, out-of-pocket costs remain high, especially for procedures not fully covered under private insurance plans. Furthermore, reimbursement mechanisms for new and innovative devices are often delayed, creating a financial barrier for hospitals to adopt newer technologies. For instance, hospitals in Brazil have reported challenges in integrating robotic-assisted surgical systems due to high acquisition and maintenance costs. The complex regulatory and approval processes further slow down the reimbursement pathway. As a result, many healthcare providers prefer sticking to older, cost-effective technologies, which may compromise the quality and outcomes of care. This cost-related disparity between the public and private healthcare sectors significantly affects equitable access to life-saving cardiovascular interventions and slows the overall adoption of cutting-edge solutions in the Brazilian market.
Regional Disparities and Uneven Access to Specialized Cardiac Care
Brazil’s vast geographic size and socioeconomic diversity contribute to stark regional disparities in access to specialized cardiac care, posing a major obstacle to the equitable growth of the cardiovascular devices market. While major cities such as São Paulo, Brasília, and Rio de Janeiro boast advanced medical facilities and high-end cardiac centers, rural and northern regions often suffer from a shortage of infrastructure, skilled cardiologists, and diagnostic equipment. Limited availability of catheterization labs, cardiac surgery units, and post-operative rehabilitation services in these areas restricts the use of cardiovascular devices and negatively impacts patient outcomes. Patients from remote or underserved communities often travel long distances to receive treatment, causing delays in diagnosis and intervention. Additionally, insufficient digital infrastructure in these regions hinders the effective deployment of remote monitoring and telecardiology solutions. The uneven distribution of healthcare resources leads to a fragmented care delivery system, where advanced cardiovascular interventions remain concentrated in urban areas. Bridging this regional gap requires significant investment in healthcare infrastructure, workforce development, and mobile health initiatives. Without addressing these disparities, the market’s growth will remain constrained, and the benefits of technological advancement in cardiovascular care will not reach the broader population.
Market Opportunities
Growing Demand for Preventive and Home-Based Cardiac Monitoring Solutions
The increasing emphasis on preventive healthcare and chronic disease management presents a significant opportunity for the expansion of home-based and wearable cardiovascular monitoring devices in Brazil. With the rise in lifestyle-related disorders such as hypertension, obesity, and diabetes, there is growing demand for early detection and continuous monitoring tools to prevent the onset of serious cardiovascular conditions. The adoption of wearable technologies-such as smartwatches with ECG functionality, portable heart rate monitors, and wireless blood pressure devices-is rapidly gaining traction among both patients and healthcare providers. These devices not only support timely intervention but also reduce the burden on healthcare infrastructure by minimizing hospital admissions and facilitating remote care. As Brazil continues to improve its digital health ecosystem, manufacturers and service providers can capitalize on the increasing demand for connected health technologies tailored to the local population.
Untapped Potential in Rural and Underserved Regions through Mobile Health and Telecardiology
A substantial market opportunity lies in expanding cardiovascular care to Brazil’s rural and underserved regions through mobile health units, telemedicine platforms, and decentralized diagnostic services. These areas remain underpenetrated due to logistical and infrastructural limitations, but advancements in telehealth and portable diagnostic tools are creating viable solutions for extending cardiac services. By partnering with public health agencies and local care providers, cardiovascular device companies can deploy cost-effective, scalable technologies to bridge the access gap. Addressing this untapped market segment will not only enhance healthcare equity but also unlock long-term revenue potential in regions historically excluded from specialized cardiac care.
Market Segmentation Analysis
By Product
The Brazil cardiovascular devices market is segmented into diagnostic & monitoring devices and surgical devices. Diagnostic and monitoring devices account for a significant share, driven by the rising demand for early detection and continuous monitoring of cardiovascular conditions. Devices such as electrocardiograms (ECGs), Holter monitors, and cardiac event monitors are widely utilized across hospitals and outpatient settings to track heart rhythms and detect abnormalities. The increasing incidence of lifestyle-related disorders such as hypertension and arrhythmias has further boosted the use of these non-invasive tools. On the other hand, surgical devices are witnessing steady growth owing to the rising number of interventional and surgical procedures, including angioplasty, valve replacement, and bypass surgeries. The demand for advanced devices like stents, pacemakers, catheters, and implantable defibrillators is rising in response to growing healthcare infrastructure and the adoption of minimally invasive techniques.
By End User
The end-user segmentation includes hospitals & clinics, diagnostic laboratories, ambulatory surgical centers, and others. Hospitals and clinics dominate the market due to the availability of skilled healthcare professionals, comprehensive diagnostic facilities, and the ability to perform complex cardiovascular procedures. These institutions benefit from government funding and public-private partnerships, especially in urban centers. Diagnostic laboratories also hold a substantial share, particularly in urban regions where routine cardiac screenings and advanced diagnostic testing are commonly conducted. Ambulatory surgical centers are emerging as key contributors, supported by a shift toward same-day procedures and cost-effective outpatient care. These centers are becoming preferred choices for elective cardiovascular interventions due to shorter recovery times and reduced healthcare costs. The 'Others' category, including home healthcare and rehabilitation centers, is gaining traction with the rise in remote patient monitoring and chronic disease management programs.
Segments
Based on Product
- Diagnostic & Monitoring Devices
- Surgical Devices
Based on End User
- Hospitals & Clinics
- Diagnostic Laboratories
- Ambulatory Surgical Centers
- Others
Based on Diagnostic & Monitoring Devices Type
- ECG
- Implantable Cardiac Monitors
- Holter Monitors
- Mobile Cardiac Telemetry
- MRI
- Others
Based on Surgical Devices Type
- Cardiac Resynchronization Therapy (CRT)
- Implantable Cardioverter Defibrillators (ICDs
- Pacemakers
- Coronary Stents
- Catheters
Based on Region
- São Paulo
- Rio de Janeiro
- Minas Gerais
Regional Analysis
Southeast region (47.3%)
The Southeast region holds the dominant share of the market, accounting for 47.3% of total revenue in 2024. This is primarily due to the presence of major metropolitan centers such as São Paulo and Rio de Janeiro, which house some of the country’s most advanced public and private healthcare institutions. These cities have well-equipped hospitals, highly trained cardiologists, and access to cutting-edge diagnostic and interventional technologies, making them central hubs for cardiovascular treatment and device deployment. The region also benefits from concentrated healthcare investments and a higher proportion of insured patients, both of which drive demand for advanced cardiovascular solutions.
South region (21.6%)
The South region ranks second, contributing approximately 21.6% of the market. States such as Paraná, Santa Catarina, and Rio Grande do Sul are known for their relatively strong healthcare systems and efficient service delivery. These areas are seeing a steady rise in the adoption of minimally invasive procedures and preventive diagnostics, supported by favorable health indicators and growing public awareness regarding cardiovascular health. The South also benefits from a high rate of private healthcare coverage, which facilitates access to newer and more sophisticated cardiovascular technologies.
Key players
- Abbott
- GE HealthCare
- Edwards Lifesciences Corporation
- Siemens Healthcare GmbH
- BIOTRONIK SE & Co. KG
- Cardinal Health
- Medtronic
- Boston Scientific Corporation
- Johnson & Johnson Services, Inc.
- Osvaldo Cruz Foundation
- Fisiomed
- Biosensors International
Competitive Analysis
The Brazil cardiovascular devices market features a blend of global medical technology giants and prominent domestic players. Multinational companies such as Abbott, Medtronic, Boston Scientific, and Johnson & Johnson dominate due to their expansive product portfolios, strong R\&D capabilities, and established distribution networks. These companies continually invest in innovation, offering advanced diagnostic and interventional solutions tailored to evolving clinical needs. GE HealthCare and Siemens Healthcare GmbH lead in imaging and diagnostic systems, essential for early detection and procedural guidance. Edwards Lifesciences and BIOTRONIK are key players in structural heart and electrophysiology segments. Meanwhile, local companies like Osvaldo Cruz Foundation and Fisiomed are strengthening their presence by catering to cost-sensitive markets and collaborating with public health initiatives. Strategic partnerships, regional manufacturing, and government-aligned healthcare solutions remain central to sustaining competitive advantage in Brazil’s diverse and evolving cardiovascular landscape.
Recent Developments
- In February 2025, Abbott issued a safety notification for certain Assurity and Endurity pacemakers due to potential epoxy mixing issues during manufacturing, which could lead to device malfunction.
- In April 2025, GE HealthCare launched the Revolution™ Vibe CT system featuring Unlimited One-Beat Cardiac imaging and AI solutions, enhancing cardiac imaging capabilities.
- In April 2025, Medtronic reported promising evidence for its Affera™ pulsed field ablation technologies in treating atrial fibrillation patients.
- In May 2024, Siemens Healthineers announced new cardiology applications with artificial intelligence for the Acuson Sequoia ultrasound system, including a new 4D transesophageal (TEE) transducer for cardiology exams.
- In February 2025, Philips developed a miniaturized intracardiac transducer, enabling higher-resolution views of cardiac structures and functions, benefiting structural heart disease and electrophysiology procedures.
- In March 2025, Boston Scientific announced the acquisition of SoniVie Ltd. to expand its interventional cardiology therapies offerings with ultrasound-based renal denervation technology.
- In June 2024, Biovac Institute entered a partnership with Sanofi to locally manufacture inactivated polio vaccines in Africa, aiming to serve the potential needs of over 40 African countries.
Market Concentration and Characteristics
The Brazil cardiovascular devices market exhibits a moderately high level of market concentration, with a significant share controlled by leading multinational corporations such as Medtronic, Abbott, Boston Scientific, and Johnson & Johnson. These companies leverage strong brand recognition, extensive product portfolios, and advanced technological capabilities to maintain a competitive edge. The market is characterized by rapid innovation, growing demand for minimally invasive procedures, and increasing integration of digital health solutions. While global players dominate high-end segments like implantable devices and advanced diagnostics, local manufacturers and public institutions are gaining traction in cost-effective solutions and preventive care technologies. The presence of a dual healthcare system-public (SUS) and private-further shapes purchasing patterns, with the private sector adopting advanced technologies faster, while the public sector focuses on affordability and accessibility. Regulatory improvements and localization strategies are fostering more competition and encouraging innovation tailored to Brazil’s specific healthcare needs.
Report Coverage
The research report offers an in-depth analysis based on Product, End User, Diagnostic & Monitoring Devices Type, Surgical Devices Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Brazil cardiovascular devices market is expected to grow robustly through 2032, driven by rising disease prevalence and increasing healthcare investments.
- Demand for minimally invasive cardiovascular interventions will rise as hospitals adopt technologies that offer faster recovery and improved outcomes.
- Preventive cardiology will gain prominence, boosting the use of wearable monitors, early diagnosis tools, and portable screening devices.
- Artificial intelligence and digital health platforms will increasingly support diagnostics, remote monitoring, and predictive cardiac care across healthcare systems.
- Government investments in cardiovascular care through SUS will expand access to essential devices in underserved and rural regions.
- Brazil is expected to strengthen local production of cardiovascular devices, reducing dependence on imports and improving supply chain resilience.
- Telecardiology will continue to grow, bridging regional healthcare disparities and enabling remote diagnosis and follow-ups in remote communities.
- Private hospitals and clinics will increasingly establish specialized cardiac centers, enhancing procedural capabilities and patient throughput.
- ANVISA is likely to further simplify device approvals, encouraging innovation and faster market entry for both domestic and foreign players.
- Collaborative initiatives between government bodies and private manufacturers will accelerate technology adoption and improve cardiovascular care delivery.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases and Lifestyle-Related Disorders
Brazil faces a high and growing burden of cardiovascular diseases, driven by aging demographics and increasing rates of hypertension, diabetes, and obesity. This has led to greater demand for both diagnostic and interventional cardiovascular devices to manage and treat chronic heart conditions.
Expanding Healthcare Infrastructure and Access to Advanced Medical Technologies
Significant investments in Brazil’s public and private healthcare infrastructure have improved access to advanced cardiac care, especially in major urban centers. The adoption of state-of-the-art diagnostic imaging, catheterization labs, and minimally invasive surgical suites is fueling market growth.
Technological Advancements and Innovation in Cardiovascular Devices
Rapid innovation in minimally invasive procedures, AI-powered diagnostics, and wearable cardiac monitors is enhancing the precision and efficiency of cardiovascular care. These advancements are increasing adoption rates among healthcare providers and improving patient outcomes.
Supportive Government Initiatives and Growing Public Awareness
Government-led preventive health campaigns and favorable reimbursement policies are promoting early screening and risk assessment for cardiovascular diseases. Increased public awareness and national initiatives are driving demand for both preventive and therapeutic cardiovascular devices.
Regional Healthcare Expansion and Telemedicine Integration
Efforts to expand healthcare access in underserved northern and northeastern regions, including the deployment of telecardiology and mobile health solutions, are opening new market opportunities and reducing regional disparities in cardiovascular care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Brazil cardiovascular devices market in 2023, and what is its projected size by 2032?
What are the primary factors driving growth in the Brazil cardiovascular devices market?
Which regions in Brazil dominate the cardiovascular devices market?
Who are the major players operating in the Brazil cardiovascular devices market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Diagnostic & Monitoring Devices
- 1.2.2 Surgical Devices
- 1.3 By End User
- 1.3.1 Hospitals & Clinics
- 1.3.2 Diagnostic Laboratories
- 1.3.3 Ambulatory Surgical Centers
- 1.3.4 Others
- 1.4 By Surgical Devices Type
- 1.4.1 Cardiac Resynchronization Therapy (CRT)
- 1.4.2 Implantable Cardioverter Defibrillators (ICDs)
- 1.4.3 Pacemakers
- 1.4.4 Coronary Stents
- 1.4.5 Catheters
- 1.5 By Diagnostic & Monitoring Devices Type
- 1.5.1 ECG
- 1.5.2 Implantable Cardiac Monitors
- 1.5.3 Holter Monitors
- 1.5.4 Mobile Cardiac Telemetry
- 1.5.5 MRI
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,029.76 million → 2032: USD 3,604.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Brazil Cardiovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Brazil Cardiovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Brazil Cardiovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Brazil Cardiovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Brazil Cardiovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Brazil Cardiovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Brazil Cardiovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Brazil Cardiovascular Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,029.76 million → 2032: USD 3,604.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Brazil Cardiovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diagnostic & Monitoring Devices
- 12.3.7.2 Surgical Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals & Clinics
- 12.4.7.2 Diagnostic Laboratories
- 12.4.7.3 Ambulatory Surgical Centers
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Surgical Devices Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cardiac Resynchronization Therapy (CRT)
- 12.5.7.2 Implantable Cardioverter Defibrillators (ICDs)
- 12.5.7.3 Pacemakers
- 12.5.7.4 Coronary Stents
- 12.5.7.5 Catheters
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Diagnostic & Monitoring Devices Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 ECG
- 12.6.7.2 Implantable Cardiac Monitors
- 12.6.7.3 Holter Monitors
- 12.6.7.4 Mobile Cardiac Telemetry
- 12.6.7.5 MRI
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Brazil Cardiovascular Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Brazil Cardiovascular Devices Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Brazil Cardiovascular Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Brazil Cardiovascular Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE HealthCare
- 18.4 Edwards Lifesciences Corporation
- 18.5 Siemens Healthineers
- 18.6 BIOTRONIK SE & Co. KG
- 18.7 Cardinal Health
- 18.8 Medtronic
- 18.9 Boston Scientific Corporation
- 18.10 Johnson & Johnson Services, Inc.
- 18.11 Osvaldo Cruz Foundation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

