
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Diagnostic Imaging Devices Market Size 2024 | USD 1,061.20 million |
| Canada Diagnostic Imaging Devices Market, CAGR | 3.41% |
| Canada Diagnostic Imaging Devices Market Size 2032 | USD 1,387.37 million |
Market Overview:
The Canada Diagnostic Imaging Devices Market is projected to grow from USD 1,061.20 million in 2024 to an estimated USD 1,387.37 million by 2032, with a compound annual growth rate (CAGR) of 3.41% from 2024 to 2032.
The growth of the Canadian diagnostic imaging devices market is driven by several key factors. The increasing prevalence of chronic diseases, such as cancer and cardiovascular conditions, has led to a higher demand for advanced diagnostic imaging technologies that provide accurate and timely detection. Additionally, Canada’s aging population is contributing to the need for more frequent imaging procedures, as older individuals are more susceptible to diseases that require detailed imaging for diagnosis and treatment. Technological advancements, including innovations in MRI, CT, and ultrasound imaging, are also boosting market growth, with artificial intelligence and portable imaging devices enhancing diagnostic precision and accessibility. Furthermore, government initiatives, such as the introduction of screening programs like the lung cancer initiative in British Columbia, are improving access to diagnostic imaging services and driving demand.
Regionally, the diagnostic imaging market is shaped by the healthcare infrastructure and population density across Canada. Western Canada, including provinces like British Columbia and Alberta, is investing heavily in healthcare facilities and diagnostic technologies to cater to growing populations. In Central Canada, Ontario and Quebec, with their large populations and numerous medical institutions, drive the demand for advanced imaging systems. Meanwhile, in Eastern Canada, provinces like Nova Scotia and Newfoundland are enhancing their healthcare services, including diagnostic imaging, to improve patient care and support medical tourism. These regional developments are crucial in shaping the market’s growth across Canada.
Market Insights:
- The Canada Diagnostic Imaging Devices Market is projected to grow from USD 1,061.20 million in 2024 to USD 1,387.37 million by 2032, with a CAGR of 3.41%.
- The increasing prevalence of chronic diseases like cancer and cardiovascular conditions is driving demand for advanced diagnostic imaging technologies for early and accurate detection.
- Canada’s aging population contributes to the rising need for frequent diagnostic imaging, particularly for degenerative diseases, cancers, and cardiovascular issues.
- Technological innovations, especially in MRI, CT, ultrasound, and AI-driven devices, are improving diagnostic precision and accessibility, accelerating market growth.
- Government healthcare initiatives, including cancer screening programs and infrastructure investments, are supporting the growth of diagnostic imaging services across the country.
- The market is geographically diverse, with strong growth in Western Canada due to investments in healthcare facilities and technology, and Central Canada leading due to its large population.
- High costs, reimbursement challenges, and regulatory compliance remain key challenges, limiting accessibility to advanced diagnostic imaging technologies in certain regions.
Report scope
This reports segments are Canada Diagnostic Imaging Devices Market as Follows;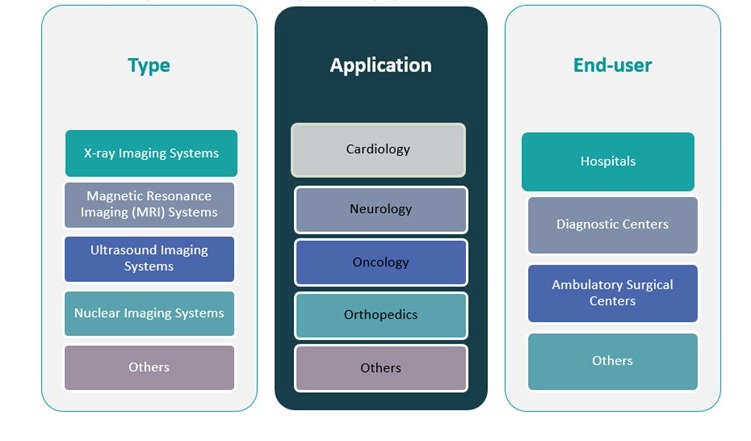
Market Drivers:
Increasing Prevalence of Chronic Diseases
One of the primary drivers of the Canada Diagnostic Imaging Devices Market is the rising incidence of chronic diseases, particularly cancer and cardiovascular conditions. The growing burden of these diseases has placed a significant emphasis on early and accurate diagnosis, thereby increasing the demand for diagnostic imaging devices. According to recent data, the number of cancer cases in Canada is projected to rise sharply in the coming years, necessitating the use of advanced imaging technologies for effective diagnosis, staging, and treatment monitoring. This trend is also seen with cardiovascular diseases, where imaging techniques like echocardiography, CT angiography, and MRI are crucial for evaluating heart conditions and guiding treatment decisions. As chronic disease rates continue to climb, the demand for high-quality diagnostic imaging devices is expected to intensify.
Aging Population and Healthcare Needs
Canada's aging population is another critical factor driving the growth of the diagnostic imaging market. The elderly are more prone to various health conditions, including degenerative diseases, cancers, and cardiovascular issues, which require regular diagnostic imaging to manage and treat effectively. With a significant portion of the Canadian population entering older age brackets, healthcare systems are increasingly relying on imaging technologies to cater to this demographic. Older individuals typically need more frequent imaging services for conditions such as osteoporosis, dementia, and tumor detection, thus contributing to the overall demand for diagnostic imaging devices. This demographic shift necessitates an expansion in healthcare infrastructure and access to diagnostic tools across the country, further fueling the market’s growth.
Technological Advancements in Imaging Devices
Continuous technological innovations are reshaping the diagnostic imaging landscape in Canada, driving the adoption of more advanced, efficient, and precise devices. Innovations in magnetic resonance imaging (MRI), computed tomography (CT) scanners, and ultrasound technologies have significantly improved image quality and diagnostic accuracy. For instance, in obstetrics, Samsung's WS80A ultrasound systems render fetal facial expressions and limb movements in utero with 0.2mm spatial resolution, enhancing prenatal diagnostics. Moreover, the integration of artificial intelligence (AI) into imaging devices has led to faster and more reliable results, allowing healthcare professionals to make quicker decisions regarding patient care. These advancements not only enhance diagnostic capabilities but also improve patient outcomes by enabling early disease detection and more effective treatment planning. As healthcare providers increasingly invest in state-of-the-art imaging technologies to improve service quality and meet growing demand, the market continues to expand.
Government Initiatives and Healthcare Investments
Government policies and initiatives have also played a crucial role in driving the demand for diagnostic imaging devices in Canada. With a focus on improving healthcare accessibility and quality, the Canadian government has invested heavily in healthcare infrastructure, including diagnostic imaging technologies. For instance, government of Alberta and Siemens Healthineers have embarked on an eight-year, 800-million-Canadian-dollar ($560 million U.S.) partnership to upgrade and replace cancer-specific diagnostic imaging equipment. Programs aimed at increasing early disease detection, such as cancer screening initiatives, are directly contributing to market growth. Provincial governments, such as in British Columbia, have implemented large-scale screening programs to detect diseases like lung cancer, which increases the demand for imaging devices. These investments in healthcare infrastructure and screening initiatives are expected to continue driving the growth of the diagnostic imaging devices market, as they support both preventive healthcare and the effective management of existing conditions.
Market Trends:
Shift Toward Minimally Invasive Imaging Techniques
A notable trend in the Canada Diagnostic Imaging Devices Market is the growing preference for minimally invasive imaging techniques. With advancements in imaging technology, patients now have access to non-invasive methods for diagnosing a wide range of conditions. Techniques such as ultrasound, digital mammography, and MRI are becoming increasingly popular due to their ability to provide high-quality images without the need for surgical intervention. These non-invasive methods reduce the risks associated with traditional diagnostic procedures, such as biopsies, and improve patient comfort and recovery times. As healthcare providers aim to deliver patient-centered care, the demand for these minimally invasive imaging solutions continues to rise, reshaping the way diagnostic imaging is approached in Canada. For instance, the new Interventional Radiology Suite at Oak Valley Health's Markham Stouffville Hospital, unveiled in April 2022, is expected to see over 2,000 patients annually using minimally invasive techniques that will improve patient outcomes.
Rise of Portable and Point-of-Care Imaging Devices
Another emerging trend in the Canadian diagnostic imaging market is the rise of portable and point-of-care (POC) imaging devices. These devices are gaining traction due to their flexibility, convenience, and ability to deliver real-time imaging results at the point of care. Portable ultrasound devices, for example, are being widely adopted by healthcare professionals for their mobility and ease of use, particularly in rural or remote areas where access to advanced diagnostic equipment may be limited. These portable solutions allow for quicker diagnoses and more immediate treatment decisions, especially in emergency settings and during patient transport. As healthcare systems look to improve accessibility and reduce waiting times, the demand for portable imaging solutions is expected to continue growing. For example, the Intelligent Network for Point-of-Care Ultrasound project in British Columbia has deployed 90 portable ultrasound devices in remote, rural, and Indigenous communities throughout the province.
Integration of Artificial Intelligence and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) into diagnostic imaging devices is another significant trend in the Canadian market. AI and ML technologies are increasingly being incorporated into imaging software, improving the speed, accuracy, and efficiency of diagnostic processes. For instance, AI algorithms are being used to assist radiologists in detecting abnormalities in imaging scans such as tumors, fractures, and lesions. These technologies can analyze large datasets more quickly and accurately than human counterparts, reducing the chances of diagnostic errors and enabling earlier disease detection. As these technologies mature and gain acceptance, the role of AI and ML in the diagnostic imaging market is poised to expand, improving overall patient outcomes and transforming the healthcare landscape in Canada.
Growing Demand for Hybrid Imaging Systems
Hybrid imaging systems, which combine multiple imaging modalities into a single device, are becoming more prevalent in Canada’s diagnostic imaging market. These systems, such as PET/CT and PET/MRI, offer enhanced diagnostic capabilities by providing both functional and anatomical imaging in a single scan. Hybrid systems allow healthcare providers to obtain more detailed and accurate information about a patient's condition, improving treatment planning and monitoring. These systems are particularly valuable in oncology, cardiology, and neurology, where both structural and functional insights are critical. As the demand for more precise and comprehensive diagnostic tools increases, the adoption of hybrid imaging systems is expected to rise, representing a key trend in the Canadian market.
Market Challenges Analysis:
High Cost of Diagnostic Imaging Devices
One of the primary restraints in the Canada Diagnostic Imaging Devices Market is the high cost associated with advanced diagnostic imaging technologies. Devices such as MRI machines, CT scanners, and hybrid imaging systems require significant capital investment, making them expensive for healthcare institutions, particularly smaller clinics and hospitals. The high cost of purchasing and maintaining these devices limits their accessibility, especially in rural or remote regions where healthcare budgets may be constrained. Additionally, the cost of training healthcare professionals to operate these advanced devices further contributes to the financial burden, slowing down the widespread adoption of these technologies.
Reimbursement Challenges
Another significant challenge in the diagnostic imaging market is the complexity and variability of reimbursement policies for imaging procedures. While the Canadian healthcare system provides public funding for many medical services, reimbursement for diagnostic imaging is often subject to provincial regulations and guidelines. Variations in reimbursement rates across provinces can create financial challenges for healthcare providers, especially those in underfunded regions. Delays or discrepancies in reimbursement can lead to financial strain for hospitals and imaging centers, discouraging investment in advanced imaging technologies and hindering the growth of the market.
Regulatory and Compliance Issues
The regulatory landscape surrounding diagnostic imaging devices in Canada also presents a challenge. Health Canada requires rigorous testing and approval processes for medical devices, which can be time-consuming and costly. Compliance with these regulations is necessary to ensure patient safety and device efficacy, but the stringent requirements can slow down the introduction of new technologies to the market. Additionally, any changes in regulatory policies or approval processes could disrupt market dynamics and delay the launch of innovative imaging solutions.
Limited Skilled Workforce
The shortage of skilled professionals to operate and interpret diagnostic imaging equipment is another restraint facing the market. As advanced imaging technologies evolve, there is a growing demand for radiologists and technicians with specialized training to effectively use and interpret these systems. However, there is a limited supply of skilled professionals in Canada, particularly in underserved areas, which can hinder the optimal utilization of imaging devices and slow market growth. For instance, the Canadian Association of Medical Radiation Technologists (CAMRT) has reported a critical shortage of medical radiation technologists, with demand outpacing availability.
Market Opportunities:
A significant opportunity in the Canada Diagnostic Imaging Devices Market lies in the expansion of healthcare infrastructure, particularly in underserved regions. As the Canadian government continues to invest in healthcare services, there is a growing demand for state-of-the-art diagnostic imaging technologies in rural and remote areas. This presents an opportunity for both public and private healthcare providers to integrate advanced imaging devices into their facilities, improving access to essential diagnostic services. Additionally, government initiatives aimed at enhancing healthcare accessibility, such as funding for rural health clinics and screening programs, provide further opportunities for market growth. By addressing the geographical disparities in healthcare access, the market for diagnostic imaging devices in these regions is expected to expand significantly.
Another opportunity for growth in the diagnostic imaging market is the increasing adoption of artificial intelligence (AI) and advanced imaging technologies. AI-powered imaging devices offer enhanced accuracy, efficiency, and speed in diagnosing a range of medical conditions. As these technologies continue to evolve, healthcare providers in Canada are increasingly incorporating AI and machine learning into their diagnostic imaging systems, enabling faster and more reliable diagnoses. The integration of AI in imaging processes can improve diagnostic accuracy, reduce human error, and increase operational efficiency, presenting a substantial opportunity for growth in the market. Furthermore, as AI-driven devices become more affordable and accessible, their adoption is likely to expand, particularly in smaller healthcare settings, driving market growth across Canada.
Market Segmentation Analysis:
he Canada Diagnostic Imaging Devices Market is segmented by type, application, and end-user, each contributing to the overall market growth.
By Type Segment The X-ray Imaging Systems segment holds a significant share in the market due to its widespread use in diagnostic imaging. These systems are cost-effective and provide quick results, making them essential in emergency and routine diagnostic settings. Magnetic Resonance Imaging (MRI) Systems are also a dominant segment, valued for their superior image quality and non-invasive nature, especially in neurology and oncology applications. Nuclear Imaging Systems, though smaller in market share, are increasingly used for precise imaging in oncology and cardiology. Ultrasound Imaging Systems are gaining popularity due to their portability, safety, and real-time imaging capabilities, particularly in obstetrics and cardiology. The "Others" segment includes specialized imaging systems like CT and PET scanners, contributing to market diversity.
By Application Segment In terms of applications, cardiology is a leading segment, driven by the rising prevalence of heart diseases and the demand for early detection and monitoring. Neurology follows closely, with MRI and CT systems used for diagnosing neurological conditions such as strokes and tumors. Oncology is a rapidly growing segment, driven by the increasing incidence of cancer and the need for accurate imaging techniques for treatment planning. Orthopaedics also represents a significant portion of the market, with imaging technologies used for joint and bone disorders. The "Others" segment encompasses various specialized applications across other medical fields.
By End-user Segment Hospitals remain the largest end-user segment, as they host a wide array of diagnostic imaging equipment to meet the needs of diverse patient populations. Diagnostic Centers are also significant users of imaging devices, offering specialized services for various conditions. Ambulatory Surgical Centers are becoming increasingly important due to the shift toward outpatient procedures, driving demand for portable and efficient imaging technologies. The "Others" segment includes research institutions and government healthcare organizations.
Segmentation:
By Type Segment:
- X-ray Imaging Systems
- Magnetic Resonance Imaging (MRI) Systems
- Nuclear Imaging Systems
- Ultrasound Imaging Systems
- Others
By Application Segment:
- Cardiology
- Neurology
- Oncology
- Orthopaedics
- Others
By End-user Segment:
- Hospitals
- Diagnostic Centers
- Ambulatory Surgical Centers
- Others
Regional Analysis:
The Canada Diagnostic Imaging Devices Market is characterized by regional differences driven by factors such as population density, healthcare infrastructure, and provincial healthcare initiatives. The market can be broadly segmented into four major regions: Western Canada, Central Canada, Eastern Canada, and Atlantic Canada, each exhibiting distinct dynamics in terms of demand for diagnostic imaging devices.
Western Canada
Western Canada, particularly provinces like British Columbia and Alberta, holds a significant share of the diagnostic imaging devices market. The region’s healthcare infrastructure is robust, with several large medical centers and hospitals investing in advanced imaging technologies to meet the growing demand for diagnostic services. British Columbia, for instance, is actively involved in expanding its diagnostic capabilities through government-funded initiatives, especially cancer screening programs, which are fueling the demand for imaging devices like MRI and CT scanners. The Western Canada market share is estimated to be approximately 35%, driven by both population growth and the increasing focus on enhancing healthcare access in remote and rural areas.
Central Canada
Central Canada, which includes Ontario and Quebec, is the largest market for diagnostic imaging devices, accounting for an estimated 45% of the total market share. Ontario, with its large population and highly developed healthcare system, is a key driver of this market. The province is home to numerous medical institutions, which continuously upgrade their imaging equipment to meet the needs of their diverse patient population. Similarly, Quebec’s healthcare infrastructure is rapidly evolving, with investments in diagnostic imaging technologies to support the aging population and rising chronic disease rates. The concentration of healthcare providers in these regions and government-driven initiatives aimed at improving diagnostic services contribute to their dominant position in the market.
Eastern Canada
Eastern Canada, comprising provinces like Nova Scotia, New Brunswick, and Newfoundland and Labrador, holds a smaller but growing share of the diagnostic imaging devices market, approximately 10%. This region has a more concentrated healthcare system, with fewer large medical institutions compared to other parts of Canada. However, there is increasing demand for diagnostic imaging solutions as the provinces invest in healthcare expansion to meet the needs of aging populations and residents in rural areas. While the market share is relatively smaller, the focus on improving access to healthcare and supporting elderly populations creates growth potential in this region.
Atlantic Canada
Atlantic Canada, including provinces like Prince Edward Island and Newfoundland and Labrador, accounts for roughly 5% of the diagnostic imaging devices market. Although the region has a smaller population and fewer healthcare facilities, there is a growing need for diagnostic imaging devices, especially in response to the aging population and the rise of chronic diseases. The Canadian government’s healthcare initiatives, aimed at improving services in remote and underserved areas, are gradually driving market growth in this region. However, the market share remains limited due to lower population density and fewer large-scale healthcare institutions compared to other regions.
Key Player Analysis:
- Samsung Medison
- Mindray
- GE Healthcare
- Siemens Healthineers
- Philips Healthcare
Competitive Analysis:
The Canada Diagnostic Imaging Devices Market is highly competitive, with several global and regional players offering a diverse range of imaging solutions. Major multinational companies such as Siemens Healthineers, GE Healthcare, Philips Healthcare, and Canon Medical Systems dominate the market, offering advanced imaging technologies like MRI, CT scanners, ultrasound, and hybrid imaging systems. These companies leverage their extensive product portfolios, established brand recognition, and innovation in AI-powered diagnostic tools to maintain their competitive edge. Additionally, regional players and smaller companies are also making significant strides, focusing on offering cost-effective solutions and specialized services tailored to local needs. The competition is further intensified by the growing demand for portable and point-of-care imaging devices, prompting companies to invest in research and development to introduce more versatile, user-friendly products. Strategic partnerships, mergers, and acquisitions are also common in the market as companies aim to expand their reach and enhance their product offerings to cater to the evolving needs of healthcare providers across Canada.
Recent Developments:
- In January 2022, Weeneebayko General Hospital became the first hospital in Canada to implement a portable MRI scanner for a project assessing the technology in a clinical setting. This initiative aims to improve access to diagnostic imaging services in remote areas of James Bay and Hudson's Bay.
- Siemens Healthineers recently inked a $560 million partnership with the Alberta Cancer Foundation in March 2025. This eight-year deal focuses on replacing outdated imaging equipment with AI-enabled oncology treatment systems and establishing centers of excellence for AI and oncology training in Alberta.
- GE Healthcare has been actively expanding its AI portfolio. In March 2025, GE partnered with NVIDIA to develop autonomous imaging tools for X-ray and ultrasound systems, aiming to address radiology staff shortages and improve diagnostic workflows.
- At ECR 2025 in February, Philips launched SmartSpeed Precise technology for MRI systems. This dual-AI engine innovation significantly improves scan speed and image quality while reducing patient wait times.
Market Concentration & Characteristics:
The Canada Diagnostic Imaging Devices Market is moderately concentrated, with a few dominant multinational companies holding a significant market share. Global players such as Siemens Healthineers, GE Healthcare, Philips Healthcare, and Canon Medical Systems lead the market, driven by their advanced technologies, extensive distribution networks, and strong brand presence. These companies invest heavily in research and development to maintain their competitive edge, especially in high-end imaging systems like MRI, CT, and hybrid modalities. While the market is concentrated in terms of high-end technology providers, there is also a growing presence of regional players offering more affordable and localized solutions. This segmentation allows smaller companies to compete by catering to specific healthcare needs, such as portable and point-of-care imaging devices. The market characteristics reflect a balance between technological innovation and cost-effective solutions, with a focus on improving diagnostic accuracy, patient outcomes, and healthcare accessibility across Canada.
Report Coverage:
The research report offers an in-depth analysis based on type, application, and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Canadian diagnostic imaging devices market is expected to experience substantial growth, driven by increased demand for advanced imaging technologies.
- The rising prevalence of chronic diseases, such as cancer and cardiovascular conditions, will contribute to a growing need for diagnostic imaging solutions.
- Government initiatives focused on improving healthcare access and expanding screening programs will drive the adoption of imaging devices in underserved regions.
- Advancements in technologies like AI and machine learning will improve diagnostic accuracy and efficiency in medical imaging.
- The demand for portable and point-of-care imaging devices will rise, particularly in rural and remote areas.
- The aging population will play a significant role in the market’s growth, increasing the need for diagnostic procedures.
- Hybrid imaging systems that combine multiple modalities will see increased demand due to their enhanced diagnostic capabilities.
- Streamlined regulatory approval processes will accelerate the introduction of innovative imaging devices into the market.
- Smaller and mid-sized healthcare facilities will focus on investing in affordable imaging solutions to manage increasing healthcare costs.
- Increased competition among global and regional players will drive innovation, enhancing the quality and functionality of diagnostic imaging devices.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Diagnostic Imaging Devices Market?
What factors are driving the growth of the Canada Diagnostic Imaging Devices Market?
What are the key segments within the Canada Diagnostic Imaging Devices Market?
Who are the major players in the Canada Diagnostic Imaging Devices Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,061.20 million → 2032: USD 1,387.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Diagnostic Imaging Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Diagnostic Imaging Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Diagnostic Imaging Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Diagnostic Imaging Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Diagnostic Imaging Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Diagnostic Imaging Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Diagnostic Imaging Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Diagnostic Imaging Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,061.20 million → 2032: USD 1,387.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Diagnostic Imaging Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Diagnostic Imaging Devices Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Canada Diagnostic Imaging Devices Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Canada Diagnostic Imaging Devices Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
