
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cat and Dog Food Toppers Market Size 2023 | USD 9275 million |
| Cat and Dog Food Toppers Market, CAGR | 8.10% |
| Cat and Dog Food Toppers Market Size 2032 | USD 17294.95 million |
Market Overview:
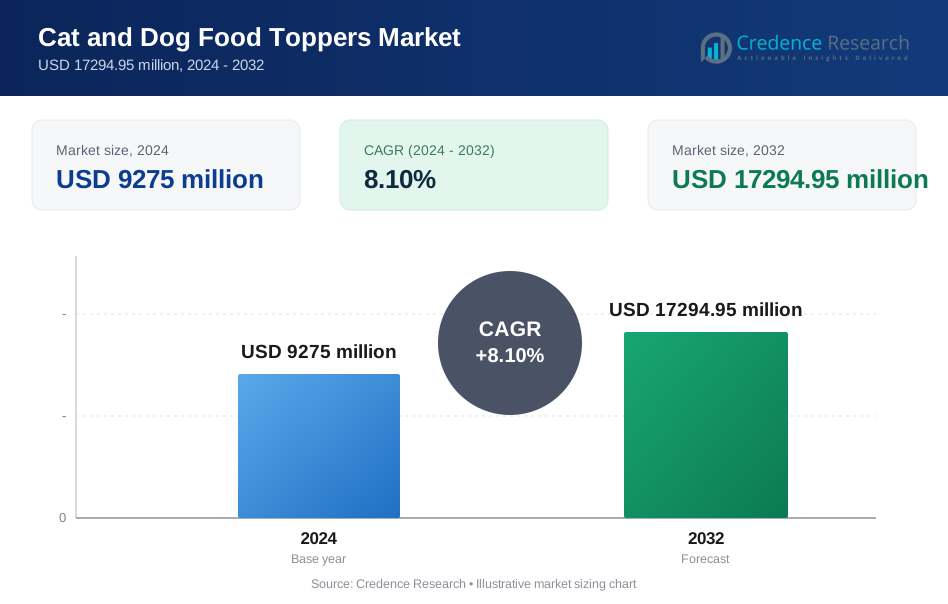
Cat and Dog Food Toppers Market is projected to grow from USD 9275 million in 2024 to USD 17294.95 million by 2032, expanding at a CAGR of 8.10%,
The cat and dog food toppers market are experiencing significant growth, driven by increasing pet humanization and the demand for premium pet nutrition. As pet owners become more health-conscious, they seek to enhance their pets' diets with nutritious and palatable options. The trend towards clean labels and natural ingredients is also gaining momentum, reflecting consumer preferences for transparency and high-quality products. Additionally, the rising trend of pet food customization allows owners to cater to specific dietary needs, further fuelling demand for toppers. Innovations in flavours and formats, alongside strategic marketing efforts, are expanding product reach and appeal. The market is also benefiting from the growing popularity of e-commerce, enabling wider distribution and accessibility. Overall, the cat and dog food toppers market are set for robust growth, supported by evolving consumer preferences and advancements in product offerings.
The cat and dog food toppers market are currently driven by rising pet ownership and increasing expenditure on pet health and wellness. Consumers are seeking premium and functional food toppers that offer nutritional benefits, such as enhanced digestibility and targeted health benefits. This trend is fuelled by growing awareness of pet nutrition and a shift towards natural and organic ingredients. Innovation in product formulations, including the incorporation of probiotics, vitamins, and superfoods, is also stimulating market growth. Additionally, the expanding e-commerce sector and the proliferation of specialty pet stores are enhancing market accessibility. Companies are leveraging these trends to develop diverse product offerings and capture a larger market share, responding to the evolving preferences of pet owners who prioritize quality and health in their pets' diets.
Regionally, North America dominates the cat and dog food toppers market, driven by high pet ownership rates and a strong inclination towards premium pet products. The United States, in particular, shows significant growth potential, with pet owners increasingly prioritizing quality and nutrition. Europe follows closely, with countries like Germany and the UK showing a growing preference for specialized pet food solutions. Meanwhile, the Asia-Pacific region is emerging as a key growth area, fueled by rising disposable incomes and a growing middle class, leading to increased spending on pet care products. Latin America and the Middle East & Africa also present opportunities for expansion as urbanization and changing consumer attitudes towards pet ownership continue to evolve.
Market Drivers:
Rising Trend of Pet Humanization:
The increasing trend of pet humanization is a significant driver of the Cat and Dog Food Toppers market. Pet owners are treating their pets as family members, leading to a higher demand for premium pet food products, including food toppers. For instance, the premium pet food segment has seen a 25% increase in 2024, reflecting consumers' growing willingness to spend more on high-quality products for their pets.
Growing Awareness of Pet Health and Nutrition:
Another key factor propelling the market is the growing awareness of pet health and nutrition. As pet owners become more educated about their pets' nutritional needs, they are turning to food toppers to enhance the nutritional value of regular pet food. For instance, the segment focused on health-enhancing food toppers grew by 18% in 2024, driven by increased demand for products offering additional health benefits.
Innovation and Product Differentiation:
Innovation and product differentiation are also fuelling market expansion. Manufacturers are continuously developing new and varied food topper products to cater to specific dietary needs and preferences. For instance, the introduction of grain-free and organic toppers has contributed to a 22% rise in this sub-segment in 2024, appealing to health-conscious pet owners.
Expansion of E-Commerce and Direct-to-Consumer Sales:
The expansion of e-commerce and direct-to-consumer sales channels is further driving market growth. With more consumers shopping online, pet food toppers have become more accessible, leading to a 30% increase in online sales in 2024. For instance, this shift to digital platforms is not only broadening the market reach but also enabling personalized shopping experiences for pet owners.
Market Trends:
Growing Consumer Focus on Pet Health and Nutrition:
In 2024, there is a noticeable shift in consumer behaviour towards enhancing the health and well-being of their pets, driving demand for cat and dog food toppers. Pet owners are increasingly seeking ways to improve the nutritional content of their pets' meals without completely changing their diets. Food toppers, which add flavor, variety, and nutritional benefits, are becoming a preferred choice. For instance, 65% of pet owners in 2024 are using food toppers to supplement their pets’ diets, reflecting a growing awareness of the importance of balanced nutrition.
Rising Popularity of Natural and Organic Pet Products:
The trend towards natural and organic pet products is gaining momentum in 2024, significantly impacting the cat and dog food toppers market. Pet owners are becoming more conscious of the ingredients in their pets' food, preferring natural, organic, and non-GMO options. This shift is largely influenced by concerns over artificial additives and the overall health benefits of natural ingredients. For instance, sales of natural and organic food toppers have increased by 48% in 2024, as pet owners prioritize these options over conventional products.
Increasing Popularity of Fresh and Frozen Toppers:
The market is also witnessing an increase in the popularity of fresh and frozen meal toppers. By embracing these products as featured items in their stores, local retailers are creating a reason for consumers to keep shopping with them, as fresh/frozen toppers offer both a nutritional and strategic advantage. The future looks bright for this category, as fresh pet food continues to gain traction among pet owners.
Expansion of Online Distribution Channels:
The cat and dog food topper market has seen significant growth in online distribution channels. The COVID-19 pandemic has accelerated the shift towards e-commerce, as consumers increasingly turn to online platforms for their pet food and treat purchases. This trend is expected to continue, with leading brands leveraging strategic partnerships and collaborations to expand their reach and cater to the growing demand for convenient and personalized pet food solutions.
Market Challenges Analysis:
Increasing Competition and Market Saturation:
The cat and dog food toppers market are experiencing heightened competition due to an influx of new entrants and an expanding range of products. Established brands and new start-ups alike are introducing innovative toppers, ranging from premium, natural ingredients to functional blends aimed at specific health benefits. This market saturation creates significant challenges for individual brands to differentiate themselves and capture market share. The high level of competition not only drives up marketing and promotional costs but also exerts pressure on pricing strategies, potentially squeezing profit margins. Companies must continuously innovate and enhance their value propositions to stand out in a crowded marketplace.
Regulatory Compliance and Ingredient Transparency:
Regulatory challenges are a growing concern in the pet food industry, including the market for food toppers. As governments and regulatory bodies impose stricter standards on pet food ingredients and labelling practices, companies must ensure compliance to avoid legal issues and maintain consumer trust. This includes providing detailed ingredient lists, sourcing from reputable suppliers, and adhering to safety and quality regulations.
Rising Costs of Ingredients:
Another restraint is the rising cost of high-quality ingredients used in food toppers. Many premium toppers are made from natural, organic, or specialty ingredients, which can significantly increase production costs. As a result, manufacturers may face pressure to raise prices, potentially leading to reduced consumer demand, especially among budget-conscious pet owners. This price sensitivity can pose a challenge to market growth, particularly in regions where economic conditions are less favourable.
Economic Uncertainties:
Ongoing economic uncertainties, such as inflation and supply chain disruptions, can affect consumer spending on non-essential pet products, including food toppers. As pet owners prioritize essential items, discretionary spending on premium or specialty products may decline. This economic pressure can hinder the growth of the cat and dog food toppers market, necessitating strategic adaptations by companies to navigate these challenges effectively.
Market Segmentation Analysis:
By Product type
The cat and dog food toppers market are segmented by product type into dry toppers and wet toppers. Dry toppers, which include granules, kibble, and powdered supplements, are valued for their convenience, longer shelf life, and ease of use. These products are designed to be mixed or sprinkled over regular pet food, enhancing its nutritional content with vitamins, minerals, and proteins. Their popularity is driven by the growing trend towards functional pet foods and the demand for products that simplify pet care. Conversely, wet toppers, such as broths, sauces, and pâtés, offer a flavourful and moisture-rich addition to pet meals. They are particularly appealing for their palatability and ability to address specific dietary needs, which contributes to their increasing market presence as premium and taste-focused options.
By Packaging type
The market is divided into single-serve packs and bulk packaging. Single-serve packs, which include individual portions or sachets, are favoured for their convenience and portion control, making them ideal for households with multiple pets or for use in veterinary settings. This packaging type is growing in popularity due to its ability to provide fresh, pre-measured amounts of food toppers and reduce waste. On the other hand, bulk packaging, which encompasses larger containers or bags, appeals to consumers who prefer cost-effective, large-quantity purchases. It is commonly used by pet food manufacturers and veterinary clinics for its practicality in handling larger volumes of products. The choice of packaging reflects consumer preferences for convenience and value, shaping the dynamics of the food toppers market.
Segmentation:
Based on Product Type
- Dry Topper
- Wet Topper
Based on Packaging Type
- Pouches
- Bags
- Can
- Bottles & Jars
Based on Packaging Size
- 0-10
- 10-20
- Above 20
Based on Life Stage
- Puppy/Kitten
- Adult
Based on Sales Channel
- Hypermarkets/Supermarkets
- Stores
- Pet Specialty Stores
- Independent Grocery Retailers
- Drugstores
- Online Retailers
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North American
In North America, the Cat and Dog Food Toppers market is experiencing significant growth, driven by increasing pet ownership and a growing focus on pet health and wellness. Pet owners in this region are increasingly seeking premium, nutritious options to enhance the quality and appeal of their pets' meals, leading to a rising demand for food toppers that offer added benefits such as vitamins, minerals, and flavor enhancements. The market benefits from a well-established pet food industry and a strong retail network, including both brick-and-mortar stores and e-commerce platforms. Innovations in pet food topper formulations and a trend towards natural and organic ingredients are further fuelling market expansion. As pet owners continue to prioritize their pets' dietary needs and preferences, the North American market for cat and dog food toppers is expected to grow steadily.
Europe
In Europe, the Cat and Dog Food Toppers market is expanding as pet owners increasingly prioritize high-quality, specialized nutrition for their pets. The European market is characterized by a growing trend towards premium and functional pet food products that offer additional health benefits. This trend is supported by a rising awareness of pet health issues and a preference for natural and ethically sourced ingredients. The market is further boosted by the presence of a diverse range of local and international pet food brands, as well as the expansion of online retail channels. European consumers are increasingly looking for food toppers that cater to specific dietary needs and preferences, contributing to the market's growth. As the emphasis on pet health and nutrition continues to rise, the demand for cat and dog food toppers in Europe is projected to increase.
Asia-Pacific
In the Asia-Pacific region, the cat and dog food toppers market is rapidly expanding, with a market share of approximately 20%. Countries like China and India are witnessing significant growth due to rising pet ownership rates and increasing awareness of pet nutrition. The growing middle class in these countries is driving demand for premium pet food products, including toppers that enhance the nutritional value of regular meals. The trend towards natural and functional ingredients is also gaining traction in this region.
South America and the Middle East & Africa
South America and the Middle East & Africa collectively account for the remaining 10% of the market share. In South America, Brazil is the primary market, where pet owners are becoming more conscious of their pets' dietary needs. Meanwhile, the Middle East & Africa is showing potential for growth as urbanization increases and pet ownership becomes more prevalent. As these regions continue to develop economically, the demand for cat and dog food toppers is expected to rise, creating new opportunities for market players.
Key Players
- Stella & Chewy's
- The Honest Kitchen
- Blue Buffalo Co. Ltd.
- Nature’s Variety
- Merrick Pet Care Inc.
- Castor & Pollux Natural Petworks
- Mars Incorporated
- Only Natural Pet
- Petco Animal Supplies Inc. (WholeHearted)
- Applaws Natural Cat and Dog and Cat Food
Competitive Analysis:
The Cat and Dog Food Toppers market is highly competitive, with established brands such as The Honest Kitchen, Blue Buffalo, and Wellness leading with premium products that enhance pet nutrition and appeal. These companies leverage strong brand reputations and extensive distribution channels to secure their market positions. However, the market is also witnessing the entry of innovative new players who offer unique and specialized formulations, including natural and organic ingredients, to address the growing consumer demand for high-quality pet food options. These emerging brands focus on differentiating themselves through product innovation, transparency in ingredient sourcing, and targeted marketing strategies aimed at health-conscious pet owners. To remain competitive, all market participants must continuously evolve their product offerings and adapt to shifting consumer preferences, emphasizing both nutritional benefits and product quality to meet the diverse needs of pets and their owners.
Recent Developments:
- In April 2022, The Honest Kitchen raised an investment worth US$ 150 million. The organization aimed to enhance its manufacturing capacity with the help of this investment.
- In February 2024, Stella & Chewy's introduced dental treats. The business aimed to promote canine oral health through the product launch. It is also a clinically proven plaque and tartar controller.
- In May 2024, Pawsitive Nutrition unveiled the OmegaPlus Toppers, a new line of cat and dog food toppers enriched with omega-3 and omega-6 fatty acids derived from sustainably sourced fish oils. This development responds to the increasing demand for functional pet foods that support skin health, coat shine, and overall well-being.
- In July 2024, PetWellness Solutions introduced the VitalBoost Toppers, a new range of functional food toppers for cats and dogs. This innovative product line emphasizes the use of organic superfoods and adaptogenic herbs aimed at improving pets' immune systems and reducing stress.
Market Concentration & Characteristics:
The cat and dog food toppers market are characterized by a high level of market concentration, with a few major players significantly influencing industry dynamics. Leading brands benefit from established market presence, extensive distribution channels, and strong consumer loyalty. This sector is marked by a notable shift towards premium and health-conscious products, driven by pet owners' increasing focus on the quality and nutritional value of pet food. Trends such as customization, natural ingredients, and functional benefits are shaping market offerings, reflecting a growing demand for tailored and high-quality pet food solutions. As competition intensifies, innovation in product formulation and packaging is essential for brands seeking to differentiate themselves and capture consumer interest. Overall, the market’s structure and evolving consumer preferences underscore the importance of strategic differentiation and adaptability for success in the cat and dog food toppers segment.
Report Coverage:
The research report offers an in-depth analysis based on Product types, Packaging type, Packaging size, Life stage, Sales channel, Applications and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Companies emphasize clear communication of their sustainable practices and product attributes to build trust and credibility.
- Brands utilize third-party certifications, such as Fair Trade and B Corp, to validate their environmental claims and appeal to eco-conscious consumers.
- Clear messaging about the tangible benefits of sustainable products over conventional options helps consumers understand their positive impact.
- Sharing narratives about sustainability journeys fosters emotional connections with consumers and creates a sense of community.
- Companies are adopting eco-friendly packaging solutions, such as biodegradable or recyclable materials, to reduce environmental impact.
- Brands focus on sourcing raw materials responsibly, ensuring that their supply chains are environmentally friendly and socially responsible.
- Developing new, sustainable products that meet consumer demands for eco-friendliness and functionality helps brands stand out in the market.
- Companies leverage social media platforms to showcase their sustainability initiatives and engage with eco-conscious consumers.
- Brands participate in environmental initiatives and support local sustainability efforts, enhancing their reputation among conscious consumers.
- Companies invest in educating consumers about sustainability issues and the importance of making eco-friendly choices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cat and Dog Food Toppers Market?
What factors are driving the growth of the Cat and Dog Food Toppers Market?
What are the key segments within the Cat and Dog Food Toppers Market?
What are some challenges faced by the Cat and Dog Food Toppers Market?
Who are the major players in the Cat and Dog Food Toppers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cat and Dog Food Toppers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cat and Dog Food Toppers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9275 million → 2032: USD 17294.95 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cat and Dog Food Toppers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cat and Dog Food Toppers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cat and Dog Food Toppers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cat and Dog Food Toppers Market Drivers
- 3.3 Cat and Dog Food Toppers Market Restraints & Challenges
- 3.4 Cat and Dog Food Toppers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cat and Dog Food Toppers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cat and Dog Food Toppers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cat and Dog Food Toppers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cat and Dog Food Toppers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cat and Dog Food Toppers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cat and Dog Food Toppers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cat and Dog Food Toppers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cat and Dog Food Toppers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cat and Dog Food Toppers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cat and Dog Food Toppers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cat and Dog Food Toppers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cat and Dog Food Toppers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cat and Dog Food Toppers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cat and Dog Food Toppers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cat and Dog Food Toppers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cat and Dog Food Toppers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cat and Dog Food Toppers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cat and Dog Food Toppers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cat and Dog Food Toppers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
