
Market Overview
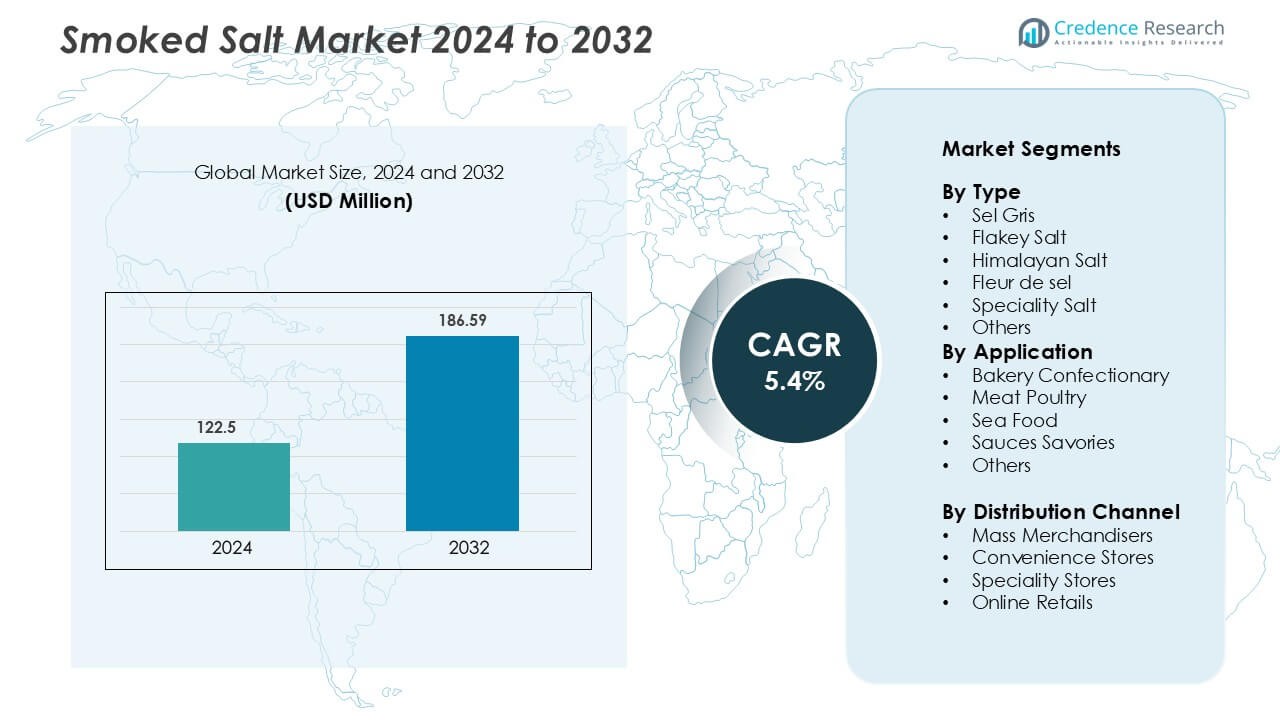
Smoked Salt Market was valued at USD 122.5 million in 2024 and is anticipated to reach USD 186.59 million by 2032, growing at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smoked Salt Market Size 2024 | USD 122.5 Million |
| Smoked Salt Market, CAGR | 6.1% |
| Smoked Salt Market Size 2032 | USD 186.59 Million |
The smoked salt market features a competitive mix of established producers and emerging artisanal brands focused on innovation and sustainability. Key players such as Besmoke, Saltverk, Jacobsen Salt Co., and SaltWorks lead the market through advanced smoking processes, eco-friendly production methods, and diverse product portfolios catering to gourmet and industrial applications. Companies like Maine Sea Salt Company, Viva Doria, and Frontier Natural Products Co-op strengthen their presence through clean-label offerings and online retail growth. North America dominates the global smoked salt market with a 36% share, driven by high consumer demand for natural, premium seasonings and strong distribution networks across retail and foodservice channels.
Market Insights
- The global smoked salt market was valued at USD 122.5 million in 2024 and is projected to grow at a CAGR of 5.4 % from 2025 to 2032, supported by rising demand for premium and natural seasonings.
- Growing consumer inclination toward clean-label and artisanal food products drives consistent market expansion, especially in meat, poultry, and seafood applications that together hold 58% segment share.
- Increasing innovation in infused and flavored smoked salts, along with expanding e-commerce distribution, shapes emerging market trends, fostering stronger global penetration.
- The competitive landscape remains fragmented, with players like Saltverk, Besmoke, and SaltWorks focusing on sustainable sourcing, flavor diversification, and eco-friendly packaging to maintain leadership.
- Regionally, North America leads with a 36% market share, followed by Europe at 29% and Asia Pacific at 22%, driven by growing consumer awareness, expanding gourmet food sectors, and the rising popularity of global cuisines across major economies.
Market Segmentation Analysis:
By Type
Sel Gris dominates the smoked salt market with nearly 32% share due to its mineral-rich composition and coarse texture, enhancing flavor complexity in gourmet dishes. Its natural moisture retention and smoky aroma make it ideal for grilling, roasting, and finishing applications. Flakey salt and Himalayan salt follow closely, driven by their premium positioning and visual appeal in high-end culinary products. Specialty salt variants, including infused and wood-smoked types, continue to gain popularity as chefs and manufacturers seek distinctive flavor profiles for gourmet and artisanal food products.
- For instance, SaltWorks, Inc. reports it offers over 110 varieties of salts including a smoked Grey Sea Salt line, and uses wood-smoke ageing periods from 24 hours up to 7 days to develop aroma.
By Application
The meat and poultry segment holds the largest market share of 38%, fueled by rising consumer demand for natural preservatives and enhanced flavoring agents. Smoked salt acts as a clean-label ingredient, replacing artificial additives in processed meats and barbecue products. The seafood and sauces categories are expanding due to increased adoption in marinades and ready-to-eat foods. Bakery and confectionery applications are also emerging, as smoked salt introduces a unique balance of sweetness and umami that appeals to premium snack and dessert manufacturers.
- For instance, SaltWorks, Inc. invested more than $2 million in its “Perfect Smoke™” cold-smoking technology.
By Distribution Channel
Mass merchandisers lead the smoked salt market with 41% share, supported by wide product availability, bulk packaging, and competitive pricing strategies. Specialty stores maintain strong traction in urban markets, catering to gourmet consumers seeking premium and exotic salt variants. Online retail channels are growing rapidly, driven by the expansion of e-commerce platforms and rising awareness of artisanal food ingredients. Convenience stores continue to serve impulse and small-scale buyers, contributing to consistent market penetration across developed and developing regions.
Key Growth Drivers
Rising Demand for Natural and Artisanal Food Products The growing preference for natural, minimally processed, and additive-free foods strongly supports smoked salt adoption. Consumers are increasingly drawn to artisanal ingredients that enhance flavor without synthetic additives. Smoked salt aligns with this trend by offering a clean-label alternative to conventional seasonings. Its use in gourmet and organic product formulations adds value to premium brands in both retail and foodservice sectors. Moreover, as consumers associate smoked salt with authentic culinary experiences and craftsmanship, producers are scaling up small-batch production methods and expanding distribution to capitalize on this evolving preference for high-quality, natural food enhancers.
- For instance, Maldon Salt Company continues hand-harvesting pyramid-shaped salt flakes in Essex, England using the same methods since 1882 and provides smoked sea salt flake variants in 125 g and 500 g tubs.
Expanding Applications in Processed and Ready-to-Eat Foods
The smoked salt market benefits from growing demand in processed meat, seafood, and ready-to-eat food categories. Manufacturers use smoked salt to impart smoky flavor, improve shelf life, and replace artificial flavor enhancers. As convenience foods gain global popularity, the inclusion of smoked salt enhances product appeal while maintaining clean-label standards. Food processors are leveraging its natural preservative properties to reduce sodium chloride levels in formulations. This versatility across meat rubs, sauces, and snack foods is fueling adoption among large-scale manufacturers seeking premium, natural flavoring alternatives that meet evolving consumer preferences for taste and health balance.
- For instance, SaltWorks lists over 110 distinct salt varieties including smoked salts, and offers bulk packaging to food-manufacturers from 5 ounces up to 40,000 pounds per SKU.
Growth of Premium Culinary and Restaurant Segments
Restaurants, gourmet food producers, and high-end culinary brands increasingly use smoked salt to elevate menu offerings and differentiate their flavors. The ingredient’s ability to add depth, aroma, and visual appeal supports its use in fine dining and luxury food preparation. The hospitality sector’s focus on ingredient authenticity and unique dining experiences further drives demand. Chefs worldwide experiment with varied wood-smoked salts-such as applewood, hickory, and mesquite to achieve signature flavors. This trend, combined with rising international exposure to global cuisines, strengthens the role of smoked salt in the premium culinary space, reinforcing its long-term market expansion potential.
Key Trend & Opportunity
Product Innovation through Flavored and Infused Variants
Manufacturers are developing innovative smoked salt products infused with herbs, spices, and exotic wood smoke to cater to evolving consumer palates. These innovations include chili-smoked, truffle-infused, and wine-barrel-aged salts, targeting the gourmet and specialty segment. The diversification allows brands to differentiate themselves and attract culinary professionals and home cooks seeking unique sensory experiences. Additionally, premium packaging and small-batch branding appeal to gifting and online retail markets. This innovation-driven approach not only expands application scope but also enables companies to command higher margins and strengthen brand loyalty in the competitive flavoring and seasoning industry.
- For instance, Bourbon Barrel Foods produces a “Bourbon Smoked Sea Salt” available in three SKUs: 0.75 oz mini, 5 oz tin, and 18 oz food-service container.
Rapid Expansion of E-commerce and Direct-to-Consumer Channels
The shift toward digital retail platforms has opened new growth avenues for smoked salt producers. E-commerce allows small and niche brands to reach global audiences, offering variety and convenience to consumers. Online platforms also enable storytelling and transparency about sourcing and production methods, aligning with the growing demand for traceable and sustainable products. Subscription boxes, gourmet ingredient kits, and customized packaging further enhance customer engagement. This digital transformation, coupled with the rising number of health-conscious and culinary-focused online shoppers, positions e-commerce as a pivotal growth enabler for both established players and emerging smoked salt brands.
- For instance, Bulls Bay Saltworks offers its smoked sea salt in units as small as ½ ounce mini bags, solar-evaporated and smoked using oak from the farm, highlighting full traceability from bay water to bottle.
Key Challenge
High Production and Distribution Costs
Producing smoked salt requires specialized smoking processes, temperature control, and high-quality wood or flavoring materials, leading to elevated production costs. Additionally, transportation and packaging expenses rise due to the product’s sensitivity to moisture and contamination. These factors make smoked salt more expensive than standard table salt, limiting its affordability in mass-market applications. Smaller producers also face logistical challenges in scaling operations and maintaining consistent flavor profiles. Managing cost efficiency while ensuring product quality and artisanal authenticity remains a core challenge for manufacturers seeking to balance premium pricing with market competitiveness.
Supply Chain and Raw Material Limitations
The availability of quality sea salt and sustainable wood sources used for smoking presents supply chain vulnerabilities. Seasonal fluctuations and environmental factors affecting salt harvesting can disrupt production volumes. Furthermore, regulatory pressures regarding sustainable sourcing and emissions from wood-smoking processes may constrain traditional production methods. Exporters face additional hurdles in meeting varying food safety and labeling standards across regions. These constraints compel producers to invest in traceable sourcing systems and environmentally friendly smoking technologies, increasing operational complexity while maintaining the product’s authentic characteristics in a growing and competitive global market.
Regional Analysis
North America
North America holds the largest share of 36% in the global smoked salt market, driven by strong consumer preference for gourmet and natural food products. The U.S. leads regional consumption, supported by the popularity of barbecue culture, premium seasoning blends, and clean-label packaged foods. Canada also contributes significantly, emphasizing artisanal salt varieties in specialty retail and restaurant sectors. The presence of major producers and growing online retail penetration further strengthen market expansion. Continuous innovation in flavor-infused variants and partnerships with premium foodservice brands sustain North America’s leadership in smoked salt production and consumption.
Europe
Europe accounts for 29% of the global smoked salt market, fueled by high demand for natural flavor enhancers and culinary diversity. Countries such as Germany, France, and the U.K. lead consumption, with smoked salt widely used in gourmet cooking, charcuterie, and specialty bakery applications. The region’s strong focus on organic and sustainable food sourcing supports steady growth. European manufacturers continue to innovate with regional wood-smoked varieties like oak and beechwood salts. The market benefits from established distribution networks and premium retail channels that cater to the expanding clean-label and fine-dining food segments across Western Europe.
Asia Pacific
Asia Pacific captures 22% market share, emerging as the fastest-growing region due to increasing awareness of Western cuisines and flavor experimentation. Countries such as Japan, South Korea, and Australia drive demand through high-end culinary applications and luxury restaurants. India and China are experiencing rising adoption in premium packaged foods and online retail. The growing middle-class population, expanding hospitality industry, and preference for fusion cuisines contribute to robust demand. Local producers and international brands are introducing customized smoked salt variants to align with regional flavor preferences and enhance penetration in emerging urban markets.
Latin America
Latin America holds an 8% market share, supported by expanding use of smoked salt in meat, seafood, and snack applications. Brazil and Mexico are key contributors, leveraging smoked salt in barbecue seasoning and gourmet product lines. Increasing interest in natural and handcrafted ingredients is fostering demand in urban retail markets. Artisanal producers are experimenting with tropical wood varieties and regional flavor infusions, appealing to local tastes. Although adoption remains niche, growing culinary tourism and export opportunities for premium salts are expected to strengthen Latin America’s position within the global smoked salt industry.
Middle East & Africa
The Middle East & Africa region accounts for 5% of the smoked salt market, characterized by gradual growth in premium food consumption and Western culinary adoption. The UAE and South Africa lead regional demand, supported by rising hospitality investments and international restaurant expansion. Smoked salt finds applications in gourmet seasoning, meat processing, and luxury retail segments. Limited domestic production and high import dependency pose challenges, but growing consumer interest in flavor innovation and natural seasonings drives steady market entry opportunities for global and regional salt producers across the region.
Market Segmentations:
By Type
- Sel Gris
- Flakey Salt
- Himalayan Salt
- Fleur de sel
- Speciality Salt
- Others
By Application
- Bakery Confectionary
- Meat Poultry
- Sea Food
- Sauces Savories
- Others
By Distribution Channel
- Mass Merchandisers
- Convenience Stores
- Speciality Stores
- Online Retails
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the smoked salt market is characterized by a mix of established producers and emerging artisanal brands focusing on product differentiation and flavor innovation. Leading companies such as Besmoke, Saltverk, and Jacobsen Salt Co. emphasize sustainable sourcing, premium wood-smoking techniques, and distinctive flavor profiles to strengthen brand positioning. Firms like Frontier Natural Products Co-op and SaltWorks leverage extensive distribution networks and e-commerce channels to enhance global market reach. Meanwhile, emerging players such as Viva Doria and Hepps Salt Co. focus on small-batch production and gourmet packaging to attract health-conscious and culinary-driven consumers. Strategic partnerships with restaurants, gourmet retailers, and food processors are common to expand visibility and build customer loyalty. Companies are also investing in organic certifications, innovative infusions, and eco-friendly packaging to align with evolving consumer trends toward clean-label, natural, and environmentally responsible products, maintaining competitive advantage in a fragmented and innovation-driven market.
Key Player Analysis
- Besmoke
- Viva Doria
- Frontier Natural Products Co-op
- Saltverk
- Laguna Salt Co.
- Jacobsen Salt Co.
- Random Harvest Pty Ltd.
- Maine Sea Salt Company
- SaltWorks
- Hepps Salt Co.
Recent Developments
- In June 2025, Besmoke advanced its PureTech™ filtration technology, which removes up to 95% of carcinogenic PAHs from smoked ingredients, ensuring clean-label smoked salt solutions for food producers
- In October 2024, Eden Mill, an independent distillery from Scotland, launched a new product named Eden Mill Smoked Salt-a sugar syrup designed for cocktails and mocktails. It was made in partnership with East Neuk Salt Company, a small-batch salt producer based in St Monans. According to them, the syrup offered a blend of sweetness, saltiness, and smoky flavor.
- In September 2024, Viva Doria continued to offer its hickory smoked sea salt, which is slowly smoked over hickory wood for a distinctive savory-sweet flavor. The process is designed to produce a balanced, strong but subtle smokiness suitable for meats, fish, vegetables, and specialty cocktails. The product is available in several grain sizes and packages.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The smoked salt market will expand as consumers increasingly prefer natural flavoring ingredients.
- Demand for clean-label and additive-free products will continue to drive premium product development.
- Innovative infusions with herbs, spices, and exotic wood smokes will strengthen brand differentiation.
- E-commerce and direct-to-consumer channels will remain major growth enablers for niche producers.
- Foodservice and gourmet restaurant adoption will rise with the focus on authentic culinary experiences.
- Sustainable sourcing and eco-friendly packaging will become critical factors for market competitiveness.
- Manufacturers will invest in process optimization to reduce production costs and improve consistency.
- Asia Pacific and Latin America will emerge as key growth regions due to rising culinary diversification.
- Strategic collaborations between salt producers and food processors will expand industrial applications.
- Increasing consumer education on flavor quality and health benefits will sustain long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Smoked Salt market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Smoked Salt market projected to grow between 2025 and 2032?
Which segment held the largest share in 2024?
What are the primary factors fueling the growth of the Smoked Salt market?
Who are the leading companies in the Smoked Salt market?
Which region commanded the largest share of the Smoked Salt market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 122.5 million → 2032: USD 186.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smoked Salt Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smoked Salt Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smoked Salt Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smoked Salt Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smoked Salt Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smoked Salt Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smoked Salt Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smoked Salt Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 122.5 million → 2032: USD 186.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smoked Salt Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smoked Salt Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Smoked Salt Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Smoked Salt Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

