
Market Overviews
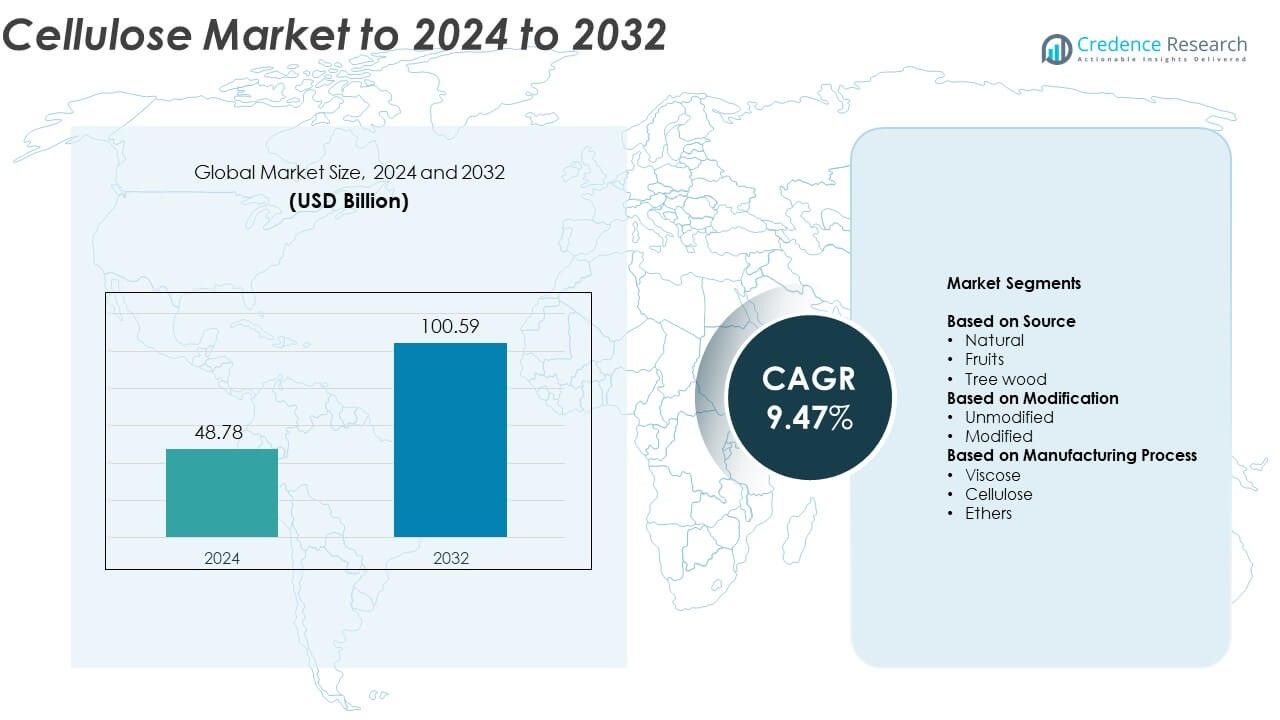
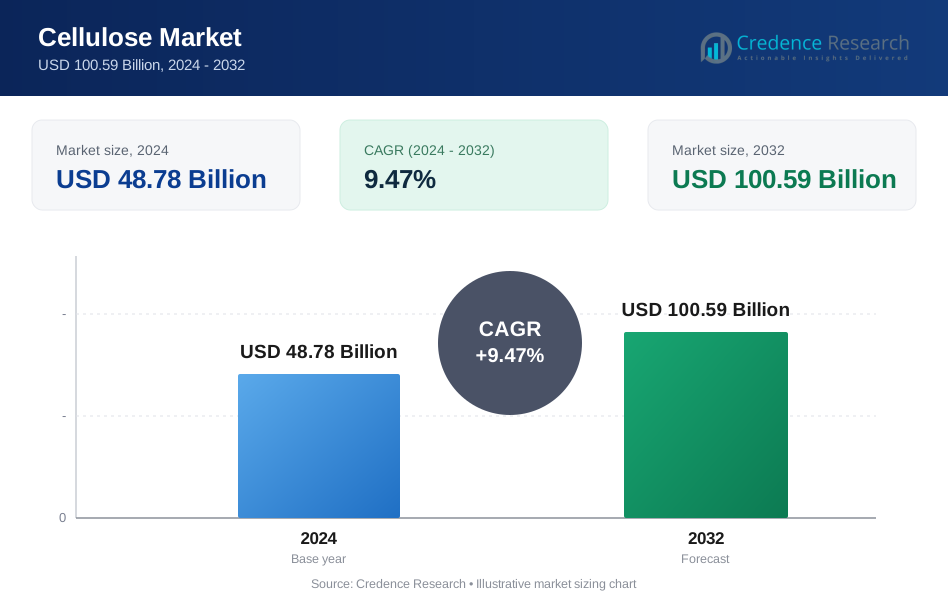
Cellulose market size was valued at USD 48.78 Billion in 2024 and is anticipated to reach USD 100.59 Billion by 2032, at a CAGR of 9.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cellulose Market Size 2024 | USD 48.78 Billion |
| Cellulose Market, CAGR | 9.47% |
| Cellulose Market Size 2032 | USD 100.59 Billion |
The cellulose market is led by major companies such as Lenzing AG, Celanese Corporation, Eastman Chemical Company, Daicel Corporation, Bracell, Shin-Etsu Chemical Co., Ltd., Dupont De Nemours, Inc., and NEC Corporation. These players focus on sustainable production, technological innovation, and expanding their product portfolios across packaging, textiles, and pharmaceutical applications. Asia-Pacific dominates the global cellulose market with approximately 34.1% share in 2024, driven by strong demand from pulp, paper, and textile industries. North America follows with about 32.6% share, supported by advanced R&D capabilities and growing adoption of eco-friendly materials across multiple sectors.
Market Insights
- The global cellulose market was valued at USD 48.78 Billion in 2024 and is projected to reach USD 100.59 Billion by 2032, growing at a CAGR of 9.47%.
- Rising demand for biodegradable and renewable materials across packaging, textiles, and pharmaceuticals drives market expansion.
- Increasing adoption of nanocellulose and cellulose derivatives in advanced applications such as composites and coatings highlights ongoing innovation trends.
- The market is moderately consolidated, with leading players focusing on sustainability, capacity expansion, and partnerships to enhance competitiveness.
- Asia-Pacific leads with 34.1% share, followed by North America at 32.6% and Europe at 27.4%, while the tree wood segment dominates the market with around 63.4% share in 2024.
Market Segmentation Analysis:
By Source
The tree wood segment dominates the cellulose market, accounting for around 63.4% share in 2024. Its leadership is driven by the abundant availability of wood pulp and established industrial infrastructure for large-scale cellulose extraction. Tree wood offers high purity and consistent fiber quality, making it the preferred raw material for paper, textile, and bioplastic production. Growing demand for sustainable materials and the expansion of pulp and paper industries in Asia-Pacific further strengthen the dominance of tree wood-based cellulose across global markets.
- For instance, Suzano started a 2.55 million-ton-per-year eucalyptus pulp line, lifting total pulp capacity to about 13.5 million tons.
By Modification
The unmodified cellulose segment leads the market with nearly 57.8% share in 2024. This dominance stems from its wide applications in textiles, packaging, and pharmaceutical formulations due to its biodegradability and cost-effectiveness. Unmodified cellulose offers excellent mechanical strength and moisture resistance, making it suitable for industrial and consumer products. Rising use in eco-friendly packaging and renewable composites further boosts segment growth, while ongoing innovation in natural polymer processing enhances its sustainability appeal.
- For instance, Sappi reports paper-pulp capacity of 2.3 million tons per year across its operations.
By Manufacturing Process
The viscose process segment holds the largest market share of about 49.2% in 2024. Its leadership is supported by extensive use in textile fibers, films, and hygiene products. The viscose route enables efficient conversion of cellulose into versatile forms with superior luster and breathability, suitable for apparel and industrial applications. Growing preference for semi-synthetic fibers and the expansion of textile manufacturing in emerging economies continue to drive the dominance of viscose-based cellulose production globally.
Key Growth Drivers
Rising Demand for Sustainable and Biodegradable Materials
The global shift toward eco-friendly materials is driving strong demand for cellulose-based products. Cellulose, derived from renewable sources, offers biodegradability and minimal environmental impact compared to synthetic alternatives. Its growing use in packaging, textiles, and bioplastics supports sustainability goals across industries. Increasing government regulations on single-use plastics and consumer preference for green materials continue to propel cellulose adoption globally.
- For instance, Tetra Pak the company reported that around 1.3 million tonnes of its carton packages were collected and sent for recycling, an increase of 7% in material collection compared to 2022.
Expanding Applications in Pharmaceuticals and Food Industry
Cellulose plays a critical role as a stabilizer, thickener, and emulsifier in food and pharmaceutical formulations. The growth of processed foods and demand for controlled-release drug systems are fueling consumption. Its non-toxic, inert, and biocompatible nature ensures widespread use in capsules, coatings, and dietary supplements. Continuous product innovation and increased regulatory approvals for cellulose derivatives further strengthen market growth.
- For instance, Sigachi Industries had a total installed microcrystalline cellulose (MCC) capacity of 18,000 metric tons per annum (MTPA), which it planned to expand to 30,000 MTPA with the addition of a new 12,000 MTPA project at its Dahej SEZ unit, according to company announcements in August 2025.
Technological Advancements in Cellulose Modification
Innovations in modification techniques are enhancing cellulose performance across industries. Advanced chemical and enzymatic treatments improve solubility, thermal stability, and compatibility with polymers. Modified cellulose is increasingly used in coatings, composites, and electronic materials, creating new commercial avenues. The development of nanocellulose and microcrystalline cellulose also expands industrial use in lightweight and high-strength materials, boosting market potential.
Key Trends & Opportunities
Growth of Nanocellulose in High-Performance Applications
Nanocellulose is emerging as a transformative material due to its superior strength, lightweight nature, and biodegradability. It finds growing use in electronics, composites, and filtration systems. Manufacturers are investing in large-scale production technologies to meet increasing industrial demand. Expanding R&D activities and collaborations with packaging and automotive sectors offer strong commercial opportunities in the coming years.
- For instance, Nippon Paper’s Ishinomaki facility has cellulose nanofiber capacity of about 500 tons per year.
Rising Investment in Bio-Based Packaging Solutions
Cellulose is increasingly adopted as a sustainable alternative in flexible packaging applications. Growing awareness about plastic waste and circular economy initiatives accelerates the transition to cellulose-based films and coatings. Companies are focusing on developing recyclable and compostable cellulose materials that maintain product integrity. This trend aligns with global sustainability goals and provides long-term market opportunities.
- For instance, Tetra Pak and Lactogal released 25 million paper-barrier aseptic cartons in Portugal during a 2023 consumer launch.
Key Challenges
High Production Costs and Complex Processing
Despite growing demand, cellulose production involves energy-intensive and costly processes, especially for modified and nanocellulose forms. Dependence on chemical treatments and purification steps raises operational expenses and limits affordability. Small-scale producers face barriers in scaling due to high equipment and raw material costs. Streamlining production technologies remains crucial to improve competitiveness and accessibility.
Competition from Synthetic and Alternative Bio-Polymers
The cellulose market faces strong competition from synthetic and emerging bio-based polymers offering similar mechanical and functional properties. Materials like polylactic acid (PLA) and polyhydroxyalkanoates (PHA) challenge cellulose’s position in packaging and textile industries. Differences in cost-efficiency and performance under certain conditions restrict wider substitution. Continuous innovation and application diversification are vital to maintaining cellulose’s market edge.
Regional Analysis
North America
North America holds around 32.6% share of the global cellulose market in 2024. The region benefits from strong demand in packaging, textiles, and pharmaceuticals supported by well-established manufacturing infrastructure. Growing adoption of biodegradable materials and rising regulatory pressure to reduce plastic waste drive cellulose consumption. The United States leads regional growth with increasing investments in nanocellulose research and production. Expanding use in food additives and coatings, coupled with innovation in cellulose-based composites, further strengthens the region’s position as a key market contributor.
Europe
Europe accounts for nearly 27.4% share of the global cellulose market in 2024. The region’s focus on circular economy initiatives and strict environmental policies accelerates demand for bio-based cellulose materials. Countries such as Germany, France, and the Netherlands dominate production due to advanced pulp and paper industries. Rising applications in sustainable packaging and green textiles reinforce market expansion. The European Union’s push for plastic reduction and strong investments in biopolymer innovation continue to enhance cellulose utilization across multiple industries.
Asia-Pacific
Asia-Pacific leads the global cellulose market with approximately 34.1% share in 2024. Rapid industrialization, growing paper production, and expanding textile manufacturing drive strong demand. China, Japan, and India remain major producers and consumers due to large-scale pulp processing and chemical industries. Increasing awareness of eco-friendly materials and government incentives for sustainable manufacturing further support growth. Rising consumption of processed foods and pharmaceutical products also contributes to cellulose demand, making Asia-Pacific the fastest-growing regional market during the forecast period.
Latin America
Latin America captures around 3.4% share of the global cellulose market in 2024. The region’s growth is primarily supported by expanding paper and packaging industries in Brazil, Chile, and Argentina. Abundant forest resources provide access to raw materials for cellulose extraction, enhancing regional supply stability. Increasing demand for sustainable packaging and bio-based materials in consumer goods fuels gradual expansion. Government efforts to promote green manufacturing and export-oriented pulp industries continue to strengthen Latin America’s cellulose production base.
Middle East & Africa
The Middle East and Africa region holds about 2.5% share of the global cellulose market in 2024. Growing demand from the food processing, construction, and pharmaceutical sectors supports gradual adoption. Limited local production capacity leads to heavy dependence on imports from Asia and Europe. Investments in sustainable packaging and industrial diversification, particularly in South Africa and the United Arab Emirates, drive future market opportunities. The rising shift toward renewable materials and increasing urbanization contribute to the region’s emerging cellulose demand base.
Market Segmentations:
By Source
- Natural
- Fruits
- Tree wood
By Modification
- Unmodified
- Modified
By Manufacturing Process
- Viscose
- Cellulose
- Ethers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the cellulose market features major participants such as Lenzing AG, Celanese Corporation, Eastman Chemical Company, Daicel Corporation, Bracell, Shin-Etsu Chemical Co., Ltd., Dupont De Nemours, Inc., and NEC Corporation. The market is characterized by strong vertical integration, advanced manufacturing technologies, and continuous innovation in cellulose derivatives and nanocellulose production. Companies are focusing on expanding production capacities, optimizing sustainability practices, and enhancing product performance through R&D investments. Strategic collaborations with packaging, textile, and pharmaceutical industries are becoming common to meet evolving application demands. Leading producers are also emphasizing environmentally responsible sourcing and circular economy initiatives to align with global sustainability goals. Additionally, regional expansion through mergers, acquisitions, and joint ventures strengthens supply chains and helps achieve economies of scale. The competitive environment remains moderately consolidated, with key players leveraging technological expertise and product diversification to maintain market leadership and address rising global demand.
Key Player Analysis
- Lenzing AG
- Celanese Corporation
- Eastman Chemical Company
- Daicel Corporation
- Bracell
- Shin-Etsu Chemical Co., Ltd.
- Dupont De Nemours, Inc.
- NEC Corporation
Recent Developments
- In 2025, Eastman launched Esmeri CC1N10, a high-performance, readily biodegradable cellulose ester micropowder for color cosmetics, meeting stringent EU regulations and improving product performance in lipstick, foundations, and powders.
- In 2025, Daicel launched "BELLOCEA® BS7," an eco-friendly cellulose acetate spherical particle product designed as a biodegradable substitute for microplastic beads in cosmetics.
- In 2025, Lenzing AG introduced new production processes for regenerated cellulose fibers that further reduce water consumption and carbon emissions, in line with growing consumer and regulatory demand for sustainable textiles and hygiene products.
Report Coverage
The research report offers an in-depth analysis based on Source, Modification, Manufacturing Process and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for bio-based and biodegradable cellulose materials will continue to rise globally.
- Nanocellulose will gain wider use in electronics, composites, and medical applications.
- Sustainable packaging solutions will remain a major growth area for cellulose producers.
- Technological advancements will improve cellulose extraction efficiency and reduce production costs.
- Asia-Pacific will maintain dominance due to strong industrial and consumer demand.
- Pharmaceutical and food industries will expand cellulose usage in formulations and coatings.
- Collaboration between manufacturers and research institutes will accelerate innovation in cellulose derivatives.
- Circular economy initiatives will boost cellulose adoption in textile and paper sectors.
- Increasing investment in green manufacturing will enhance cellulose market competitiveness.
- Development of advanced cellulose composites will open opportunities in automotive and construction industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cellulose Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cellulose Market projected to grow between 2025 and 2032?
Which Cellulose Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cellulose Market?
Who are the leading companies in the Cellulose Market?
Which region commanded the largest share of the Cellulose Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cellulose Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cellulose Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 48.78 Billion → 2032: USD 100.59 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cellulose Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cellulose Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cellulose Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cellulose Market Drivers
- 3.3 Cellulose Market Restraints & Challenges
- 3.4 Cellulose Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cellulose Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cellulose Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cellulose category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cellulose Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cellulose Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cellulose market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cellulose Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cellulose Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cellulose Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cellulose (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cellulose Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cellulose Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cellulose Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cellulose Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cellulose Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cellulose Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cellulose Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cellulose Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cellulose Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
