
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ceramic and Porcelain Tableware Market Size 2023 | USD 6,210.00 million |
| Ceramic and Porcelain Tableware Market, CAGR | 7.7% |
| Ceramic and Porcelain Tableware Market Size 2032 | USD 8,686.96 million |
Market Overview:
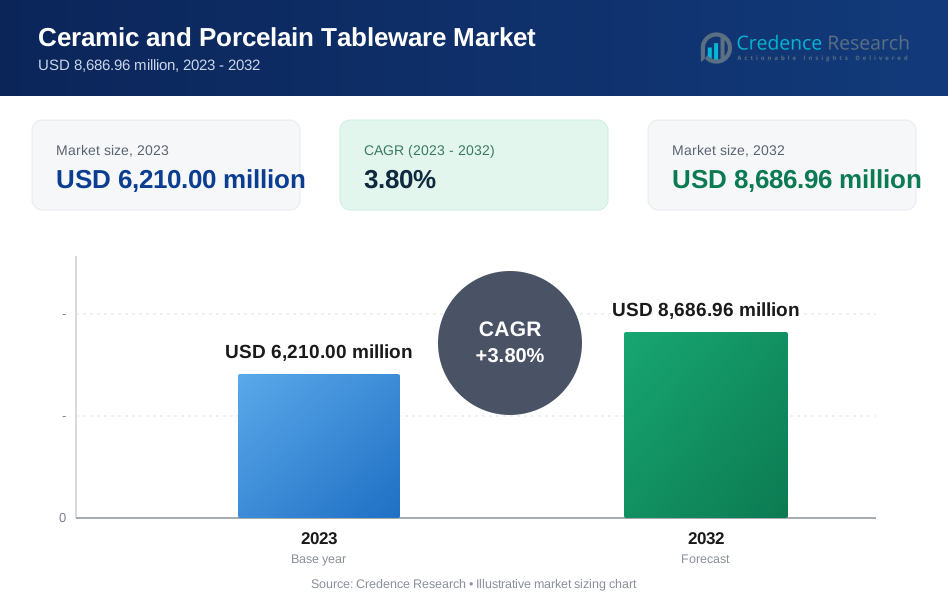
The global Ceramic and Porcelain Tableware Market is projected to grow from USD 6,210.00 million in 2023 to an estimated USD 8,686.96 million by 2032, with a compound annual growth rate (CAGR) of 3.80% from 2024 to 2032.
Several factors are fueling the growth of the ceramic and porcelain tableware market. The increasing demand for luxury and premium dining products in developed economies, along with the growing popularity of fine dining and home decor trends, has led to a surge in demand for high-quality tableware. Ceramic and porcelain tableware offer distinct advantages, including durability, aesthetic appeal, and versatility in design, making them the preferred choice for both casual and formal dining. The hospitality industry’s expansion, particularly in emerging economies, and the increasing trend of gift-giving during festive seasons are also driving the growth. Moreover, sustainability initiatives and the shift towards eco-friendly products further contribute to the demand for ceramic and porcelain tableware, as these materials are often considered more environmentally friendly compared to alternatives.
Regionally, Asia-Pacific holds the largest market share, driven by the significant demand from countries like China and India, where ceramic tableware has strong cultural roots. The region’s expanding middle class, rapid urbanization, and rising living standards are fueling the market’s growth. Europe follows closely, with countries such as Germany and Italy being key consumers due to their rich history and tradition in ceramics. North America is also a significant market for ceramic and porcelain tableware, supported by a growing trend for premium dining and consumer interest in artisanal products. Latin America and Middle East & Africa represent emerging markets, with increasing investments in the hospitality sector and growing demand for tableware products.
Market Insights
• The global Ceramic and Porcelain Tableware Market is projected to grow from USD 6,210.00 million in 2023 to USD 8,686.96 million by 2032, with a CAGR of 3.80% from 2024 to 2032.
• Rising disposable incomes, urbanization, and the growing interest in premium tableware are key drivers of market growth.
• Consumers are increasingly seeking personalized and customized tableware options, reflecting their individual tastes and preferences.
• Eco-friendly manufacturing practices and sustainable products are gaining traction as consumers prioritize environmentally responsible choices.
• Intense price competition, especially from low-cost manufacturers, and fluctuating raw material costs pose challenges for market growth.
• Asia-Pacific is expected to dominate the market, driven by high manufacturing capabilities and growing consumer demand in countries like China and India.
• The shift toward online retail channels is helping expand the market, providing convenience and greater access to a variety of tableware options.
Market Drivers:
Increasing Demand for Luxury and Premium Tableware
The demand for luxury and premium tableware is a key driver of the ceramic and porcelain tableware market. With rising disposable income, particularly in developed regions, consumers are increasingly opting for high-quality, aesthetically appealing tableware for their homes and dining experiences. This demand is also driven by the growing preference for fine dining and artisanal craftsmanship. For instance, Vigneto, a premium tableware brand, has introduced exquisitely embossed floral designs using state-of-the-art electric decal technology, which imparts a pearlescent, mirror-like finish to their porcelain products. Ceramic and porcelain offer an ideal combination of elegance, durability, and functionality, making them the material of choice for premium tableware. As people seek to enhance their dining experiences and showcase their personal style, demand for premium ceramic and porcelain tableware continues to rise, particularly among millennials and high-income households.
Expansion of the Hospitality Industry
The growth of the global hospitality industry is a significant driver of the ceramic and porcelain tableware market. As the number of restaurants, hotels, and cafes expands worldwide, the demand for quality tableware also increases. Ceramic and porcelain tableware is preferred in the hospitality industry due to its durability, ability to withstand frequent use, and aesthetic appeal. Additionally, the rise of luxury hotels and fine dining establishments further contributes to the demand for premium tableware that enhances the customer experience. For example, Steelite International has developed the Craft range, which features a hand-applied reactive glaze that creates a unique finish on each piece, ensuring no two items are exactly alike. The hospitality industry's increasing focus on customer experience and ambiance reinforces the demand for stylish and functional ceramic and porcelain tableware.
Sustainability and Eco-Friendly Products
Consumers' growing preference for sustainable and eco-friendly products is another major driver in the ceramic and porcelain tableware market. As environmental awareness rises, more consumers are looking for alternatives to plastic and other non-biodegradable materials. Ceramic and porcelain are seen as environmentally friendly options because they are durable, recyclable, and made from natural materials. Many manufacturers are also introducing eco-friendly production methods and non-toxic glazes, catering to the growing demand for sustainable and safe dining products. For instance, Stone Lain offers stoneware dinnerware sets that are free from harmful chemicals like lead and cadmium, and are microwave and dishwasher safe. This shift towards sustainability not only helps protect the environment but also aligns with consumers' preferences for products that are safer and more responsible.
Cultural and Traditional Preferences
Ceramic and porcelain tableware has a long-standing cultural significance, particularly in regions like Asia, where ceramics are an integral part of dining and cultural practices. In countries such as China and Japan, porcelain tableware has been used for centuries, and its cultural significance continues to drive demand in these regions. For example, Chinese blue and white porcelain is renowned for its exquisite designs and delicate craftsmanship, reflecting China's deep cultural roots and artistic achievements. Additionally, as global interest in different cultures and cuisines rises, the popularity of traditional tableware made from ceramic and porcelain materials is also growing. Consumers worldwide are drawn to the craftsmanship, history, and heritage associated with these products. Furthermore, ceramic and porcelain tableware is commonly used in gift-giving traditions during festive seasons, further fueling demand in both local and international markets.
Market Trends:
Customization and Personalization Demand
A significant trend in the Ceramic and Porcelain Tableware Market is the increasing demand for customization and personalization. Consumers are increasingly seeking unique, tailored tableware to reflect their individual style and preferences. For instance, BHS tabletop implements individual decors from 400 pieces upward, with their inglaze decoration process firing porcelain at 1,250 degrees Celsius, ensuring decorations can withstand at least 3,000 dishwasher cycles. This trend has been further driven by the rise of e-commerce platforms where consumers have access to a wide range of customizable options. The use of advanced technologies such as 3D printing is also making it easier for manufacturers to offer personalized designs and intricate patterns. This trend appeals to both younger, design-conscious consumers and those looking for special, one-of-a-kind products for occasions such as weddings, anniversaries, and holidays.
Blending Modern and Traditional Designs
There is a growing trend towards the integration of modern designs with traditional craftsmanship. While contemporary, minimalist styles are in demand, many consumers are also interested in products that combine modern aesthetics with time-honored techniques. Ceramic and porcelain tableware, often associated with artisanal craftsmanship, is being reimagined to cater to a broader range of tastes. This trend has led to the resurgence of handcrafted and artisanal elements in tableware products, creating a balance between innovation and heritage. Lemonade India combines traditional craftsmanship with modern personalization, producing ceramic plates that are microwave safe, dishwasher safe, and food grade safe, while maintaining artistic elements through manual printing processes. Consumers are drawn to these products for their quality, craftsmanship, and the cultural significance they represent, helping them stand out in a competitive market.
Technological Advancements in Production
Technological innovations in the manufacturing processes of ceramic and porcelain tableware are another important market trend. The introduction of automated production lines and robotic assistance has significantly improved efficiency, enabling manufacturers to meet rising demand for high-quality products faster and more cost-effectively. For instance, SACMI's automated production lines now feature drum mills with capacities ranging from 200 to 38,000 liters for grinding slip and glaze, complemented by advanced supervision systems for comprehensive quality control. Automation reduces labor costs, increases consistency, and minimizes errors, all while maintaining the integrity of the product. These advancements in manufacturing are also reducing waste and improving the overall sustainability of the production process, which is increasingly important to both manufacturers and environmentally conscious consumers.
Sustainability and Eco-Conscious Production
Sustainability continues to be a defining trend in the Ceramic and Porcelain Tableware Market. Consumers and manufacturers alike are increasingly prioritizing eco-friendly production practices. Ceramic and porcelain products are inherently more sustainable than alternatives made from plastics or other synthetic materials, but the industry's move towards greener practices is further being driven by rising awareness of environmental issues. Manufacturers are adopting energy-efficient production techniques, using recyclable materials, and focusing on non-toxic glazes to meet demand for sustainable tableware. For instance, Don Bellini recycles up to 6% of ceramics in their production process, with waste products being ground into fine powder and reused as raw materials. As eco-conscious consumer behavior increases, manufacturers are under pressure to minimize their environmental impact, aligning their products with growing global preferences for sustainable goods.
Market Challenges Analysis:
High Production Costs
One of the key challenges in the Ceramic and Porcelain Tableware Market is the high cost of production. Manufacturing ceramic and porcelain tableware involves a complex process that requires specialized raw materials, high-quality clay, and skilled labor. The high energy consumption associated with the firing process, which requires kilns to reach extremely high temperatures, adds to the overall production cost. Additionally, the incorporation of intricate designs and premium finishes further increases costs. As a result, manufacturers face pressure to balance quality with affordability, especially when competing with mass-produced, low-cost alternatives. This can make it difficult for smaller or newer companies to enter the market or for existing players to maintain competitive pricing while ensuring profitability.
Vulnerability to Raw Material Price Fluctuations
The price of raw materials, particularly clay, kaolin, feldspar, and other minerals used in the production of ceramic and porcelain tableware, can fluctuate significantly due to factors such as supply chain disruptions, geopolitical events, and changes in mining practices. These fluctuations can directly impact the production costs of tableware, making it difficult for manufacturers to maintain consistent pricing. The increasing demand for these materials in other industries, such as construction and manufacturing, further exacerbates this issue. Manufacturers may face challenges in ensuring a steady supply of high-quality raw materials, which can disrupt production schedules and affect market prices.
Environmental Concerns and Regulations
Environmental regulations are another significant restraint in the Ceramic and Porcelain Tableware Market. The production of ceramic and porcelain products requires significant energy input and generates emissions, which has led to growing concerns over the environmental impact of the industry. Stricter regulations surrounding emissions, energy usage, and waste management are increasing the pressure on manufacturers to adopt greener production practices. While some companies have responded by investing in energy-efficient technologies and sustainable practices, such as using recyclable materials and reducing water consumption, these efforts often come with high initial investment costs. Compliance with these regulations can, therefore, be a significant financial burden for manufacturers, especially small- and medium-sized enterprises.
Market Opportunities:
The Ceramic and Porcelain Tableware Market presents significant opportunities driven by rising consumer demand for premium dining experiences and sustainable products. As disposable incomes rise globally, particularly in emerging markets, consumers are increasingly opting for high-quality, durable, and aesthetically pleasing tableware to enhance their dining experience. This trend is further amplified by the growing interest in luxury dining and the desire for unique, personalized tableware. Manufacturers can capitalize on this opportunity by offering customized designs, intricate craftsmanship, and unique finishes that cater to consumer preferences for individuality and premium quality. The increasing inclination towards eco-friendly products also presents an opportunity, as more consumers demand tableware made from sustainable materials with minimal environmental impact. This shift toward sustainability is expected to expand market demand, particularly for porcelain and ceramic products, which are considered more environmentally responsible compared to plastic alternatives.
Additionally, the expansion of the hospitality industry in emerging economies represents another avenue for growth in the ceramic and porcelain tableware market. With the rise of fine dining, luxury hotels, and restaurants, the demand for high-end tableware is poised to increase. Regions like Asia-Pacific, driven by countries such as China, India, and Southeast Asia, are expected to witness rapid growth in the coming years due to increasing urbanization and rising standards of living. Manufacturers have the opportunity to tap into these growing markets by offering tailored solutions that meet both aesthetic and functional requirements. Investing in advanced manufacturing technologies that improve efficiency while reducing production costs also presents a valuable opportunity for companies to expand their market share in an increasingly competitive landscape.
Market Segmentation Analysis:
The ceramic and porcelain tableware market is segmented based on material, technology, product type, distribution channel, and region, each contributing to the market's overall growth trajectory.
By Material, the market includes Bone China, Porcelain, Stoneware, and Others. Porcelain dominates the segment due to its durability, versatility, and aesthetic appeal, making it suitable for both casual and formal dining. Bone China is highly sought after in the luxury segment for its lightweight yet sturdy nature and elegant appearance. Stoneware is gaining traction for everyday use due to its cost-effectiveness and robustness.
By Technology, the market comprises Slip Casting, Pressure Casting, Isostatic Casting, and Others. Slip casting remains widely used for mass production, while isostatic and pressure casting technologies are gaining popularity for producing high-quality, intricate designs efficiently.
By Product, the market includes Dinnerware, Beverage Ware, Cookware, and Others. Dinnerware holds the largest share, driven by increasing consumer interest in premium and stylish table settings. Beverage ware, including tea and coffee sets, is experiencing steady demand, particularly in emerging markets.
By Distribution Channel, the market is segmented into Supermarkets & Hypermarkets, Wholesalers & Retailers, and Online Platforms. Online channels are witnessing rapid growth, driven by e-commerce expansion and increasing consumer preference for convenient shopping.
Segmentation:
By Material:
- Bone China
- Porcelain
- Stoneware
- Others
By Technology:
- Slip Casting
- Pressure Casting
- Isostatic Casting
- Others
By Product:
- Dinnerware
- Beverage Ware
- Cookware
- Others
By Distribution Channel:
- Supermarket & Hypermarket
- Wholesalers & retailers
- Online
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Ceramic and Porcelain Tableware Market is experiencing significant growth globally, with regional dynamics shaped by consumer preferences, economic factors, and emerging trends.
North America remains a dominant force in the market, with the United States and Canada accounting for a large portion of the demand. The region's strong presence in premium and luxury tableware, driven by rising consumer spending, contributes to its market share. North American consumers continue to seek high-quality ceramic and porcelain products, with growing interest in custom designs and artisanal craftsmanship. The region also benefits from high online retail penetration, making premium tableware more accessible to a wider consumer base. The shift toward sustainability is further driving market growth, as consumers increasingly prefer eco-friendly, long-lasting products over disposable alternatives. For example, brands such as Lenox and Villeroy & Boch have capitalized on this demand by offering a range of sustainable and high-end porcelain products.
In Europe, demand for ceramic and porcelain tableware continues to thrive, driven by countries such as Italy, France, and Germany, which are renowned for their rich ceramic heritage. The region is known for a strong preference for high-quality, often handcrafted, tableware. The growing popularity of artisanal and bespoke designs has led to a rise in demand for unique porcelain collections. European consumers are also focused on sustainability, with eco-friendly production methods being highly valued. With the European Union’s Green Deal and other sustainability regulations, the market for environmentally conscious products continues to expand, encouraging brands to innovate while adhering to environmental standards. Countries like Italy are also seeing growth due to their strong tradition in ceramics, which fuels both local and export demand.
Asia-Pacific is poised for rapid growth, primarily due to rising disposable incomes, urbanization, and a burgeoning middle class in China, India, and Japan. This region holds significant promise, with China alone contributing to the growing consumption of ceramic tableware, thanks to the country's rich tradition in ceramics and porcelain. According to a report by the China National Ceramics Association, China's demand for ceramics in various sectors, including tableware, has grown significantly, fueled by rising living standards and consumer awareness. Similarly, India’s middle class is expanding, with increasing demand for premium dining products. Japan and South Korea also lead in adopting innovative tableware designs, influenced by both local culture and global trends. E-commerce growth in these markets is making ceramic and porcelain products more accessible, further driving demand.
Latin America and the Middle East & Africa (MEA) are emerging as key markets for ceramic and porcelain tableware, accounting for a growing share of global demand. In Brazil and Mexico, the demand for tableware is rising due to urbanization, a growing middle class, and increasing consumer interest in premium products. According to a study by Euromonitor, Brazil’s consumer goods market is shifting toward higher-quality products, and ceramic tableware is benefiting from this trend. In the MEA region, countries like Saudi Arabia and South Africa are witnessing greater interest in luxury products, driven by increasing disposable incomes and an expanding hospitality sector. As the region's infrastructure continues to develop, more people are investing in high-quality tableware, and this trend is further supported by the growth of the hospitality industry. The rise in tourism and the increasing number of restaurants and hotels also fuels demand for premium ceramic and porcelain products.
Key Player Analysis:
- Churchill China (UK) Limited
- Fiskars Group
- Lenox Corporation
- Lifetime Brands Inc.
- Noritake Co., Ltd
- RAK Ceramics PJSC
- Richard Ginori Srl
- Rosenthal GmbH
- Royal Doulton,
- Tognana Porcellane SpA
- Villeroy & Boch AG
- Wedgwood,
Competitive Analysis:
The Ceramic and Porcelain Tableware Market is highly competitive, with numerous global and regional players vying for market share. Leading companies, such as Villeroy & Boch, Lenox, Royal Doulton, and Wedgwood, dominate the premium segment by offering high-quality, luxurious products. These companies focus on innovation, craftsmanship, and sustainable production methods to differentiate their offerings. For instance, Royal Doulton continues to innovate with their use of high-quality bone china, which is known for its exceptional strength and translucency. They continuously introduce new designs and collections to meet evolving consumer preferences for unique, personalized tableware. Additionally, established players leverage strong brand reputations and extensive distribution networks, ensuring broad market reach. Emerging players, particularly from Asia-Pacific, are increasingly gaining traction by offering cost-effective alternatives without compromising on quality. Companies in China and India are capitalizing on the growing middle class and rising demand for affordable, durable tableware. To remain competitive, manufacturers are investing in advanced technologies, such as 3D printing and eco-friendly production processes, to enhance product appeal and reduce costs. The focus on sustainability and eco-conscious production is expected to intensify as the market continues to evolve.
Recent Developments:
- In November 2023, Villeroy & Boch launched an innovative eco-friendly tableware collection made from recycled ceramic materials. This initiative repurposes production waste and unsold items, reflecting the company’s strong commitment to sustainability and reducing environmental impact.
- In July 2023, Noritake Co., Limited expanded its e-commerce operations to adapt to changing consumer shopping preferences. The company focused on enhancing its online shopping experience to strengthen its digital presence and reach a broader customer base.
- In 2023, Steelite International introduced a new sustainable tableware range made from recycled glass. This move aligns with the rising demand for environmentally friendly dining solutions and highlights the company’s focus on sustainability-driven innovation.
Market Concentration & Characteristics:
The Ceramic and Porcelain Tableware Market is moderately concentrated, with a few large, established players holding significant market share. Leading companies, including Villeroy & Boch, Lenox, Royal Doulton, and Wedgwood, dominate the high-end segment by offering premium, artisanal products that cater to affluent consumers. These companies leverage their strong brand identities, extensive distribution networks, and consistent innovation to maintain market leadership. However, the market also has a notable presence of smaller, regional manufacturers, particularly in Asia-Pacific and Europe, that provide affordable and mass-market options. This dual structure allows for a blend of high-end, handcrafted products and more budget-friendly, mass-produced tableware. The market is characterized by an increasing focus on sustainability, with both large and small manufacturers incorporating eco-friendly materials and production processes. Additionally, advancements in digital technologies and customization are reshaping the competitive landscape, enabling greater product personalization and accessibility.
Report Coverage:
The research report offers an in-depth analysis based on By Material, By Technology, By Product and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for high-quality, customized ceramic and porcelain tableware will continue to rise as consumers seek personalized and unique products.
- Sustainability will be a key driver, with increasing demand for eco-friendly materials and production processes in response to consumer preferences.
- Online retail platforms will expand market reach, allowing consumers to easily access a wider variety of tableware products.
- Advancements in manufacturing technologies, including 3D printing, will enable faster, more efficient production and customization options.
- The rise of premium dining and luxury tableware will increase, driven by growing disposable incomes, particularly in emerging markets.
- As the hospitality industry continues to expand, there will be greater demand for high-end tableware for hotels, restaurants, and catering businesses.
- Regional players from Asia-Pacific will experience significant growth due to expanding middle-class populations and increasing demand for affordable, durable tableware.
- The market for ceramic and porcelain tableware will benefit from the ongoing trend of artisanal and handcrafted products that appeal to design-conscious consumers.
- Innovations in product designs, such as minimalist and contemporary styles, will attract younger, style-focused consumers.
- Manufacturers will focus on sustainability certifications and eco-friendly packaging to appeal to environmentally conscious buyers and comply with evolving regulations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the growth projection for the ceramic and porcelain tableware market?
What factors are driving market growth?
Which region holds the largest market share?
What are the challenges in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ceramic and Porcelain Tableware Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ceramic and Porcelain Tableware Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 6,210.00 million → 2032: USD 8,686.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ceramic and Porcelain Tableware Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ceramic and Porcelain Tableware Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ceramic and Porcelain Tableware Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ceramic and Porcelain Tableware Market Drivers
- 3.3 Ceramic and Porcelain Tableware Market Restraints & Challenges
- 3.4 Ceramic and Porcelain Tableware Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ceramic and Porcelain Tableware Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ceramic and Porcelain Tableware Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ceramic and Porcelain Tableware category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ceramic and Porcelain Tableware Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ceramic and Porcelain Tableware Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ceramic and Porcelain Tableware market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ceramic and Porcelain Tableware Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ceramic and Porcelain Tableware Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ceramic and Porcelain Tableware Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ceramic and Porcelain Tableware (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ceramic and Porcelain Tableware Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ceramic and Porcelain Tableware Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ceramic and Porcelain Tableware Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ceramic and Porcelain Tableware Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ceramic and Porcelain Tableware Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ceramic and Porcelain Tableware Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ceramic and Porcelain Tableware Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ceramic and Porcelain Tableware Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ceramic and Porcelain Tableware Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
