
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Chromatography Consumables Market Size 2021 | USD 296.74 million |
| Chromatography Consumables Market, CAGR | 12.40% |
| Chromatography Consumables Market Size 2022 | USD 333.53 million |
Chromatography Consumables Market Overview
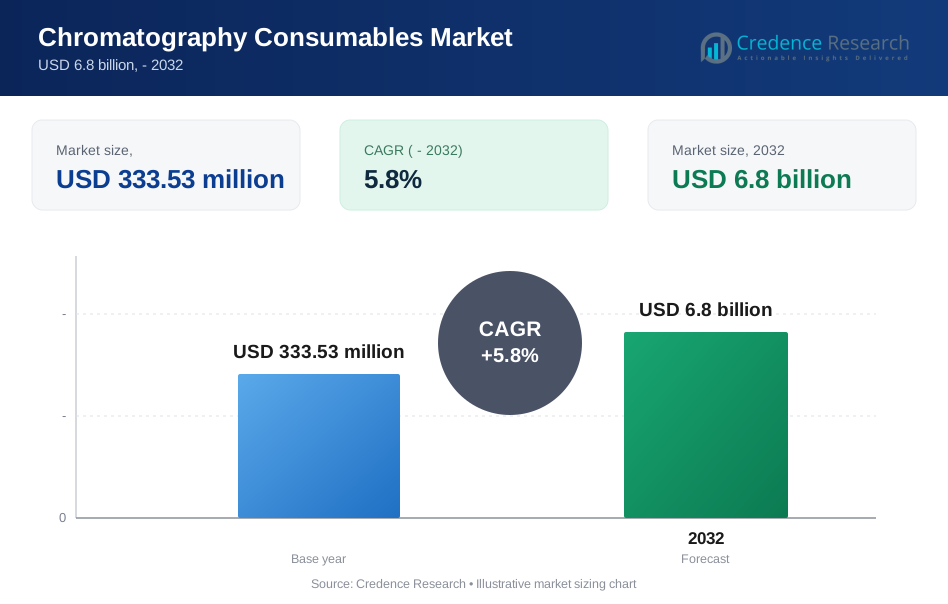
Chromatography Consumables market was valued at USD 296.74 million in 2021 and is poised to grow from USD 333.53 million in 2022 to USD 849.7 million by 2030, at a CAGR of 12.40% during the forecast period (2023–2030).
Several key drivers are propelling the growth of the chromatography consumables market. The rising prevalence of chronic diseases and the consequent increase in pharmaceutical and biotechnological research activities have significantly boosted the demand for chromatography consumables. Furthermore, stringent regulatory requirements for the quality and safety of food products and pharmaceuticals are driving the adoption of advanced chromatographic techniques. Technological advancements in chromatography systems, such as high-performance liquid chromatography (HPLC) and gas chromatography (GC), are also contributing to market growth by enhancing the efficiency and accuracy of analytical processes.
Regionally, North America dominates the chromatography consumables market, accounting for the largest share due to the presence of major pharmaceutical and biotechnology companies, advanced healthcare infrastructure, and significant investment in research and development. Europe follows closely, driven by stringent regulatory standards and a strong focus on environmental testing. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, fueled by increasing research activities, growing pharmaceutical and biotechnology industries, and rising awareness about the benefits of advanced analytical techniques. Emerging economies such as China and India are particularly notable for their expanding healthcare sectors and increasing investment in scientific research, which are anticipated to drive substantial market growth in the region.
Key Market Drivers of the Chromatography Consumables Market
Rising Prevalence of Chronic Diseases
The increasing prevalence of chronic diseases is a primary driver for the chromatography consumables market. As the incidence of diseases such as cancer, diabetes, and cardiovascular disorders rises, there is an elevated demand for advanced diagnostic and therapeutic solutions. According to the CDC, six in ten adults in the United States currently live with a chronic disease. Furthermore, chronic diseases are responsible for seven out of every ten deaths in the U.S., killing more than 1.7 million Americans every year. Chromatography plays a crucial role in drug development and quality control, leading to a surge in the need for consumables like columns, reagents, and solvents. The pharmaceutical and biotechnology sectors heavily rely on these consumables to ensure the efficacy and safety of their products, thus driving market growth.
Stringent regulatory requirements
Stringent regulatory requirements imposed by health authorities across the globe are significantly boosting the adoption of chromatography techniques. Regulatory bodies such as the FDA, EMA, and other national agencies mandate rigorous testing and quality assurance protocols for pharmaceuticals, food products, and environmental samples. Compliance with these standards necessitates the use of high-precision analytical tools, including chromatography systems and associated consumables. For instance, the FDA’s guidance on the validation of chromatographic methods presents issues to consider when evaluating chromatographic test methods from a regulatory perspective. This regulatory landscape ensures consistent demand for chromatography consumables as companies strive to meet quality and safety benchmarks.
Technological Advancements in Chromatography Systems
Technological advancements in chromatography systems are also a major market driver. Innovations such as high-performance liquid chromatography (HPLC), ultra-performance liquid chromatography (UPLC), and gas chromatography-mass spectrometry (GC-MS) have enhanced the accuracy, sensitivity, and speed of analytical processes. These advancements enable more efficient separation and analysis of complex mixtures, making chromatography an indispensable tool in research and quality control. As technology continues to evolve, the demand for consumables designed to optimize these sophisticated systems is expected to rise, further propelling market growth.
Expanding Applications Across Industries
The expanding applications of chromatography in various industries contribute significantly to the market's growth. Beyond pharmaceuticals and biotechnology, chromatography is extensively used in the food and beverage industry for quality control and safety testing, in environmental testing for pollutant analysis, and in the chemical and petrochemical industries for product purification. The versatility of chromatography techniques in addressing diverse analytical needs across multiple sectors drives the continuous demand for consumables, ensuring sustained market expansion.
Market Trends:
Increasing Adoption of Advanced Chromatography Techniques
One of the current trends in the chromatography consumables market is the increasing adoption of advanced chromatography techniques. High-performance liquid chromatography (HPLC), ultra-performance liquid chromatography (UPLC), and gas chromatography-mass spectrometry (GC-MS) are gaining traction due to their enhanced accuracy, speed, and sensitivity. For instance, global trends in GC or GC-MS include a desire for miniaturization, flexibility, and faster results. Full automation of sample preparation and multiple detection channels are helping to address the need for more specific and confident results with shorter turnaround times. These techniques allow for the efficient separation and analysis of complex mixtures, making them indispensable in pharmaceutical research, environmental testing, and food safety. The continuous development of these advanced techniques drives the demand for specialized consumables, such as high-quality columns and reagents, to optimize their performance.
Growth in Biopharmaceutical Research
The rapid growth in biopharmaceutical research is another significant trend impacting the chromatography consumables market. As the biopharmaceutical industry expands, there is a heightened need for precise analytical methods to ensure the quality and efficacy of biologics. Chromatography is extensively used in the characterization and purification of biomolecules, including proteins, antibodies, and nucleic acids. This increasing focus on biopharmaceuticals propels the demand for chromatography consumables tailored to these applications, such as affinity columns and specialized resins, to support the intricate processes involved in biopharmaceutical production.
Sustainability and eco-friendly consumables
Sustainability and eco-friendliness are becoming prominent trends in the chromatography consumables market. There is a growing emphasis on reducing environmental impact through the use of green chromatography techniques and sustainable consumables. Manufacturers are developing eco-friendly solvents, recyclable columns, and biodegradable materials to meet the increasing demand for environmentally responsible laboratory practices. This trend not only addresses regulatory pressures but also aligns with the broader movement toward sustainability in scientific research and industrial applications.
Integration of Automation and Digitalization
The integration of automation and digitalization in chromatography processes is a key trend shaping the market. Automated chromatography systems and digital tools for data analysis enhance the efficiency, reproducibility, and accuracy of analytical workflows. Automation reduces human error and increases throughput, while digitalization enables real-time monitoring and advanced data analytics. This trend is driving the demand for consumables compatible with automated and digital systems, such as pre-packed columns and sensor-equipped reagents, facilitating seamless integration and improved performance in modern laboratories.
Key market restraints
High Costs of Chromatography Consumables
One of the key market restraints in the chromatography consumables market is the high cost associated with these products. High-quality columns, reagents, solvents, and other consumables necessary for advanced chromatography techniques come at a significant expense. This financial burden can be particularly challenging for small and medium-sized enterprises (SMEs) and research institutions with limited budgets. The high costs may deter the adoption of advanced chromatography methods, potentially slowing market growth.
Complexity of Chromatography Techniques
The inherent complexity of chromatography techniques presents another significant challenge. Advanced chromatography methods require specialized knowledge and skills to operate and maintain the equipment effectively. This complexity can lead to operational inefficiencies and increased training costs, particularly in industries and regions where skilled personnel are scarce. The steep learning curve associated with these techniques can limit their widespread adoption, thereby impacting the overall growth of the chromatography consumables market.
Stringent Regulatory Requirements
While regulatory requirements drive the demand for chromatography consumables, they also pose significant challenges. Compliance with stringent regulations involves rigorous testing and validation processes, which can be time-consuming and costly. Regulatory bodies frequently update standards, necessitating continuous adaptation and investment in new technologies and consumables. This constant need to stay compliant can strain resources and hinder market growth, particularly for smaller companies and new market entrants.
Environmental Concerns and Disposal Issues
Environmental concerns and disposal issues associated with chromatography consumables are increasingly becoming critical challenges. Many consumables, such as solvents and reagents, can be hazardous and require careful handling and disposal to prevent environmental contamination. The costs and logistics involved in the safe disposal of these materials add an extra layer of complexity for laboratories and industries. Growing awareness and stricter environmental regulations further amplify these challenges, pushing companies to seek more sustainable and eco-friendly solutions, which may require significant investment and innovation.
Segmentation:
Chromatography: Consumables Market by Type
- Columns
- Pre-packed Columns
- Analytical Columns
- Preparative Columns
- Empty Columns
- Pre-packed Columns
- Fittings and tubing
- Tubing
- Tubing
- Ferrules and nuts
- Valves and gauges
- Liners and seals
- Vials and well plates
- Vials
- Well Plates
- Syringe Filters
- Other Consumables
Chromatography Consumables Market, by Technology
- Liquid Chromatography
- HPLC
- UPLC
- Low-pressure liquid chromatography
- Flash Chromatography
- Other liquid chromatography technologies
- Gas Chromatography
- Other Technologies
Chromatography Consumables Market, by End User
- Food & Beverage Industry
- Academic and Research Institutes
- Oil & Gas Industry
- Hospitals and Clinics
- Environmental Agencies
- Pharmaceutical and Biotechnology Industries
- Other End Users
Segmentations Analysis:
By Type
The chromatography consumables market can be segmented by type into columns, solvents, reagents, and other consumables. Columns, including HPLC, GC, and affinity columns, represent the largest segment due to their critical role in the separation process. Solvents, which are essential for mobile phases in liquid chromatography, also hold a significant market share. Reagents, including derivatizing agents and ion-pairing reagents, are vital for enhancing detection and separation efficiency. Other consumables, such as vials and filters, support various chromatography workflows, contributing to the market's overall growth.
By Technology
Segmentation by technology includes high-performance liquid chromatography (HPLC), gas chromatography (GC), ultra-performance liquid chromatography (UPLC), and others. HPLC dominates the market due to its widespread application in pharmaceuticals, biotechnology, and environmental analysis. GC is extensively used in the petrochemical, food and beverage, and environmental sectors for its efficiency in analyzing volatile compounds. UPLC, known for its higher resolution and faster analysis, is gaining traction, particularly in pharmaceutical research and development. Other technologies, such as thin-layer chromatography (TLC) and supercritical fluid chromatography (SFC), also contribute to the market, but to a lesser extent.
Key players:
- Merck KGaA (Germany),
- Bio-Rad Laboratories, Inc. (U.S.),
- Thermo Fisher Scientific Inc. (U.S.),
- Agilent Technologies, Inc. (U.S.),
- Waters Corporation (U.S.),
- PerkinElmer, Inc. (U.S.),
- Shimadzu Corporation (Japan).
- Danaher Corporation (U.S.),
- Hitachi High-Tech Corporation (Japan),
- Bruker Corporation (U.S.),
Competitive Analysis:
The chromatography consumables market is highly competitive, characterized by the presence of several key players, including Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Merck KGaA, and PerkinElmer. These companies dominate the market through extensive product portfolios, advanced technological capabilities, and strong global distribution networks. Continuous innovation and significant investments in research and development allow these players to offer cutting-edge consumables that cater to evolving industry demands.
Emerging companies and regional players also contribute to the competitive landscape by offering cost-effective and specialized products and targeting niche markets and specific applications. Strategic collaborations, mergers and acquisitions, and geographic expansion are common strategies adopted by these companies to enhance their market presence. The competitive environment drives continuous advancements and ensures a diverse range of high-quality consumables, benefiting end users across various industries.
Recent Developments:
- In June 2023, Waters established a strategic partnership with Sartorius to offer integrated process analytics and optimized chromatography consumables. This partnership aims to integrate Sartorius’ Resolute® BioSMBTM multi-column chromatography system with Waters’ PATROLTM UltraPerformance Liquid Chromatography (UPLCTM) Process Analysis system, making downstream biomonitoring cost-effective and reducing the amount of chromatography resins used.
- In July 2023, Valmet announced the acquisition of Siemens' Process Gas Chromatography business. Valmet intends to strengthen its automation segment and process automation by adding Siemens' process industry gas chromatography system and process analyzer systems to its offering.
- In February 2023, Biotage acquired Astrea Bioseparations to advance its chromatography product portfolio in biologics and advanced therapeutics.
- In 2021, Waters Corporation launched the ACQUITY PREMIER LC Solution and Arc Premier system, featuring the company’s High-Performance Surface (HPS) technology. These products offer higher sensitivity and support faster analysis.
- In 2022, Shimadzu Corporation introduced the sample preparation module CLAM-2040, a fully automated module that supports faster sample preparation.
- In 2021, Thermo Fisher Scientific launched a new chromatography solution designed to support researchers with advanced capabilities.
- In December 2020, Waters Corporation collaborated with Dr. Sunghwan Kim of Kyungpook National University to use its Select Series Cyclic IMS system to investigate compounds in complex mixtures, such as petroleum and advanced materials used in electronics.
- In November 2020, Thermo Fisher Scientific entered into a collaborative agreement with the Biopharmaceutical Analysis Training Laboratory (BATL) at Northeastern University to advance analytical capabilities using Thermo Fisher's ultra-high-performance liquid chromatography-mass spectrometry (UHPLC-MS) technology.
- In October 2020, Thermo Fisher Scientific extended its strategic collaboration with Symphogen A/S to utilize its analytical and chromatographic capabilities for developing, testing, and routinely implementing platform workflows for intact and native mass analysis of therapeutic monoclonal antibody (mAb) mixtures.
- In September 2020, Waters Corporation established Immerse Cambridge, a new research laboratory in Cambridge’s Kendall Square, dedicated to innovation, discovery, and accelerating the next generation of scientific advancements.
- In January 2020, PerkinElmer collaborated with Emerald Scientific to utilize its high throughput, advanced instruments, and regulatory-compliant software for cannabis and hemp testing.
Market Concentration and Characteristics of the Chromatography Consumables Market
The chromatography consumables market is characterized by a high degree of market concentration, with several leading players such as Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Merck KGaA, and PerkinElmer dominating the industry. These companies hold significant market shares due to their extensive product portfolios, advanced technological capabilities, and strong global distribution networks.
The market exhibits robust competition, driven by continuous innovation and substantial investments in research and development. Key characteristics include the rapid adoption of advanced chromatographic techniques, stringent regulatory requirements, and increasing applications across diverse industries such as pharmaceuticals, biotechnology, food and beverage, and environmental testing. The market also shows a trend towards sustainability, with growing emphasis on eco-friendly consumables and green chromatography techniques. This competitive and dynamic environment ensures ongoing advancements and a wide range of high-quality consumables for various analytical needs.
Report Coverage:
The research report offers an in-depth analysis based on type, technology, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook of the Chromatography Consumables Market
- The chromatography consumables market is projected to continue its robust growth, driven by increasing demand across the pharmaceutical, biotechnology, and environmental sectors.
- Continuous innovation in chromatography techniques, such as high-performance liquid chromatography (HPLC) and gas chromatography (GC), will enhance efficiency and accuracy, driving market expansion.
- The rising focus on biopharmaceuticals and advanced therapeutics will significantly boost the demand for specialized chromatography consumables.
- Growing emphasis on sustainability will lead to the development and adoption of eco-friendly and recyclable chromatography consumables.
- Increased integration of automation and digitalization in chromatography processes will drive demand for compatible consumables that enhance workflow efficiency.
- Stricter regulatory requirements will continue to propel the adoption of high-precision chromatography techniques and consumables, ensuring product quality and safety.
- Expansion in emerging markets, particularly in Asia-Pacific, will offer substantial growth opportunities due to rising investments in healthcare and scientific research.
- Strategic collaborations and partnerships among key players will foster innovation and broaden product offerings in the market.
- Demand for customized and application-specific chromatography consumables will increase, catering to the unique needs of various industries.
- Enhanced educational and training initiatives will address the skills gap, promoting efficient use and maintenance of advanced chromatography systems and thereby supporting market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and projected growth of the global chromatography consumables market?
What are the key drivers of growth in the chromatography consumables market?
Which regions are leading the chromatography consumables market, and why?
How are emerging economies contributing to the growth of the chromatography consumables market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chromatography Consumables Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chromatography Consumables Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 333.53 million → 2032: USD 6.8 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chromatography Consumables Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chromatography Consumables Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chromatography Consumables Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chromatography Consumables Market Drivers
- 3.3 Chromatography Consumables Market Restraints & Challenges
- 3.4 Chromatography Consumables Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chromatography Consumables Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chromatography Consumables Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chromatography Consumables category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chromatography Consumables Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chromatography Consumables Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chromatography Consumables market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chromatography Consumables Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chromatography Consumables Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chromatography Consumables Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chromatography Consumables (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chromatography Consumables Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chromatography Consumables Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chromatography Consumables Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chromatography Consumables Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chromatography Consumables Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chromatography Consumables Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chromatography Consumables Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chromatography Consumables Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chromatography Consumables Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
