
Market overview
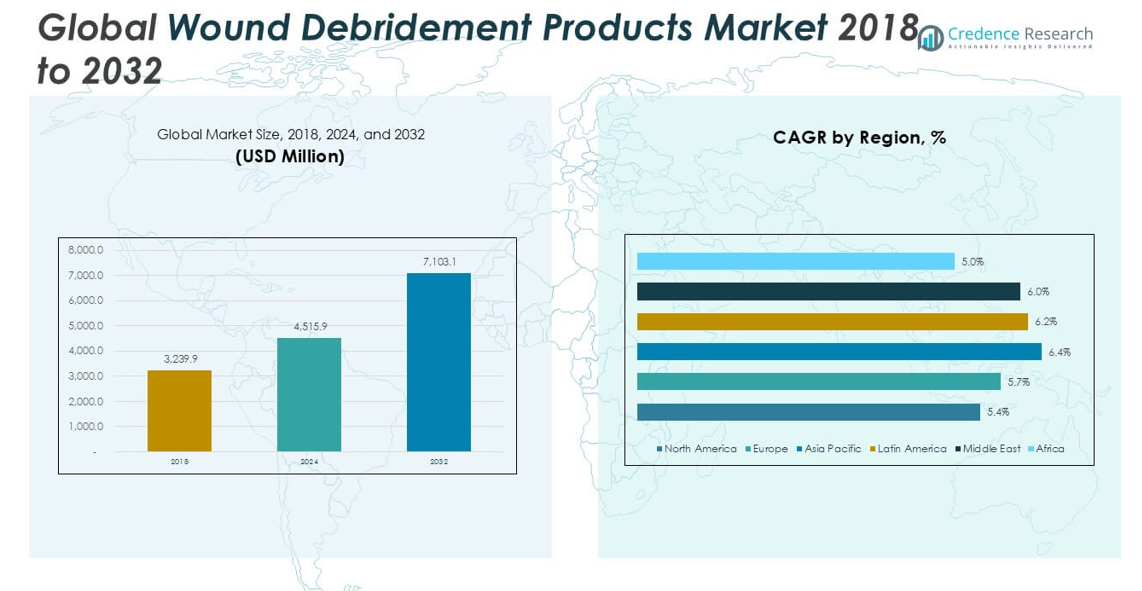
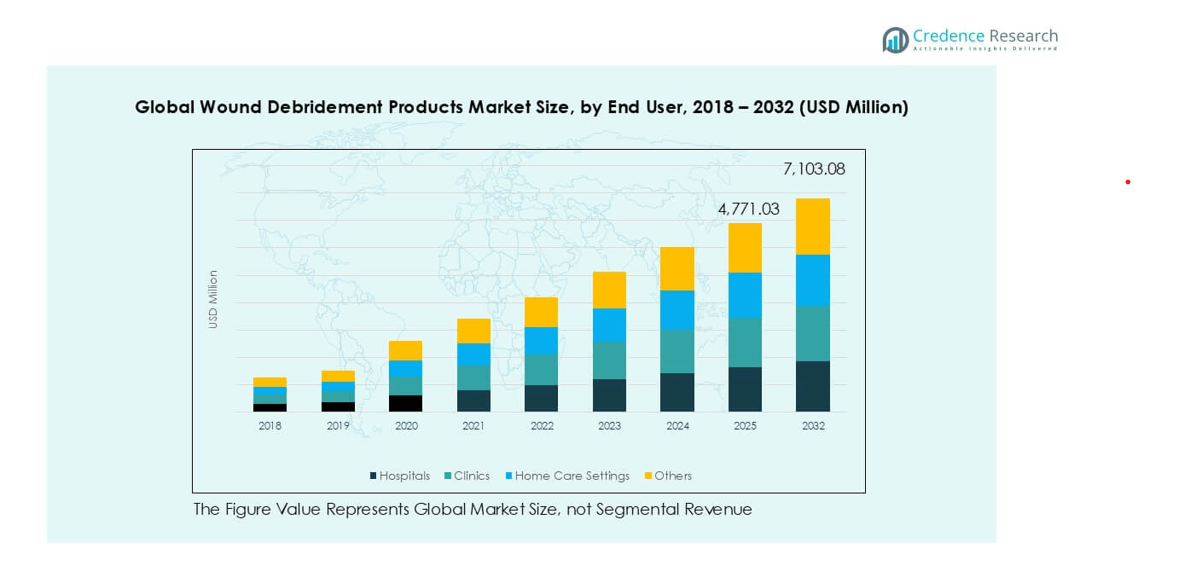
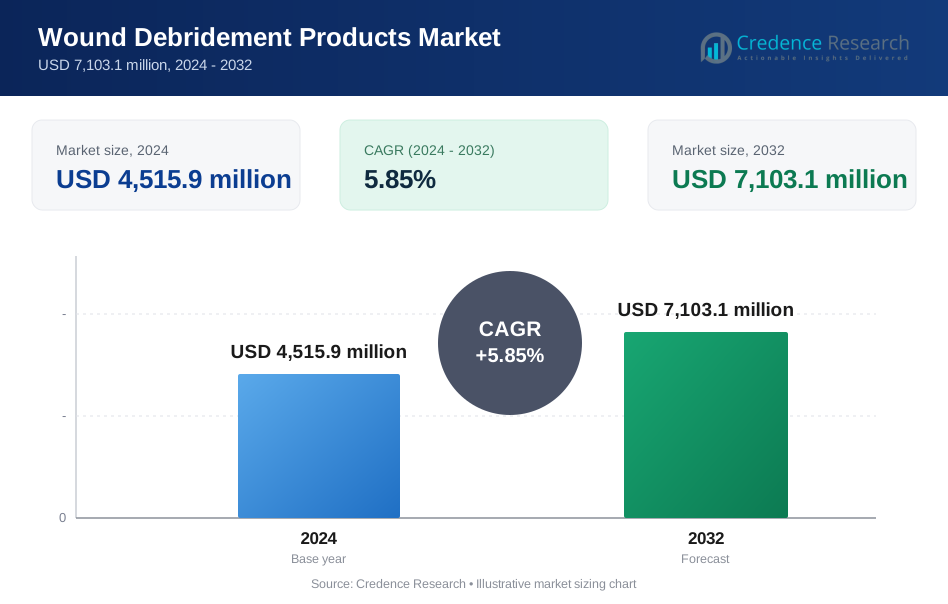
The Global Wound Debridement Products market size was valued at USD 3,239.9 million in 2018 and increased to USD 4,515.9 million in 2024. It is anticipated to reach USD 7,103.1 million by 2032, growing at a CAGR of 5.85% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wound Debridement Products Market Size 2024 | USD 4,515.9 million |
| Wound Debridement Products Market, CAGR | 5.85% |
| Wound Debridement Products Market Size 2032 | USD 7,103.1 million |
The global wound debridement products market is led by major players such as Smith & Nephew plc, B. Braun, Mölnlycke Health Care, Coloplast A/S, Integra LifeSciences, Solventum, Schülke & Mayr GmbH, Lotus Surgicals Pvt Ltd, Misonix, Bioventus, and Esacrom Srl. These companies strengthen their positions through diverse portfolios, technological innovations, and expanding global reach. In 2024, North America dominated with 33.1% share, driven by advanced healthcare infrastructure and high adoption of modern debridement methods. Asia Pacific followed with 26.9%, benefiting from rising diabetes prevalence and healthcare investments, while Europe accounted for 22.0%, supported by strong reimbursement systems. This competitive environment continues to push innovation and regional expansion strategies among top players.
Market Insights
- The global wound debridement products market was valued at USD 4,515.9 million in 2024 and is projected to reach USD 7,103.1 million by 2032, growing at a CAGR of 5.85%.
- Key drivers include the rising burden of chronic wounds, increasing diabetic and geriatric populations, and growing demand for advanced debridement methods such as ultrasonic devices and enzymatic gels.
- Market trends highlight the shift toward minimally invasive solutions, integration of digital wound monitoring, and the growing preference for home care settings, which boost adoption of easy-to-use gels and ointments.
- The competitive landscape is dominated by players like Smith & Nephew, B. Braun, Mölnlycke Health Care, Coloplast A/S, and Integra LifeSciences, while niche players such as Misonix, Bioventus, and Lotus Surgicals expand through innovation and partnerships.
- North America led with 33.1% share in 2024, followed by Asia Pacific at 26.9% and Europe at 22.0%; among products, gels accounted for over 30% share.
Market Segmentation Analysis:
By Product
In 2024, gels emerged as the dominant sub-segment in the wound debridement products market, holding over 30% share. Their leadership is supported by ease of application, faster healing outcomes, and strong adoption in both acute and chronic wound care. Ointments and creams follow closely, driven by demand for moisture-retentive formulations. Medical gauzes and mechanical debridement pads remain widely used in conventional care, while ultrasonic devices are gaining traction with advanced hospitals adopting technology-driven wound treatment. The “Others” category, including sprays and solutions, reflects expanding innovation and diversified treatment approaches.
- For instance, Smith & Nephew Intrasite Hydrogel Dressing is widely used to maintain moist wound environments and assist autolytic debridement in diabetic foot ulcers.
By Wound Type
Diabetic foot ulcers accounted for the largest share of the market in 2024, representing more than 35% share. The dominance is linked to the global rise in diabetes prevalence and the increasing incidence of chronic wounds requiring specialized debridement. Venous leg ulcers form the next major segment, supported by aging populations and vascular disease cases. Burn wounds contribute significantly due to trauma-related admissions, while surgical and traumatic wounds are expanding with rising surgical procedures worldwide. Advanced debridement methods, especially for diabetic and vascular-related wounds, continue to drive demand across these categories.
- For instance, in chronic diabetic ulcers, gels and dressings (like hydrogels) are used for repeated debridement cycles with minimal trauma.
By End User
Hospitals led the end-user segment in 2024, securing above 40% share of the market. Their dominance comes from high patient volumes, access to advanced technologies, and specialized wound care units. Clinics represent the second-largest share, supported by outpatient wound management and growing use of minimally invasive debridement solutions. Home care settings are expanding rapidly as patient preference for cost-effective, at-home treatment increases, particularly among elderly and chronic wound patients. The “Others” category includes long-term care centers and military facilities, showing steady adoption of wound debridement products for diverse healthcare needs.
Key Growth Drivers
Rising Burden of Chronic Wounds
The increasing prevalence of chronic wounds, such as diabetic foot ulcers, venous leg ulcers, and pressure ulcers, is a major driver for the wound debridement products market. With the global rise in diabetes, obesity, and vascular diseases, the number of patients requiring long-term wound care continues to escalate. Diabetic foot ulcers alone account for a significant share of chronic wound-related hospitalizations, demanding effective and advanced debridement methods. This trend has prompted healthcare providers to adopt specialized debridement products, including enzymatic gels, ultrasonic devices, and advanced dressings. In addition, longer life expectancy and the expanding geriatric population, who are more prone to non-healing wounds, further fuel market demand. As chronic wounds often result in complications such as infections or amputations if untreated, the need for effective debridement solutions remains critical. This factor significantly strengthens product penetration in hospitals, clinics, and home care settings, driving steady market growth.
- For instance, a clinical study demonstrated that the VERSAJET Hydrosurgery System reduced the debridement procedure time for lower extremity ulcers (including diabetic foot ulcers) by an average of 6.9 minutes compared to conventional surgical debridement
Technological Advancements in Debridement Methods
Continuous innovation in wound care technology is fueling the adoption of advanced wound debridement products. Traditional methods, such as mechanical pads and gauzes, are increasingly being replaced or supplemented with high-efficiency options like ultrasonic devices, enzymatic debridement gels, and hydrogels that accelerate tissue regeneration. Ultrasonic devices, in particular, are gaining strong traction due to their precision in removing necrotic tissue while minimizing patient discomfort. Enzymatic and autolytic products also support less invasive care, aligning with the growing preference for patient-friendly treatments. Companies are heavily investing in R&D to launch targeted formulations and device-based solutions with improved healing outcomes. Furthermore, the integration of digital wound monitoring with advanced debridement methods enhances treatment outcomes by enabling timely interventions. These innovations not only improve clinical efficacy but also reduce treatment time and overall healthcare costs, making advanced debridement products more attractive to healthcare providers worldwide.
- For instance, the VERSAJET III Hydrosurgery System combines cutting, excision, and removal of non-viable tissue in a single pass.
Growing Preference for Outpatient and Home Care Settings
A significant driver of the wound debridement products market is the growing shift toward outpatient care and home-based treatment. Patients increasingly prefer home care solutions due to lower costs, convenience, and reduced risk of hospital-acquired infections. Home care settings particularly favor gels, ointments, and portable mechanical or enzymatic debridement solutions that are easy to apply without medical supervision. Additionally, healthcare systems encourage outpatient wound care as it helps reduce the burden on hospitals and improves resource allocation. The aging population, who often require long-term wound management, further supports this trend. Insurance providers and reimbursement frameworks in several countries are also adapting to cover wound debridement treatments in home care environments. The rising demand for cost-effective yet efficient wound management products continue to expand market opportunities beyond hospitals and clinics. This transition from institutional to home-based care remains a strong driver, accelerating the adoption of patient-centric debridement solutions globally.
Key Trends & Opportunities
Shift Toward Advanced Debridement Technologies
One of the key trends shaping the market is the increasing adoption of advanced technologies such as ultrasonic devices and enzymatic gels. These products provide faster, more effective, and less painful debridement compared to traditional mechanical pads and gauzes. The growing acceptance of minimally invasive methods reflects a shift in both patient and provider preferences. Opportunities lie in expanding the use of these technologies across emerging markets where advanced wound care adoption remains low but rapidly growing. Manufacturers introducing cost-effective versions of ultrasonic and enzymatic products can gain significant market share.
- For instance, the Söring UAW ultrasonic system operates at 25 kHz to remove devitalized tissue selectively with minimal damage to healthy tissue.
Rising Integration of Digital Solutions in Wound Care
The integration of digital monitoring and telemedicine with wound debridement practices is opening new opportunities. Digital wound imaging tools and connected platforms enable clinicians to remotely assess wound progression and adjust treatment protocols accordingly. This trend supports the home care shift, allowing physicians to oversee patient progress without frequent hospital visits. Combining advanced debridement products with digital platforms enhances efficiency and patient compliance. Companies focusing on combining their products with digital wound care ecosystems are likely to gain competitive advantages in both developed and developing markets.
Expansion in Emerging Markets
The wound debridement products market is experiencing increased opportunities in emerging economies due to growing healthcare investments, rising diabetes prevalence, and expanding access to modern wound care. Regions such as Asia-Pacific, Latin America, and parts of the Middle East are witnessing improvements in healthcare infrastructure and affordability. As awareness of advanced wound care solutions rises among both patients and healthcare providers, demand for modern debridement products is expected to grow rapidly. Manufacturers who tailor their product portfolios to cost-sensitive markets stand to gain significant traction in these regions.
Key Challenges
High Cost of Advanced Debridement Products
The cost of advanced wound debridement products, such as ultrasonic devices and enzymatic formulations, remains a significant barrier to widespread adoption, especially in low- and middle-income countries. While these solutions offer superior clinical outcomes, the high upfront price limits their accessibility in cost-sensitive markets. Hospitals in developing regions often rely on traditional and low-cost alternatives like gauzes and pads due to budget constraints. Lack of favorable reimbursement policies further hampers patient adoption. Addressing affordability without compromising on efficacy remains a critical challenge for manufacturers aiming to expand their market reach.
Shortage of Skilled Wound Care Specialists
Effective wound debridement often requires trained professionals to apply advanced methods such as enzymatic or ultrasonic debridement. However, there is a global shortage of wound care specialists, particularly in developing regions. Limited access to expertise reduces the proper use of advanced products and can delay patient recovery. Even in developed healthcare systems, uneven distribution of specialists creates treatment gaps. Training programs and broader clinical education are needed to address this shortage. Without adequate skilled professionals, the adoption of advanced wound debridement products may remain restricted despite their proven benefits.
Regional Analysis
North America
North America dominated the wound debridement products market in 2024, accounting for 33.1% share, valued at USD 1,493.85 million. The region’s strong performance is driven by high prevalence of chronic wounds, an expanding elderly population, and advanced healthcare infrastructure. The U.S. leads adoption due to favorable reimbursement systems and availability of cutting-edge technologies such as ultrasonic devices. Rising surgical procedures and greater patient awareness also sustain market demand. By 2032, the regional market is projected to reach USD 2,272.98 million, reflecting a steady CAGR of 5.4% during the forecast period.
Europe
Europe held the second-largest position in the market in 2024, with 22.0% share at USD 992.07 million. Demand is supported by an increasing diabetic and geriatric population across countries such as Germany, France, and the U.K. Well-established hospital care systems and regulatory focus on advanced wound management contribute to steady product adoption. Reimbursement coverage for chronic wound treatments further strengthens the market. With a projected CAGR of 5.7%, Europe’s market is expected to reach USD 1,547.05 million by 2032, highlighting consistent growth in advanced wound care adoption.
Asia Pacific
Asia Pacific emerged as the fastest-growing regional market, capturing 26.9% share in 2024 with revenues of USD 1,215.67 million. Growth is led by rising diabetes prevalence, expanding healthcare investments, and increasing awareness of advanced wound management. Countries such as China, India, and Japan are at the forefront, benefiting from improving infrastructure and greater access to innovative debridement technologies. The region’s cost-sensitive markets create opportunities for affordable product variants. With a CAGR of 6.4%, Asia Pacific is forecasted to reach USD 1,988.86 million by 2032, reinforcing its role as a high-potential growth hub.
Latin America
Latin America represented 11.0% share of the global market in 2024, valued at USD 495.52 million. Growth is supported by the increasing incidence of diabetes-related wounds, rising healthcare expenditure, and improving availability of wound care products. Brazil and Mexico drive regional demand due to expanding hospital networks and medical tourism. However, limited reimbursement policies restrict broader adoption of advanced solutions. The region is expected to expand at a CAGR of 6.2%, reaching USD 797.68 million by 2032, with opportunities emerging in cost-effective debridement solutions tailored to regional affordability.
Middle East
The Middle East accounted for 4.8% share in 2024, generating USD 218.18 million. Rising investments in healthcare infrastructure, particularly in the Gulf Cooperation Council (GCC) countries, support the adoption of advanced wound management products. Increasing trauma cases, burn injuries, and surgical procedures contribute to market growth. However, adoption remains concentrated in urban centers due to cost barriers in smaller economies. The market is projected to expand at a CAGR of 6.0%, reaching USD 348.05 million by 2032, driven by government focus on modernizing healthcare facilities and diversifying treatment options.
Africa
Africa remained the smallest market, with 2.2% share in 2024, valued at USD 100.58 million. Limited access to advanced healthcare infrastructure and cost barriers restrict widespread adoption of innovative wound care solutions. However, growing awareness of diabetic and chronic wound management, along with international aid programs, is gradually supporting adoption of basic debridement products such as gauzes and gels. South Africa leads regional demand, followed by Nigeria and Kenya. With a CAGR of 5.0%, Africa’s market is anticipated to reach USD 148.45 million by 2032, reflecting gradual yet steady progress.
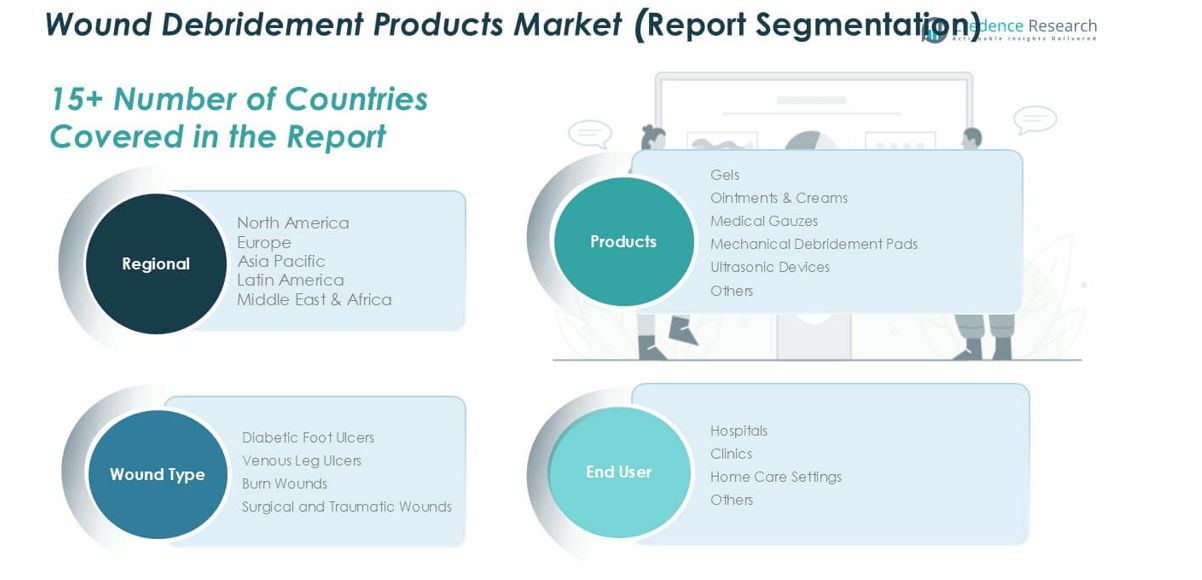
Market Segmentations:
By Product
- Gels
- Ointments & Creams
- Medical Gauzes
- Mechanical Debridement Pads
- Ultrasonic Devices
- Others
By Wound Type
- Diabetic Foot Ulcers
- Venous Leg Ulcers
- Burn Wounds
- Surgical and Traumatic Wounds
By End User
- Hospitals
- Clinics
- Home Care Settings
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global wound debridement products market is characterized by strong competition, with multinational players and specialized regional companies shaping the landscape. Leading manufacturers such as Smith & Nephew plc, B. Braun, Mölnlycke Health Care, and Coloplast A/S hold substantial shares through their diverse portfolios, advanced technologies, and wide distribution networks. Companies like Integra LifeSciences, Bioventus, Misonix, and Solventum are expanding their presence with product innovations in enzymatic, mechanical, and ultrasonic debridement. Meanwhile, Schülke & Mayr GmbH, Lotus Surgicals, and Esacrom Srl focus on niche products, addressing specific patient and clinical needs. Strategic initiatives including mergers, acquisitions, partnerships, and product launches drive growth and strengthen market positioning. Investment in R&D for minimally invasive and patient-friendly solutions remains a key differentiator among top competitors. The competition also extends into emerging markets, where affordability and accessibility provide opportunities for local players, intensifying rivalry across global and regional segments.
Key Player Analysis
- Smith & Nephew plc
- Braun
- Mölnlycke Health Care
- Coloplast A/S
- Integra LifeSciences
- Solventum
- Schülke & Mayr GmbH
- Lotus Surgicals Pvt Ltd
- Misonix, Inc.
- Bioventus
- Esacrom Srl
- Other Key Players
Recent Developments
- In May 2025, a peer‑reviewed post-hoc analysis in Wounds confirmed EscharEx outperformed collagenase (SANTYL®) in terms of debridement speed and healthy tissue formation, underscoring its clinical potential.
- In February 2025, MediWound initiated a global, randomized, double-blind Phase III study assessing EscharEx, a bromelain-based enzymatic debrider, in venous leg ulcer treatment across 40 U.S. and European sites. An interim analysis is expected mid‑2026.
- In April 2025, MediWound showcased new findings at two major wound-care conferences, highlighting EscharEx’s selective proteolytic activity, robust granulation tissue promotion, and efficacy in models of diabetic foot and venous leg ulcers.
- In October 2024, MediWound initiated a multicenter Phase II study comparing EscharEx to collagenase ointment in venous leg ulcers. The study supports their U.S. BLA submission and commercialization efforts.
- In April 2024, Mölnlycke AB agreed to acquire the Austrian manufacturer of Granudacyn wound cleansing and moisturizing solutions, P.G.F. Industry Solutions GmbH. This acquisition will help the company to strengthen its wound cleansing and moisturizing portfolio.
- In January 2024, Smith+Nephew, the medical technology firm, announced the completion of its acquisition of CartiHeal, the developer of Agili-C, an innovative sports medicine technology for cartilage regeneration in the knee.
Report Coverage
The research report offers an in-depth analysis based on Product, Wound Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily, driven by rising chronic wound cases.
- Advanced technologies like ultrasonic and enzymatic debridement will see wider adoption.
- Gels will maintain dominance as the most preferred product segment for wound care.
- Hospitals will remain the leading end-user due to high patient inflow and advanced facilities.
- Home care settings will expand rapidly, supported by aging populations and cost-effective treatment demand.
- Asia Pacific will record the fastest growth, driven by diabetes prevalence and healthcare investments.
- North America will retain leadership, supported by strong reimbursement systems and innovation adoption.
- Companies will increase R&D spending to develop less invasive and patient-friendly products.
- Strategic mergers, acquisitions, and collaborations will shape competition and global expansion.
- Greater integration of digital wound monitoring will enhance personalized treatment and compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Wound Debridement Products market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Wound Debridement Products market projected to grow between 2025 and 2032?
Which Global Wound Debridement Products market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Wound Debridement Products market?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wound Debridement Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wound Debridement Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,515.9 million → 2032: USD 7,103.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wound Debridement Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wound Debridement Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wound Debridement Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wound Debridement Products Market Drivers
- 3.3 Wound Debridement Products Market Restraints & Challenges
- 3.4 Wound Debridement Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wound Debridement Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wound Debridement Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wound Debridement Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wound Debridement Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wound Debridement Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wound Debridement Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wound Debridement Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wound Debridement Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wound Debridement Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wound Debridement Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wound Debridement Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wound Debridement Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wound Debridement Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wound Debridement Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wound Debridement Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wound Debridement Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wound Debridement Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wound Debridement Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wound Debridement Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
