
Market Overview
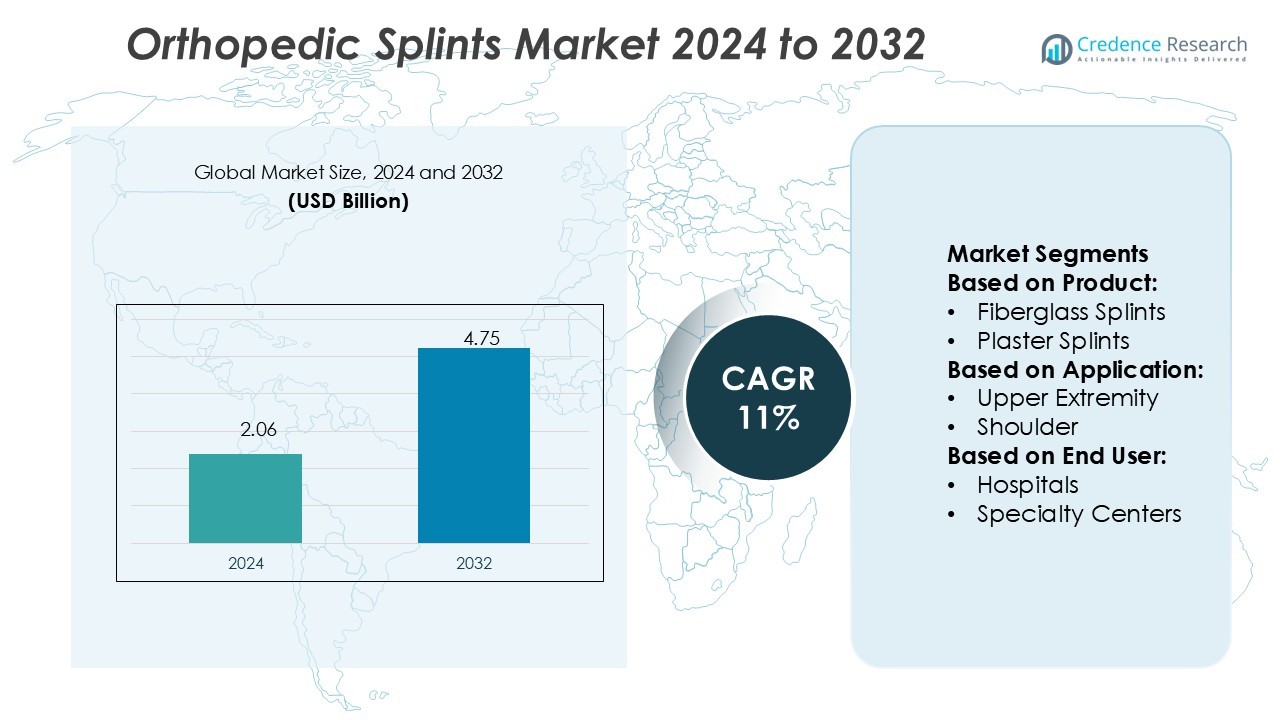
Orthopedic Splints Market size was valued USD 2.06 billion in 2024 and is anticipated to reach USD 4.75 billion by 2032, at a CAGR of 11% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Orthopedic Splints Market Size 2024 | USD 2.06 Billion |
| Orthopedic Splints Market, CAGR | 11% |
| Orthopedic Splints Market Size 2032 | USD 4.75 Billion |
The orthopedic splints market is shaped by prominent players including 3M, Becton, Dickinson and Company, Breg, Inc., DeRoyal Industries, Inc., DJO Global, Dynatronics Corporation, Essity AB, Medi GmbH & Co. KG, and Orthosys. These companies emphasize innovation in materials, lightweight designs, and patient-centric solutions to enhance treatment outcomes. Strategic partnerships, strong distribution channels, and advancements such as thermoplastic and fiberglass splints strengthen their competitive positions. Among regions, North America leads the market with a 38% share, supported by advanced healthcare infrastructure, higher adoption of innovative technologies, and increasing demand for effective fracture and injury management solutions.
Market Insights
- The orthopedic splints market size was valued at USD 2.06 billion in 2024 and is projected to reach USD 4.75 billion by 2032, at a CAGR of 11%.
- Rising incidence of fractures, sports injuries, and trauma cases drives demand, while technological advancements in fiberglass and thermoplastic splints improve comfort, durability, and recovery outcomes.
- The market shows strong trends toward customization, with 3D printing and lightweight materials gaining traction, and key players like 3M, DJO Global, and DeRoyal Industries, Inc. strengthening competitiveness through innovation and strategic partnerships.
- High costs of advanced splints and limited awareness in rural healthcare settings act as restraints, creating adoption challenges, especially in cost-sensitive regions.
- North America leads with 38% share supported by advanced healthcare infrastructure, while lower extremity applications dominate with 52% share, highlighting strong regional and segmental demand across hospitals and specialty centers.
Market Segmentation Analysis:
By Product
Fiberglass splints hold the dominant share in the orthopedic splints market, accounting for 46%. Their leadership is driven by lightweight construction, durability, and superior patient comfort compared to plaster alternatives. Fiberglass also allows faster setting time and better radiolucency, which supports accurate imaging during treatment. While plaster splints remain in use for cost-sensitive applications, adoption is declining due to heavier weight and lower durability. Tools and accessories support surgical procedures but form a smaller share. The segment’s growth reflects increasing preference for advanced, patient-friendly splinting materials.
- For instance, Norman Noble, Inc. invested in its proprietary athermal, ultra-short-pulse laser technology (Noble STEALTH), which produces the industry's narrowest laser-cut kerfs of 0.00025 inches (approx. 6.35 microns) in bioabsorbable materials.
By Application
Lower extremity applications dominate the market with a 52% share, led by high incidence of knee, ankle, and foot injuries. Rising cases of sports injuries, road accidents, and orthopedic conditions such as osteoarthritis fuel demand for these splints. Knee and ankle splints are particularly important in trauma care and rehabilitation, ensuring stability and faster recovery. Upper extremity applications such as shoulder, elbow, and wrist follow, supported by rising outpatient procedures. Growth in this segment is reinforced by the aging population and demand for mobility-preserving treatments across healthcare systems.
- For instance, Paragon Medical operates a 34,000 square-foot additive manufacturing facility dedicated to 3D printing porous titanium implant architectures, and its subtractive capabilities include machining tolerances down to 20 millionths of an inch with surface finishes reaching 1 microinch (40 millionths of an inch) in polishing.
By End-user
Hospitals account for the largest share at 61% in the orthopedic splints market, driven by high patient volumes, trauma admissions, and access to advanced splinting materials. They serve as the primary treatment centers for acute injuries, fractures, and post-surgical recovery cases. Specialty centers, including orthopedic and sports injury clinics, are expanding steadily with rising demand for customized and minimally invasive treatments. Other end-users, such as rehabilitation facilities and ambulatory centers, contribute niche demand. The dominance of hospitals reflects their broad service capacity, while specialty centers capture growth from focused care delivery.
Key Growth Drivers
Rising Incidence of Orthopedic Injuries
The increasing prevalence of fractures, sports injuries, and trauma cases significantly drives the orthopedic splints market. Growing participation in high-impact sports, coupled with a rise in road accidents, contributes to higher injury rates requiring splinting solutions. Additionally, the global aging population is more prone to bone fragility and joint disorders, further fueling demand. Hospitals and specialty centers adopt advanced splints to provide effective stabilization and faster recovery. This consistent rise in injury-related cases positions splints as a critical component of orthopedic treatment worldwide.
- For instance, ARCH Medical Solutions operates over 700,000 square feet of manufacturing capacity across numerous ISO 13485-certified and FDA-registered U.S. facilities, leveraging a large network to enable scalable and large-volume production of implants and instruments.
Technological Advancements in Splint Materials
Continuous innovation in splint design and materials strengthens market adoption, especially with fiberglass and thermoplastic options replacing traditional plaster. Fiberglass splints are lightweight, water-resistant, and radiolucent, improving both patient comfort and diagnostic accuracy. Thermoplastic splints allow custom molding, supporting personalized treatment and rehabilitation. These advancements reduce complications, enhance durability, and shorten immobilization times. Growing preference for patient-friendly solutions accelerates the shift toward modern splinting technologies. Manufacturers investing in research and development capture competitive advantage by meeting rising demand for efficient, innovative, and sustainable orthopedic care products.
- For instance, Tecomet’s purpose-built orthopedic casting line can produce complex net-shape CoCr implant blanks. Using a lost-wax process, it can achieve tight tolerances of ±0.2 mm across a 50 mm span, before final precision machining and polishing.
Expansion of Healthcare Infrastructure
The expansion of hospitals, trauma care centers, and specialty clinics in emerging markets boosts orthopedic splint adoption. Increasing healthcare spending, insurance penetration, and government-backed initiatives to strengthen orthopedic care infrastructure fuel growth. Facilities are investing in advanced diagnostic and treatment technologies, creating opportunities for high-quality splint usage in both urban and rural areas. The shift toward outpatient care and rehabilitation centers further widens accessibility. This infrastructure development enhances patient reach and ensures timely treatment for fractures and injuries, positioning orthopedic splints as an essential component of modern healthcare delivery.
Key Trends & Opportunities
Shift Toward Customization and Patient Comfort
The market shows a strong trend toward customized splints that improve patient outcomes. Thermoplastic and 3D-printed splints allow individualized fitting, reducing complications such as skin irritation and improving rehabilitation results. Growing awareness of patient comfort and recovery times drives adoption of these solutions. Companies offering lightweight, breathable, and easily adjustable designs gain market traction. Customization also opens opportunities in pediatric orthopedics, where patient-specific needs are high. The trend highlights the industry’s transition from standardized immobilization methods to advanced, patient-centric solutions tailored for faster and safer recovery.
- For instance, CRETEX runs Direct Metal Printing (DMP) builds in its 30,000 sq ft additive hub, enabling the delivery of custom titanium implants from powder to finished part through a vertically integrated process.
Growth Opportunities in Emerging Markets
Emerging economies present significant opportunities due to increasing healthcare investments and a rising middle-class population. Countries in Asia-Pacific, Latin America, and the Middle East are witnessing higher demand for orthopedic treatments as access to healthcare improves. The surge in road accidents and trauma cases in these regions amplifies the need for splints. Government initiatives to modernize healthcare systems and expand trauma care infrastructure create favorable conditions for manufacturers. Companies entering these markets with cost-effective yet advanced splinting products are well-positioned to capture long-term growth potential.
- For instance, Viant expanded its Costa Rica medical device facility in Heredia in late 2022, adding over 90,000 square feet of cleanroom space and significantly enhancing production capacity for complex medical devices.
Key Challenges
High Cost of Advanced Splints
Despite clear clinical benefits, advanced fiberglass and thermoplastic splints are more expensive than traditional plaster options. This cost difference limits adoption in low-income regions and among patients lacking comprehensive insurance coverage. Hospitals in developing economies often prioritize cost over performance, restricting the penetration of modern splints. Additionally, reimbursement gaps in certain healthcare systems create financial barriers. Manufacturers must balance innovation with affordability to address diverse markets. The challenge lies in offering advanced solutions at competitive prices without compromising quality, durability, and patient comfort.
Limited Awareness in Rural and Underserved Areas
In many rural regions, awareness and access to advanced splints remain limited. Patients often rely on outdated or traditional methods of fracture care due to lack of resources, trained professionals, or infrastructure. This gap restricts the market potential in underserved areas despite growing demand. Furthermore, limited training among healthcare providers in adopting modern splinting techniques affects treatment outcomes. Bridging this gap requires stronger educational initiatives, supply chain improvements, and collaborations between manufacturers and healthcare systems to expand awareness and accessibility of advanced orthopedic splint solutions.
Regional Analysis
North America
North America leads the orthopedic splints market with a 38% share, driven by advanced healthcare infrastructure and high adoption of innovative splinting materials. Strong presence of leading manufacturers and wide insurance coverage enhance accessibility for patients. Rising cases of sports injuries and orthopedic conditions among aging populations fuel consistent demand. Hospitals and specialty centers integrate fiberglass and thermoplastic splints to improve patient comfort and recovery outcomes. Regulatory support for advanced medical devices further accelerates innovation and adoption. The region’s focus on quality healthcare and technology-driven treatment positions it as a dominant hub for orthopedic splint solutions.
Europe
Europe holds a 27% market share, supported by strong demand for advanced orthopedic care across key economies such as Germany, France, and the UK. The region benefits from government-backed healthcare systems and growing preference for patient-centric splints. Increasing geriatric population and rising musculoskeletal disorders drive consistent need for immobilization solutions. Emphasis on sustainable and lightweight materials, including fiberglass, supports innovation. Orthopedic clinics and rehabilitation centers in Europe prioritize customized splinting for faster recovery. The region’s strong research ecosystem and focus on high-quality healthcare services contribute to steady adoption, making it a significant contributor to global market growth.
Asia-Pacific
Asia-Pacific accounts for a 22% share of the orthopedic splints market, with rapid growth driven by expanding healthcare infrastructure in countries like China, India, and Japan. Rising trauma cases from road accidents and sports activities fuel demand for advanced splints. Increasing healthcare investments, coupled with government programs to strengthen trauma care, improve accessibility to modern solutions. Growing middle-class population and higher insurance penetration support affordability. Fiberglass and thermoplastic splints gain traction as hospitals shift from traditional plaster solutions. Asia-Pacific’s combination of large patient base, infrastructure expansion, and rising awareness positions it as a key growth frontier.
Latin America
Latin America holds an 8% share of the orthopedic splints market, driven by improving healthcare systems and rising orthopedic cases across Brazil, Mexico, and Argentina. Growth is fueled by increasing investments in trauma care and expanding access to modern hospitals. Road accidents and sports-related injuries drive steady demand for immobilization products. However, limited affordability in rural regions creates uneven adoption of advanced fiberglass splints. Governments and private players are investing in rehabilitation centers, opening opportunities for market expansion. Latin America’s improving healthcare accessibility and gradual adoption of innovative materials position it as an emerging regional contributor.
Middle East & Africa
The Middle East & Africa region contributes 5% to the orthopedic splints market, with adoption concentrated in urban centers such as the UAE, Saudi Arabia, and South Africa. Growing investments in healthcare infrastructure and medical tourism support demand for advanced orthopedic treatments. However, limited accessibility in rural and underdeveloped areas restricts widespread penetration. Increasing prevalence of road accidents and trauma cases fuels splint requirements across emergency care. Hospitals and specialty centers in wealthier nations adopt fiberglass and thermoplastic splints, while cost-sensitive markets still rely on plaster solutions. Gradual modernization makes the region a developing growth avenue.
Market Segmentations:
By Product:
- Fiberglass Splints
- Plaster Splints
By Application:
- Upper Extremity
- Shoulder
By End User:
- Hospitals
- Specialty Centers
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The orthopedic splints market features strong competition among leading players such as Esaote, Materialise NV, McKesson Corporation, Intellijoint Surgical, Merge Healthcare (IBM), Brainlab AG, Medstrat, Inc., DePuy Synthes, Carestream Health, and GE Healthcare. The orthopedic splints market is highly competitive, with companies focusing on innovation, material advancements, and patient-centric solutions to strengthen their presence. Market dynamics are shaped by the growing demand for lightweight, durable, and customizable splints that enhance recovery outcomes. Manufacturers increasingly invest in research and development to integrate advanced materials such as fiberglass and thermoplastics, offering superior comfort and functionality compared to traditional options. Digital technologies, including 3D printing and imaging integration, further support the customization trend. Strong distribution networks, strategic partnerships, and expansion into emerging markets remain central strategies, enabling players to capture a wider consumer base.
Key Player Analysis
- Esaote
- Materialise NV
- McKesson Corporation
- Intellijoint Surgical
- Merge Healthcare (IBM)
- Brainlab AG
- Medstrat, Inc.
- DePuy Synthes
- Carestream Health
- GE Healthcare
Recent Developments
- In June 2025, Dimension Ortho, along with Rothman Orthopaedics, announced a partnership to improve orthotic care through 3D printing orthopedic solutions. These two industry leaders aim to have custom-fit braces that lead to improved patient comfort and healing outcomes while modernizing the way orthopedics has traditionally treated patients.
- In January 2025, Aspen Medical Products acquired Advanced Orthopaedics to promote its offerings of spinal and orthopedic bracing products. In addition to advancing Aspen distribution capabilities, the acquisition will help Aspen branch into new orthopedic care markets throughout the United States.
- In June 2024, Zimmer Biomet and THINK Surgical signed a deal to distribute TMINI, a handheld robotic system for knee replacement surgery. This complements Zimmer Biomet's existing ROSA robotic arm system and offers surgeons more choices for knee replacement procedures.
- In January 2024, Enovis launched the DonJoy ROAM OA knee brace in the U.S. for patients with osteoarthritis. The brace contains two new telescoping hinges and magnetic buckles to improve patient mobility or comfort by offloading pressure from the knee joint that commonly causes pain for patients.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising orthopedic injuries and trauma cases worldwide.
- Fiberglass and thermoplastic splints will replace traditional plaster solutions at a faster pace.
- Digital technologies like 3D printing will drive demand for customized splints.
- Hospitals will continue to dominate adoption due to high patient volumes and trauma care needs.
- Specialty centers will gain traction with a focus on personalized orthopedic treatments.
- Emerging economies will present strong growth opportunities with improving healthcare infrastructure.
- Rising geriatric populations will increase demand for fracture stabilization solutions.
- Partnerships between manufacturers and healthcare providers will enhance product reach.
- Sustainability concerns will push innovation in eco-friendly splinting materials.
- Growing awareness of patient comfort will drive the design of lightweight, user-friendly splints.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Orthopedic Injuries
The increasing prevalence of fractures, sports injuries, and trauma cases globally is driving demand for orthopedic splints, as more patients require effective immobilization and stabilization solutions for recovery.
Technological Advancements in Splint Materials
Innovations in fiberglass and thermoplastic materials have led to lighter, more durable, and comfortable splints, encouraging healthcare providers to adopt advanced products that improve patient outcomes and reduce complications.
Expansion of Healthcare Infrastructure
Growth in hospitals, trauma centers, and specialty clinics, especially in emerging markets, is boosting the adoption of orthopedic splints by increasing access to modern treatment options and expanding the patient base.
Shift Toward Customization and Patient Comfort
The trend toward 3D-printed and custom-molded splints is enhancing patient comfort and rehabilitation outcomes, driving market growth as providers and patients seek more personalized and effective immobilization solutions.
Aging Population and Increased Mobility Needs
As the global population ages, the incidence of bone fragility and joint disorders rises, leading to greater demand for orthopedic splints to manage fractures and support mobility-preserving treatments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Orthopedic Splints Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Orthopedic Splints Market projected to grow between 2025 and 2032?
Which Orthopedic Splints Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Orthopedic Splints Market?
Who are the leading companies in the Orthopedic Splints Market?
Which region commanded the largest share of the Orthopedic Splints Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Fiberglass Splints
- 1.2.2 Plaster Splints
- 1.2.3 Thermoplastic Splints
- 1.2.4 Tools and Accessories
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Specialty Centers
- 1.3.3 Rehabilitation Facilities
- 1.3.4 Ambulatory Centers
- 1.4 By Application
- 1.4.1 Lower Extremity
- 1.4.2 Upper Extremity
- 1.4.3 Shoulder
- 1.4.4 Wrist
- 1.4.5 Knee & Ankle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.06 billion → 2032: USD 4.75 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Splints Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Splints Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Splints Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Splints Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Splints Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Splints Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Splints Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Splints Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.06 billion → 2032: USD 4.75 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Splints Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fiberglass Splints
- 12.3.7.2 Plaster Splints
- 12.3.7.3 Thermoplastic Splints
- 12.3.7.4 Tools and Accessories
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Specialty Centers
- 12.4.7.3 Rehabilitation Facilities
- 12.4.7.4 Ambulatory Centers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Lower Extremity
- 12.5.7.2 Upper Extremity
- 12.5.7.3 Shoulder
- 12.5.7.4 Wrist
- 12.5.7.5 Knee & Ankle
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Splints End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Splints Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Splints Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Splints Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Becton, Dickinson and Company
- 18.4 Breg, Inc.
- 18.5 DeRoyal Industries, Inc.
- 18.6 DJO Global
- 18.7 Dynatronics Corporation
- 18.8 Essity AB
- 18.9 Medi GmbH & Co. KG
- 18.10 Orthosys
- 18.11 Zimmer Biomet
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

