
Cocoa Liquor Market Overview:
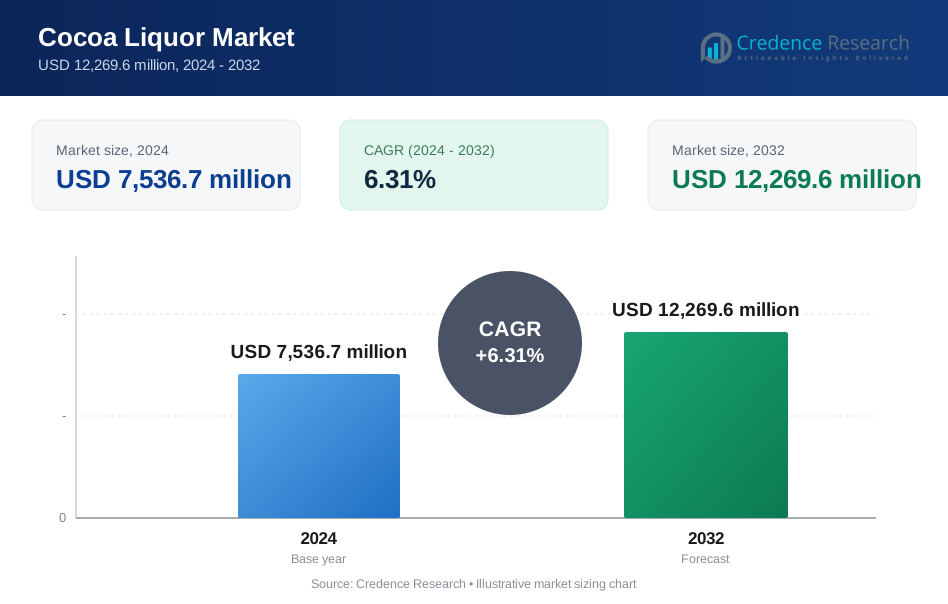
The global cocoa liquor market size was valued at USD 5,287.9 million in 2018, increased to USD 7,536.7 million in 2024, and is anticipated to reach USD 12,269.6 million by 2032, at a CAGR of 6.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cocoa Liquor Market Size 2024 | USD 7,536.7 Million |
| Cocoa Liquor Market, CAGR | 6.31% |
| Cocoa Liquor Market Size 2032 | USD 12,269.6 Million |
Top players in the global cocoa liquor market include Callebaut AG, Cargill Incorporated, Olam International Limited, JB Foods Ltd, and Nestlé S.A. These companies leverage strong sourcing networks, advanced processing facilities, and diversified product portfolios to meet global demand. Callebaut and Cargill lead with integrated value chains and sustainability initiatives, while Olam and JB Foods focus on traceable origin-based offerings. Nestlé utilizes in-house cocoa liquor capabilities for premium chocolate lines. Europe is the leading region in the cocoa liquor market, holding a 27.81% share in 2024, driven by high per capita chocolate consumption and a strong presence of artisanal and industrial chocolate manufacturers.

Cocoa Liquor Market Insights
- The global cocoa liquor market was valued at USD 7,536.7 million in 2024 and is projected to reach USD 12,269.6 million by 2032, growing at a CAGR of 6.31% during the forecast period.
- Rising global demand for chocolate, especially dark and premium varieties, continues to drive cocoa liquor consumption in both developed and emerging economies.
- Ethical sourcing, single-origin formulations, and clean-label preferences are shaping innovation in cocoa liquor blends and artisanal chocolate offerings.
- The market remains moderately consolidated, with key players like Callebaut AG, Cargill, and Olam expanding through vertical integration and sustainability programs, though price volatility of cocoa beans limits margin stability.
- Europe led with 27.81% market share in 2024, followed by Asia Pacific at 32.99%, while Forastero dominated the cocoa variety segment with over 70% share; the paste or liquid form held more than 60% share due to ease of use in large-scale chocolate production.
Cocoa Liquor Market Segmentation Analysis:
By Product Type
Natural cocoa liquor dominates the global market, accounting for over 58% of the product type segment. Its wide use in premium chocolate formulations and artisanal confectionery drives demand. The unalkalized nature of natural liquor retains higher polyphenol content, appealing to health-conscious consumers. Manufacturers prefer natural cocoa liquor for its intense flavor and minimal processing, aligning with clean-label trends. Dutch cocoa liquor, though less prevalent, finds favor in recipes requiring milder taste and darker color, particularly in bakery and ready-to-drink beverages.
- For instance, Barry Callebaut produces natural cocoa liquor using roasted and ground cocoa nibs without alkalization. The liquor is processed at controlled temperatures below 90 °C to preserve flavor compounds.
By Cocoa Variety
Forastero holds the largest market share, contributing more than 70% of the cocoa liquor market by variety. It remains the industry standard due to high yield, disease resistance, and cost-effectiveness. Bulk chocolate manufacturers rely on Forastero for its strong flavor and consistent supply from West Africa. Criollo, though rare, gains traction in premium and specialty chocolate due to its superior aroma and low bitterness. Trinitario, a hybrid of Forastero and Criollo, balances flavor and resilience, supporting niche and gourmet applications.
- For instance, Olam Food Ingredients sources Forastero cocoa beans from Côte d’Ivoire and Ghana. The company manages traceable supply chains covering millions of cocoa trees.
By Form
Paste or liquid form leads the market, with a share exceeding 60%, primarily due to its compatibility with automated chocolate processing systems. It ensures easier handling, faster melting, and consistent texture in confectionery manufacturing. High-volume producers prefer liquid cocoa liquor to reduce processing time and energy costs. Solid blocks serve smaller-scale or traditional processors who prioritize storage stability and batch-controlled melting. Demand for liquid form continues to rise with the expansion of industrial-scale chocolate production and advancements in liquid handling technologies.
Cocoa Liquor Market Key Growth Drivers
Rising Global Chocolate Consumption
The increasing demand for chocolate, especially in emerging economies, drives the cocoa liquor market significantly. Cocoa liquor is a core ingredient in chocolate production, and its consumption rises in tandem with confectionery growth. Markets like India, China, and Southeast Asia show rising per capita chocolate consumption, supported by urbanization, growing middle-class incomes, and Western dietary preferences. In developed regions, demand for dark and premium chocolate further accelerates cocoa liquor use. Manufacturers expand capacity and diversify product portfolios to cater to this growing chocolate base, driving steady volume growth. Seasonal sales spikes during holidays and gifting seasons also boost production cycles. With global chocolate consumption expected to continue rising, cocoa liquor remains integral to maintaining flavor, texture, and quality in various confectionery applications, making it a critical driver of market expansion.
- For instance, Barry Callebaut operates cocoa processing plants in Asia, Europe, and the Americas. The company processes cocoa liquor using controlled roasting and grinding systems.
Expansion in Artisanal and Premium Chocolate Segments
The growth of premium and artisanal chocolate segments worldwide enhances demand for high-quality cocoa liquor. Consumers increasingly seek products with authentic origins, rich flavor profiles, and ethical sourcing. Artisanal brands often use single-origin or specialty cocoa liquor to emphasize quality and traceability, supporting premium pricing strategies. This trend is particularly evident in North America, Europe, and Japan, where small-batch chocolate makers and bean-to-bar producers are gaining market share. These segments require consistent, flavor-rich cocoa liquor made from varieties like Criollo and Trinitario. As awareness of ethical sourcing and flavor complexity rises, so does the need for cocoa liquor with defined characteristics and minimal processing. This pushes suppliers to offer differentiated products and support traceability systems, aligning with consumer expectations in high-value markets and reinforcing cocoa liquor’s role in premium offerings.
- For instance, Valrhona sources cocoa liquor from single-origin farms across Latin America and Africa. The company produces liquor in small batches to preserve flavor complexity.
Health and Wellness Preferences Fueling Dark Chocolate Demand
Growing health consciousness supports increased consumption of dark chocolate, which typically contains a higher concentration of cocoa liquor. Dark chocolate is associated with antioxidant benefits, cardiovascular support, and mood enhancement, aligning with wellness trends. Cocoa liquor, rich in flavonoids and polyphenols, is a key functional component in these products. Consumers prefer lower-sugar, high-cocoa products, driving formulators to incorporate higher percentages of cocoa liquor. Health-focused branding and functional claims have gained traction in major retail channels, further boosting demand. Manufacturers also respond with cleaner labels, natural ingredients, and certifications like organic and non-GMO, where cocoa liquor quality plays a critical role. As the global functional food sector grows, cocoa liquor’s nutritional appeal contributes to its value in health-oriented chocolate innovations.
Cocoa Liquor Market Key Trends & Opportunities
Ethical Sourcing and Traceability Initiatives
Consumer awareness around sustainability and ethical sourcing is transforming supply chain practices in the cocoa liquor market. Buyers increasingly favor cocoa liquor sourced under fair trade, Rainforest Alliance, or UTZ certification schemes. Companies invest in traceability tools and direct farmer relationships to meet these requirements. Major chocolate manufacturers now include sustainability metrics in procurement goals, ensuring cocoa liquor supports social and environmental standards. Blockchain integration and origin-specific labeling help build consumer trust. This trend offers opportunities for suppliers who can verify responsible sourcing and supply premium cocoa liquor with transparent value chains. As regulations tighten and retailers demand compliance, traceable and ethically produced cocoa liquor gains competitive advantage and long-term viability in global markets.
- For instance, Olam Food Ingredients manages digital traceability systems covering cocoa farms across West Africa. The company tracks cocoa beans from farm gate to processing facility.
Product Innovation with Cocoa Liquor Blends
Manufacturers are exploring cocoa liquor blends tailored for specific product formats such as gourmet bars, spreads, and beverages. By combining cocoa liquor from multiple origins or varieties, companies create signature flavor profiles that appeal to niche markets. For instance, blending Criollo and Forastero allows premium brands to balance exotic aroma with cost efficiency. There’s also rising interest in cocoa liquor infused with natural flavors or enriched with functional ingredients like adaptogens. These innovations expand cocoa liquor’s role beyond traditional chocolate into health foods, bakery fillings, and ready-to-eat snacks. As demand for unique flavor experiences and cleaner formulations grows, such product development offers a promising route for differentiation and margin expansion across regions.
Cocoa Liquor Market Key Challenges
Volatility in Cocoa Bean Prices
Fluctuating cocoa bean prices pose a major challenge for cocoa liquor manufacturers. Price swings result from climate change, political instability in producing countries, and global supply-demand imbalances. Since cocoa liquor is directly derived from cocoa beans, cost structures face immediate pressure during price surges. Volatility affects profit margins, particularly for small and medium manufacturers lacking hedging capabilities. Uncertainty in pricing also complicates long-term contracts and planning cycles for both buyers and suppliers. Inconsistent bean quality further affects liquor consistency, impacting product outcomes. Addressing this challenge requires strategic sourcing, stronger supplier networks, and investments in sustainable farming practices to stabilize supply and reduce exposure to extreme price fluctuations.
Complexity in Processing and Storage Conditions
Cocoa liquor requires precise processing conditions to retain its flavor, texture, and microbial safety. Variability in fermentation, roasting, and grinding can impact the quality of the final product, especially in artisanal or decentralized production settings. Maintaining proper temperature and storage conditions for liquid or solid forms adds logistical complexity, especially in tropical or high-humidity environments. This creates barriers for manufacturers in emerging economies or for smaller players without advanced infrastructure. Moreover, the lack of standardization in processing methods leads to inconsistency in product specifications, making it difficult for end-users to maintain uniform formulations. Overcoming these issues involves investing in modern processing equipment, improved quality control systems, and industry-wide training on cocoa liquor handling best practices.

Cocoa Liquor Market Regional Analysis
North America
North America accounted for 23.63% of the global cocoa liquor market in 2024, reaching USD 1,781.25 million, up from USD 1,274.91 million in 2018. The market is projected to hit USD 2,822.02 million by 2032, growing at a CAGR of 5.95%. Growth is driven by the rising demand for premium dark chocolate and artisanal brands across the U.S. and Canada. Health-conscious consumers increasingly favor cocoa-rich products with clean labels. Manufacturers expand retail distribution, while product innovations in functional chocolate also support market penetration in health and wellness segments.
Europe
Europe led the global cocoa liquor market with a 27.81% share in 2024, valued at USD 2,096.28 million, up from USD 1,427.73 million in 2018. It is forecast to grow to USD 3,545.92 million by 2032, registering a CAGR of 6.82%, the highest among all regions. The region’s dominance stems from high chocolate consumption, established confectionery brands, and strong demand for ethical sourcing. Germany, Switzerland, and Belgium lead innovation in bean-to-bar and single-origin chocolates, while increasing vegan and organic product demand further drives the region’s expansion.
Asia Pacific
Asia Pacific held a 32.99% share of the cocoa liquor market in 2024, reaching USD 2,486.36 million, from USD 1,757.16 million in 2018. It is projected to grow to USD 4,008.49 million by 2032, with a CAGR of 6.18%. Rising urbanization, growing middle-class income, and Western influence on dietary habits are boosting chocolate consumption in China, India, and Southeast Asia. Multinational brands are expanding local production to meet regional demand, while increased retail penetration and e-commerce channels support wider distribution of premium chocolate products.
Latin America
Latin America captured a 7.54% share of the global cocoa liquor market in 2024, reaching USD 568.59 million, up from USD 393.95 million in 2018. The market is forecast to reach USD 941.08 million by 2032, at a CAGR of 6.53%. As a key cocoa bean-producing region, Latin America benefits from vertical integration and origin-branding initiatives. Brazil and Ecuador drive regional consumption and export value-added chocolate. Growth is fueled by domestic premium chocolate brands, rising tourism-related confectionery sales, and export of fine-flavor cocoa liquor to North America and Europe.
Middle East
The Middle East held a 4.47% market share in 2024, with cocoa liquor revenue at USD 338.29 million, rising from USD 252.76 million in 2018. The market is set to reach USD 503.06 million by 2032, at a CAGR of 5.11%. Increasing demand for imported premium chocolates, rising disposable incomes, and urban retail growth are key drivers. The UAE and Saudi Arabia lead consumption due to higher consumer spending and international product availability. Regional confectionery manufacturers also begin sourcing cocoa liquor directly to ensure supply chain stability and cost efficiency.
Africa
Africa accounted for a 3.53% share of the global cocoa liquor market in 2024, valued at USD 265.94 million, up from USD 181.37 million in 2018. The market is projected to reach USD 449.07 million by 2032, expanding at a CAGR of 6.80%. As the world’s largest cocoa-producing region, Africa sees growing investment in local cocoa processing to boost value addition. Ghana, Côte d’Ivoire, and Nigeria lead processing capacity growth, supported by government initiatives. Domestic chocolate consumption is still emerging, but export of semi-finished products such as cocoa liquor is steadily rising.
Cocoa Liquor Market Segmentations:
By Product Type
- Natural
- Dutch
By Cocoa Variety
- Forastero
- Criollo
- Trinitario
- Others
By Form
- Solid Blocks
- Paste / Liquid Form
By End Use
- Food and Beverage
- Pharmaceuticals
- Personal Care & Cosmetics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The global cocoa liquor market features a moderately consolidated competitive landscape, led by key players such as Callebaut AG, Cargill Incorporated, and Olam International Limited. These companies maintain dominance through integrated supply chains, large-scale processing capacities, and global distribution networks. Strategic initiatives such as origin traceability programs, sustainability certifications, and bean-to-bar manufacturing support brand positioning and premium product offerings. Firms like JB Foods Ltd and United Cocoa Processor, Inc. cater to niche and regional markets with customized cocoa liquor grades. Multinational food and beverage companies including Nestlé S.A. and Mars Incorporated also influence market dynamics through in-house processing and high-volume sourcing. Companies invest in advanced fermentation and flavor development technologies to cater to premium chocolate and health-conscious consumer segments. Expansion into emerging economies, particularly in Asia Pacific and Latin America, remains a focus for growth. The competitive intensity continues to rise as firms prioritize innovation, ethical sourcing, and cost-effective processing to capture evolving demand.
Key Player Analysis
- Callebaut AG
- Cargill Incorporated
- Olam International Limited
- JB Foods Ltd
- United Cocoa Processor, Inc.
- EFKO Group
- Cemoi Group
- Nestlé S.A.
- Mars Incorporated
- Other Key Players
Recent Developments
- In April 2025, Hershey’s announced its intent to acquire LesserEvil, a maker of organic snacks. This move is designed to expand Hershey’s snacking portfolio into new categories and better-for-you options, complementing its core confection brands like Hershey’s, Reese’s, and Jolly Ranchers. The acquisition will enhance Hershey’s manufacturing capacity and deliver more options to consumers across eating occasions.
- In August 2024, Nestlé Health Science signed an agreement to acquire the global rights to VOWST, a next-generation probiotic product. Having commercialized VOWST since June 2023, this deal grants Nestlé full control over the development, commercialization, and manufacturing of VOWST, further strengthening its health science business.
- In May 2024, Ghirardelli partnered with Baa Baa Thai Tea to launch a new collection of eight frappe beverages, merging Ghirardelli’s renowned chocolate with innovative tea flavors. This collaboration aims to deliver a luxurious and unique beverage experience, reflecting Ghirardelli’s commitment to product innovation in new segments.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Cocoa Variety, Form, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for premium and single-origin cocoa liquor will rise with consumer focus on flavor and authenticity.
- Growth in dark chocolate consumption will continue to support high cocoa liquor content in formulations.
- Health and wellness trends will drive innovation in functional chocolate using antioxidant-rich cocoa liquor.
- Manufacturers will invest in sustainable sourcing to meet traceability and ethical standards.
- Processing technologies will improve to enhance flavor consistency and reduce energy consumption.
- Emerging markets in Asia and Latin America will see increased domestic production and consumption.
- Cocoa liquor blends will be developed for specific applications in bakery, spreads, and beverages.
- Strategic partnerships between producers and chocolate brands will strengthen supply security.
- Climate change adaptation in cocoa farming will become a priority to ensure long-term supply.
- Value-added cocoa liquor exports from Africa will increase as local processing capacity expands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Chocolate Consumption
Increasing demand for chocolate, especially in emerging economies, directly drives cocoa liquor consumption as it is a core ingredient in chocolate production. Growth in per capita chocolate intake in markets like India, China, and Southeast Asia, as well as premiumization trends in developed regions, support steady market expansion.
Expansion in Artisanal and Premium Chocolate Segments
The growth of premium and artisanal chocolate brands worldwide is boosting demand for high-quality, single-origin, and traceable cocoa liquor. Consumers are seeking authentic flavors and ethical sourcing, prompting manufacturers to innovate with specialty cocoa liquor blends.
Health and Wellness Preferences Fueling Dark Chocolate Demand
Rising health consciousness is increasing the popularity of dark chocolate, which contains higher concentrations of cocoa liquor and is associated with antioxidant and cardiovascular benefits. This trend is driving formulators to use more cocoa liquor in their products and to market cleaner, functional chocolate options.
Ethical Sourcing and Traceability Initiatives
Growing consumer awareness of sustainability and ethical sourcing is pushing manufacturers to invest in traceable supply chains and certification programs. Cocoa liquor sourced under fair trade or sustainability standards is gaining preference, supporting premium pricing and long-term market viability.
Product Innovation with Cocoa Liquor Blends
Manufacturers are developing cocoa liquor blends tailored for specific applications such as gourmet bars, spreads, and beverages. By combining different cocoa varieties and origins, companies can create unique flavor profiles and expand cocoa liquor’s use beyond traditional chocolate, driving new demand.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
Q: What is the current market size for the Global Cocoa Liquor market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Cocoa Liquor market projected to grow between 2024 and 2032?
Which Global Cocoa Liquor market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Cocoa Liquor market?
Who are the leading companies in the Global Cocoa Liquor market?
Which region commanded the largest share of the Global Cocoa Liquor market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Solid Blocks
- 1.2.2 Paste / Liquid Form
- 1.3 By End Use
- 1.3.1 Food and Beverage
- 1.3.2 Pharmaceuticals
- 1.3.3 Personal Care & Cosmetics
- 1.4 By Product Type
- 1.4.1 Natural
- 1.4.2 Dutch
- 1.5 By Cocoa Variety
- 1.5.1 Forastero
- 1.5.2 Criollo
- 1.5.3 Trinitario
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,536.7 million → 2032: USD 12,269.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cocoa Liquor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cocoa Liquor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cocoa Liquor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cocoa Liquor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cocoa Liquor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cocoa Liquor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cocoa Liquor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cocoa Liquor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,536.7 million → 2032: USD 12,269.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cocoa Liquor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solid Blocks
- 12.3.7.2 Paste / Liquid Form
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food and Beverage
- 12.4.7.2 Pharmaceuticals
- 12.4.7.3 Personal Care & Cosmetics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Natural
- 12.5.7.2 Dutch
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Cocoa Variety - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Forastero
- 12.6.7.2 Criollo
- 12.6.7.3 Trinitario
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cocoa Liquor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cocoa Liquor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cocoa Liquor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cocoa Liquor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Callebaut AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cargill Incorporated
- 18.4 Olam International Limited
- 18.5 JB Foods Ltd
- 18.6 United Cocoa Processor, Inc.
- 18.7 EFKO Group
- 18.8 Cemoi Group
- 18.9 Nestlé S.A.
- 18.10 Mars Incorporated
- 18.11 Barry Callebaut
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

